What Actually Happens on Ex Dividend Day
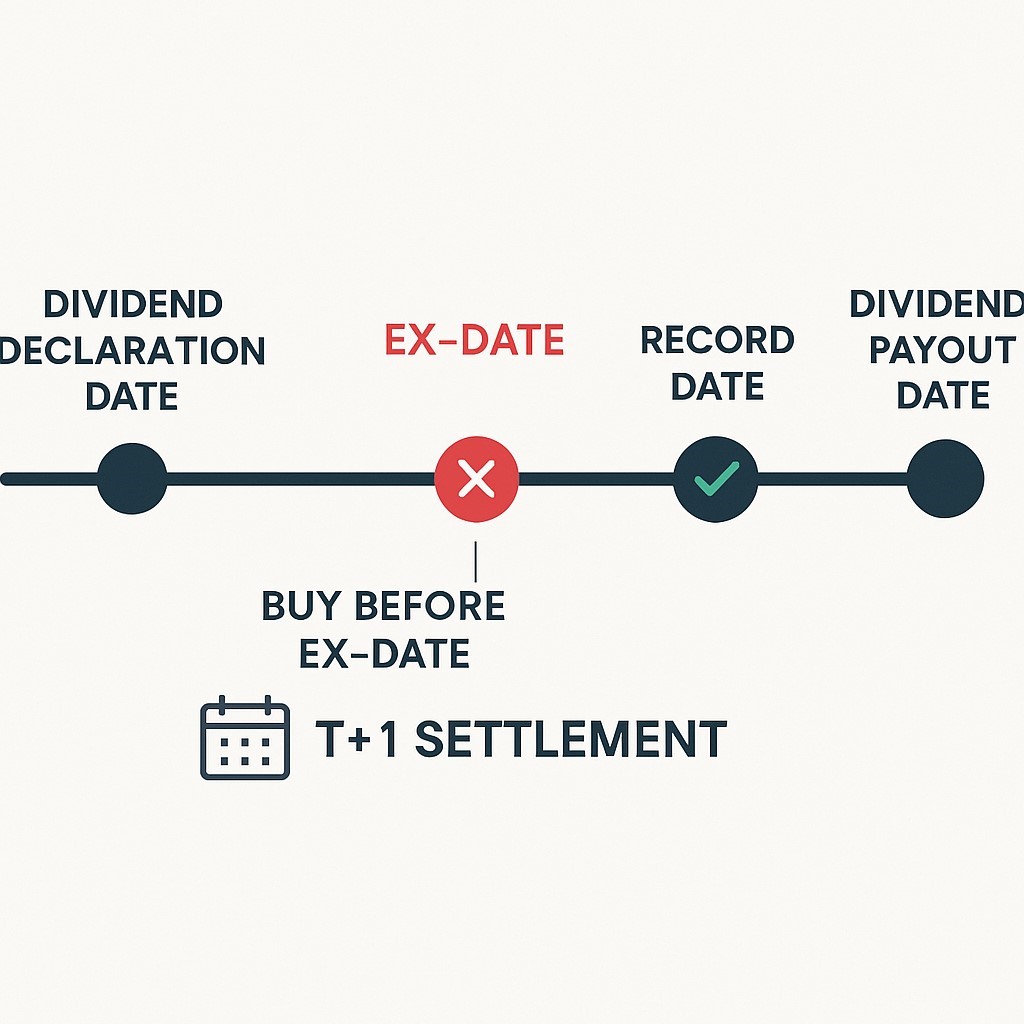
You see a stock dropping the day it goes ex-dividend and think you've found free money. That's usually not how it works. The price adjustment is real, but the mechanics around timing can quietly cost you more than they give you back if you're not paying attention. The ex dividend date is the first day a stock trades without entitlement to the upcoming dividend payment. If you buy on or after that date, you don't get the dividend. The seller keeps it. Buy before it, and you do. The stock typically opens lower by roughly the dividend amount because that cash is leaving the company's balance sheet. I spent years watching traders chase dividends the wrong way. They'd buy the day before ex, hold through the drop, and then wonder why their portfolio wasn't performing. The dividend isn't free money. It's your own money moving from one pocket to another, taxed along the way.
The Ex Dividend Date Explained The One Day That Can Change Your Trading Strategy
Here's the practical mechanism. Let's say Company XYZ announces a $0.50 per share quarterly dividend with an ex date of March 15th. If you buy on March 14th, you receive the dividend. If you buy on March 15th or later, you don't. The share price typically drops by approximately $0.50 on March 15th opening. You now own a stock worth less, but you have $0.50 in cash. Net position change is about zero before taxes. The real strategic question isn't whether you should chase the dividend. It's whether you can structure the trade to capture it while managing the tax consequence and the price drop simultaneously. That's where most people get it wrong. On the tax side, qualified dividends get taxed at the long-term capital gains rate. Non-qualified or ordinary dividends get taxed at your ordinary income rate. For most people in a higher bracket, the ordinary dividend tax rate can eat 30 to 40 percent of the dividend itself. A $500 dividend might only net you $300 after taxes. If the stock drops $500 on ex date and you hold for less than 31 days to sell, the capital gain or loss is also short-term and taxed at your ordinary rate. You're basically paying double ordinary rates on what should have been a clean trade.
There's a holding period requirement for qualified dividend treatment. You have to hold the stock for more than 60 days during the 121-day window that starts 60 days before the ex date. If you're day trading around ex dates, your dividends are almost certainly going to be classified as non-qualified. I learned this the hard way in 2019 when I built a small arbitrage strategy around ex dates on high-yield REITs. I thought I was capturing clean income. The IRS code had other plans. Every single dividend from those trades got reclassified as ordinary income on my tax return. I ended up owing an extra $2,400 that year that I hadn't planned for. The workaround was straightforward but tedious. I stopped trying to flip the stock and instead held through the required window. It killed the strategy's turnover but saved me from the tax surprise.
Get the Full Details
The Mechanics Most People Miss
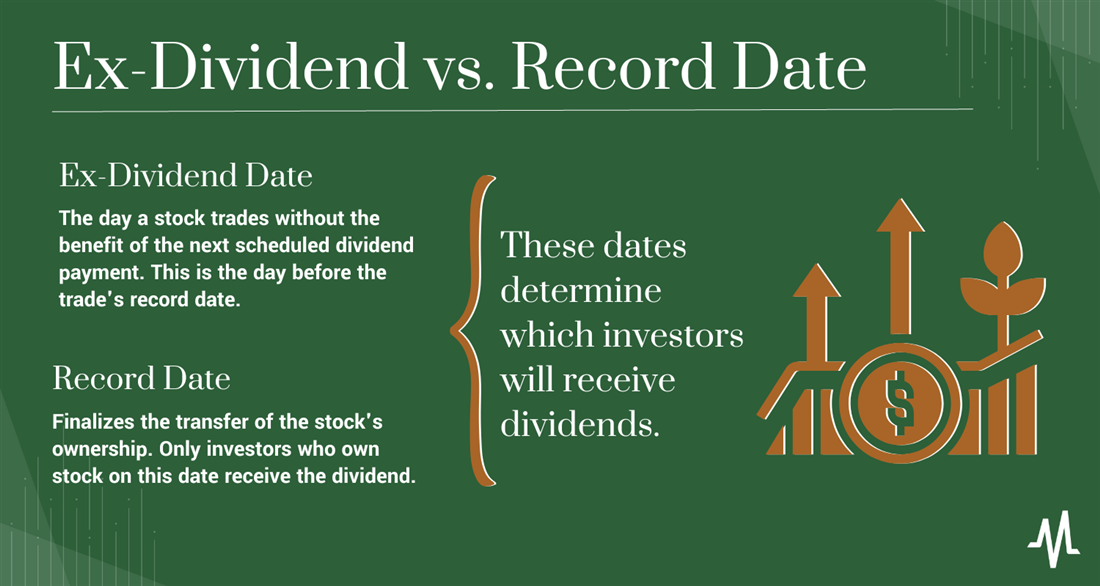
Record date matters less than you'd think for the average retail investor because of how brokerages handle settlement. Trades settle T+1 now in the US, which changed the math significantly from the old T+2 system. Under T+1, if you buy on the business day before the ex date, your trade settles the next business day, which is still before the record date. You get the dividend. Under the old T+2 system, you had to buy two days before ex. The shift to T+1 gave retail investors a little more flexibility but also made timing more confusing because the old mental models didn't update. International stocks add another layer. If you're trading ADRs or foreign-listed shares, the ex date rules can differ from US domestic securities. Some foreign markets use different settlement cycles. Some don't adjust the share price on ex date at all. I ran into this with a European utility ADR that announced a dividend with a UK-set ex date while the ADR traded on a US exchange. The price adjustment happened three days after the US ex date because the underlying settlement happened on the home market schedule. I bought thinking I was early and sold thinking I was safe. The dividend showed up late and the price move didn't match my model. I lost about 80 cents per share on the mismatch because I hadn't mapped the dual settlement calendar properly. Another thing people overlook is the cum-dividend price. The stock doesn't magically drop exactly by the dividend amount. Market forces, sentiment, and broader index movement can push the price up or down independently. On a strong market day, the stock might only drop 60 percent of the dividend amount. On a weak day, it could drop more. The dividend is a floor cushion, not a guarantee. If you're entering specifically to capture the dividend, you're betting that the price drop won't exceed the dividend minus taxes. That's a real bet.
How to Actually Trade Around Ex Dates
If you're going to structure a trade around an ex date, the first step is building a simple tracker. You don't need fancy software. A spreadsheet with the stock symbol, ex date, record date, pay date, dividend amount, dividend type (qualified or ordinary), and your intended hold period will cover 90 percent of what you need. I keep one open year-round because dividends aren't seasonal in a concentrated way. Utilities, REITs, and BDCs pay on different schedules throughout the year. The second step is knowing your tax bracket and whether the dividend qualifies. Check the IRS guidelines or your brokerage's tax documents. Some brokerages label dividends as qualified or non-qualified on your 1099-DIV. If your brokerage doesn't provide that breakdown upfront, request it. Form 1099-DIV box 1b covers qualified dividends. Box 1a covers total ordinary dividends. The difference is what gets taxed at the preferential rate versus your ordinary rate. For the actual trade execution, the cleanest approach is buying before the ex date and holding through the qualification window if you want qualified treatment. That means holding for at least 61 days from the ex date for most common stocks. If you're okay with ordinary dividend taxation, you can sell sooner, but factor in the higher tax hit. The math changes quickly. A 2 percent dividend on a $100 stock looks attractive until you realize a 37 percent ordinary tax rate leaves you with 1.26 percent net, and the stock dropped $2 on ex date. You're down 0.74 percent before even considering transaction costs.
Options can hedge the price drop risk. Buying a protective put before the ex date gives you downside protection while you collect the dividend. The cost of the put varies. For a typical large-cap stock paying a 2 percent annualized dividend, a 30-day put might cost 0.5 to 1.5 percent of the stock value depending on implied volatility. If IV is elevated around earnings season, the put gets expensive and the hedge eats into your dividend capture. I've seen cases where the put cost nearly matched the dividend, making the whole strategy pointless. Check the implied volatility skew before entering. If the put is priced rich, skip the hedge and accept the risk, or wait for a different setup. Short selling the stock on or after the ex date while holding a long position is another tactic some traders use to neutralize the price drop. You're essentially creating a synthetic position where the dividend receipt offsets the short's obligation to pay the dividend to the lender. The lender of the shares will demand dividend payment from you if you're short on or after ex date. This gets complicated fast with borrow costs and rebate rates. If the stock has a high short interest and tight borrow availability, the cost of maintaining the short can exceed the dividend benefit. I once tried this on a mid-cap tech stock with a 18 percent short interest and a borrow fee of 12 percent annualized. The dividend was 1.5 percent. The short cost wiped out the trade before I even entered. The lesson was obvious in hindsight but easy to miss if you're focused only on the dividend side.

When the Strategy Falls Apart
The dividend capture strategy fails in several common scenarios. The first is when the market moves against you on ex date. A broad sell-off can drop the stock well below the dividend-adjusted level. You capture the dividend but lose more on the position. The second is when the company suspends or cuts the dividend after you've already bought. I saw this happen with a regional bank in 2020. The stock went ex dividend, dropped as expected, and then the company announced a dividend cut two weeks later. The stock fell another 15 percent. I held through the ex date expecting to sell into a recovery that never came. The dividend was the only bright spot and it was still taxed as ordinary income because my hold period was too short. A third failure mode is transaction cost creep. If you're trading small positions and paying per-trade commissions plus spread costs, the math can turn negative quickly. Even with zero-commission brokers, the bid-ask spread on less liquid names can be 10 to 50 cents on a $20 stock. That's half a percent to two and a half percent round trip. Against a dividend that might be 0.5 percent per quarter, the spread alone can erase the edge. The fourth is reinvestment risk. You capture the dividend, the stock drops, and you reinvest at a lower price. That sounds good on paper but only if the stock recovers. If the company is fundamentally deteriorating, the lower price reflects reality. You're just buying more of a losing position at a discount. I held a dividend stock through three consecutive ex dates over 18 months. Each time I collected the dividend and reinvested. The stock price dropped 40 percent over that period. The dividends covered maybe 8 percent of the loss. The strategy felt productive because I was collecting income. In reality, I was just averaging down into a declining asset with extra tax friction.
If you're going to trade ex dates, the most practical alternative to pure dividend capture is using it as a filter for quality. Look for companies with consistent dividend histories, manageable payout ratios, and stable cash flows. A dividend isn't just income. It's a signal about management's confidence in future earnings. If a company has raised its dividend for 10 consecutive years and the payout ratio is under 60 percent of free cash flow, the ex date trade becomes less about timing and more about owning a fundamentally sound business at a reasonable entry point. That's a much more durable strategy than trying to arbitrage the price drop.
A Realistic Workflow
Start each quarter by pulling the upcoming ex date calendar for the stocks you already own or are watching. Most brokerages and financial data sites publish these. Filter for dividends above 1.5 percent annualized yield because anything lower rarely justifies the additional complexity. Check the dividend type. Qualified dividends get preferential tax treatment. Ordinary dividends don't. Note the record and pay dates. The pay date is when the money actually hits your account, usually 2 to 4 weeks after the ex date. Before entering a trade, calculate the after-tax dividend. Take the gross dividend, subtract the estimated tax at your marginal rate, and compare it to the expected price drop. If the stock is likely to drop the full dividend amount and your after-tax net is less than 0.5 percent, the trade is marginal at best. Factor in the spread cost and any options hedge expense. Only proceed if the remaining edge is meaningful. Set your exit plan before you buy. Are you holding through the qualification period? Selling immediately after ex? Using a stop? Write it down. Emotional decisions around ex dates tend to produce mediocre outcomes because the trade already has thin margins. If you don't have a plan, you'll hold too long hoping for a recovery that may not come, or sell too early and miss the rebound.

The ex dividend date itself is just a mechanical checkpoint. What matters is what you do before it and after it. Most traders focus on the day itself and ignore the tax and cost implications that determine whether the strategy actually adds value. The difference between a profitable ex date trade and a costly mistake usually comes down to whether you accounted for those hidden factors before you pressed buy.


