What Happened To A Regional Mall That Started In 1980
The Shops At Northfield opened in 1980 on the edge of Northfield, Minnesota, just south of the metro area near the University of Minnesota campus. It was built as a traditional enclosed regional mall with anchors like JCPenney and Marshall Field's (later Macy's). For most of its history it functioned exactly like any suburban mall: big-box anchors at either end, a food court in the middle, and a string of smaller retailers running along the corridors. Traffic followed the seasonal retail calendar. Back-to-school drives. Holiday foot traffic peaks. Nothing complicated about that model. The real shift started around 2018 when Sears closed its location there. That wasn't unique to Northfield, but it was a visible crack in the anchor strategy. One big anchor leaving doesn't kill a mall immediately, but it changes the physics of how the remaining space performs. You lose the draw that pulled people past your smaller tenants. Foot traffic drops maybe 15 to 20 percent at the anchors that remain because the destination value weakens. I saw this play out across several Midwest properties over the years.
The Evolution Of Shopping At The Shops At Northfield A Look Into The Past Present And Future
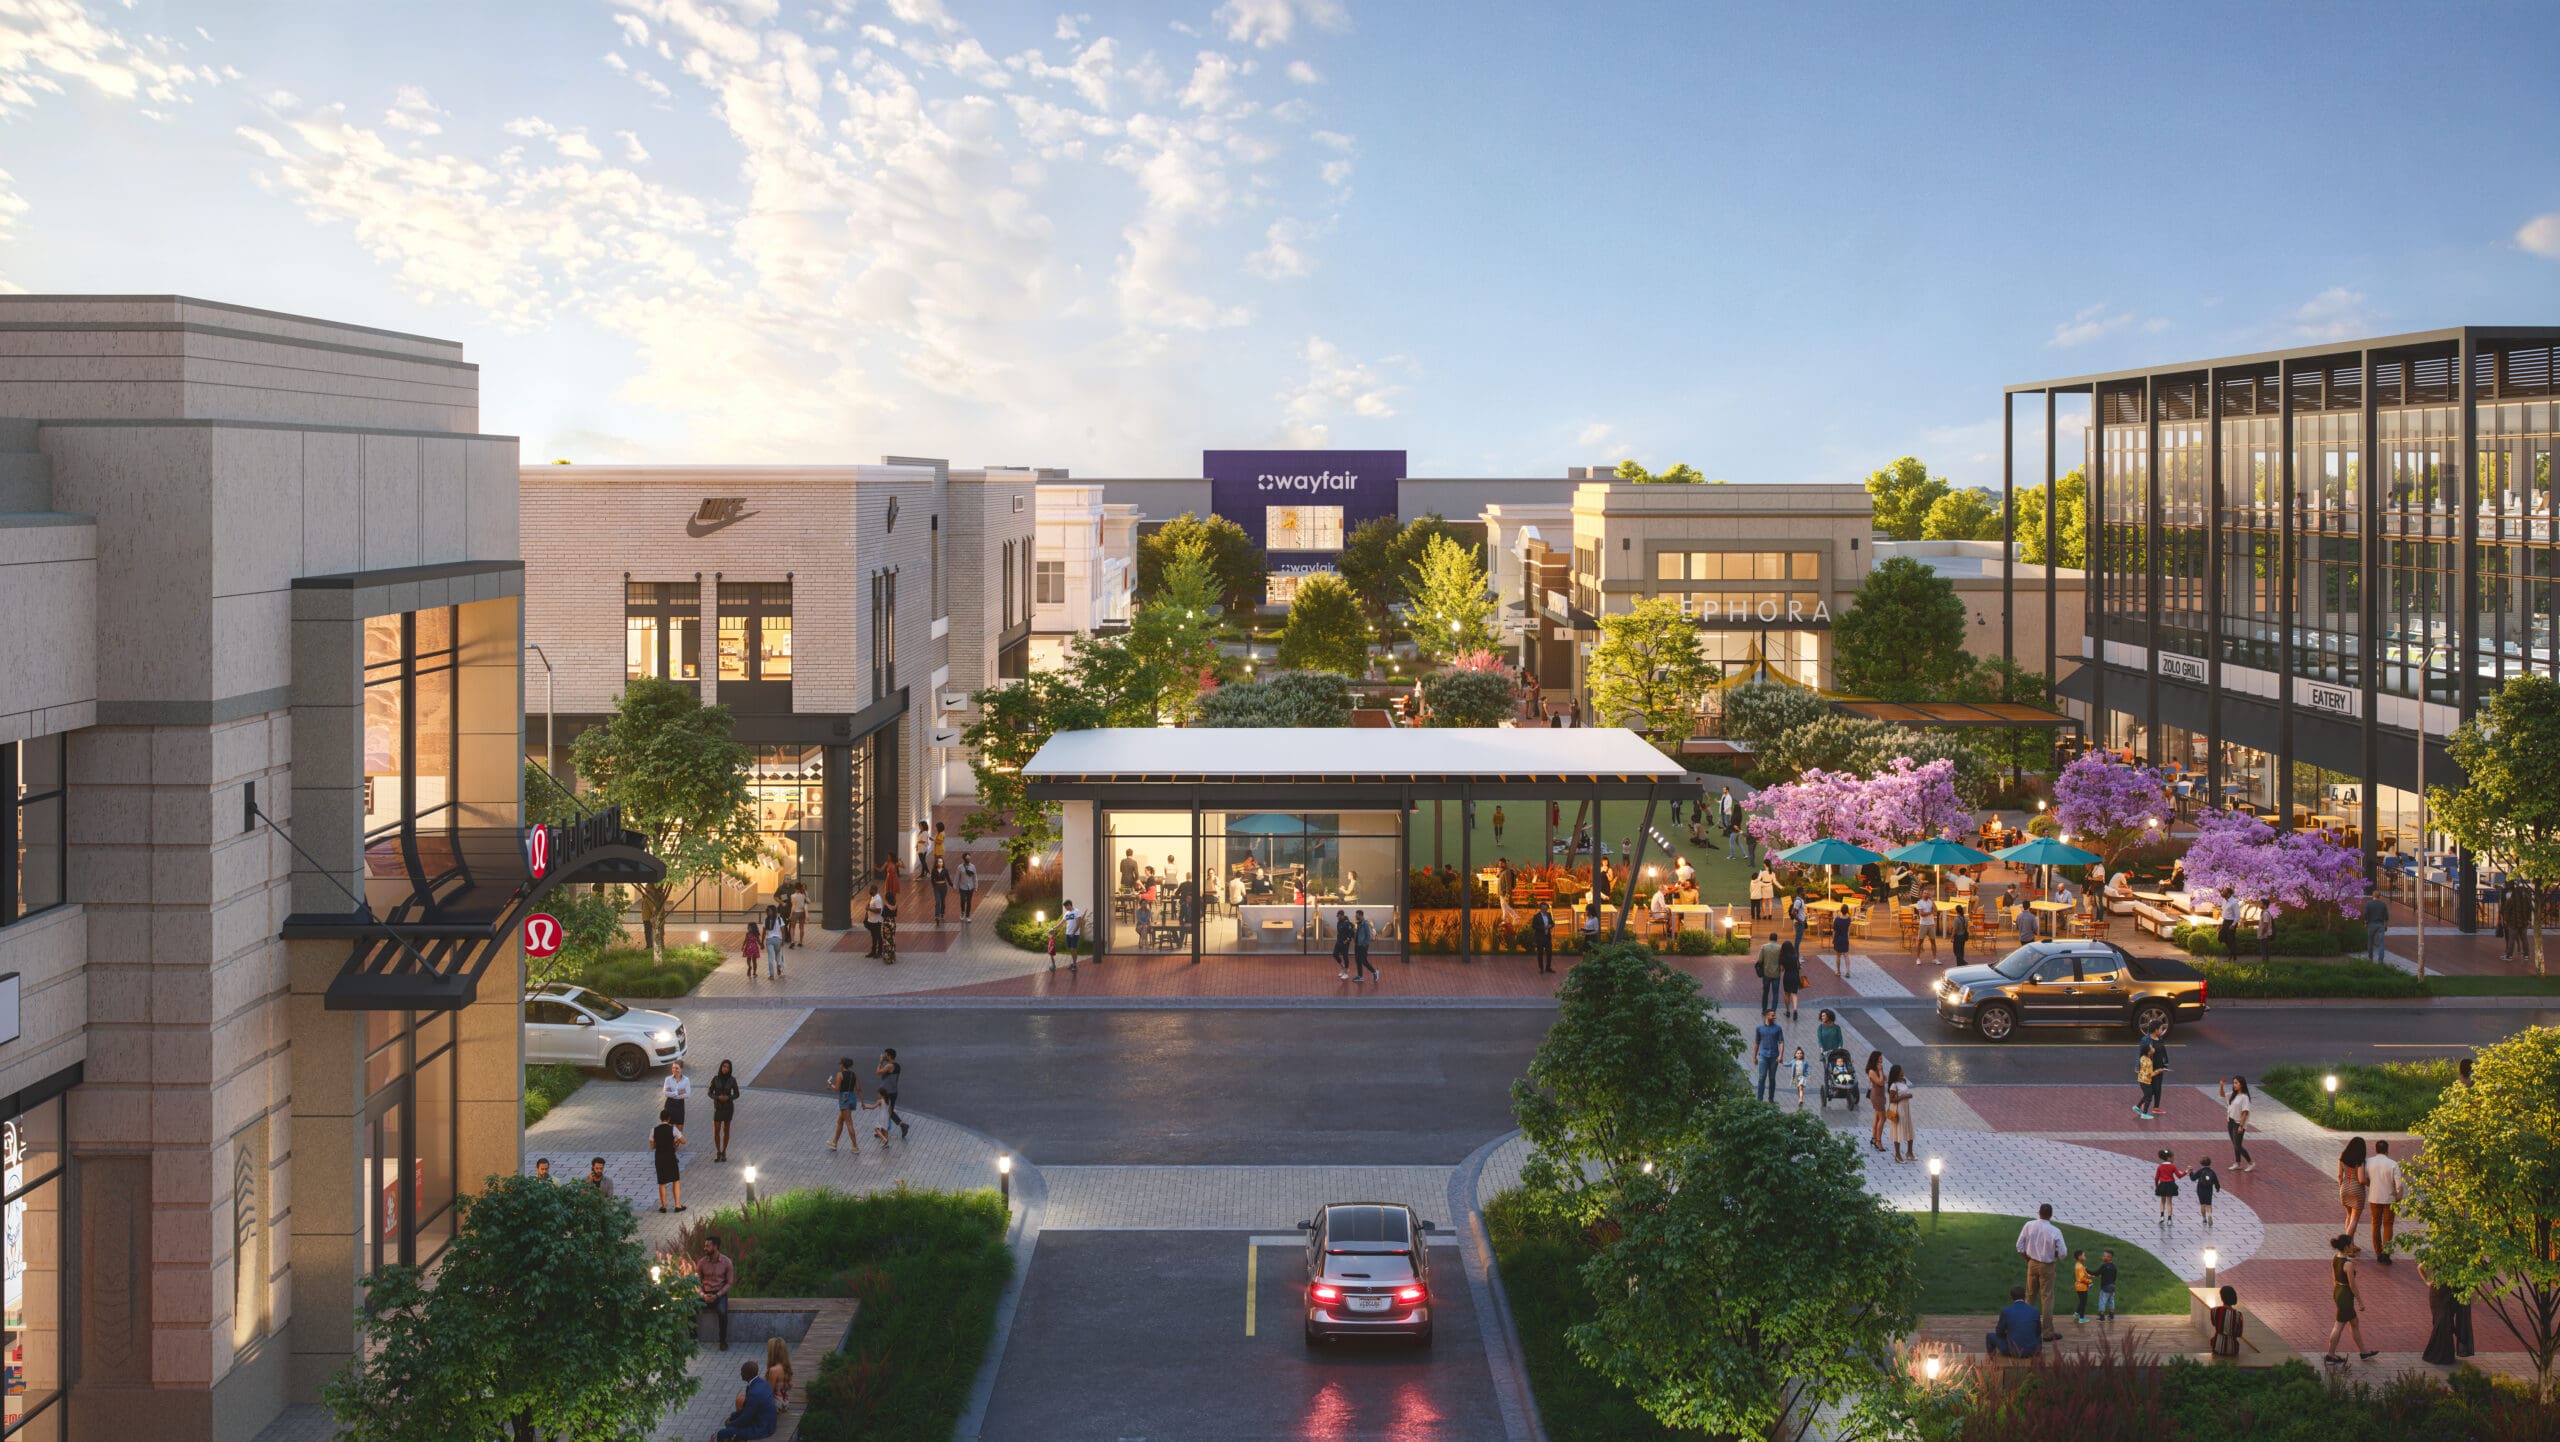
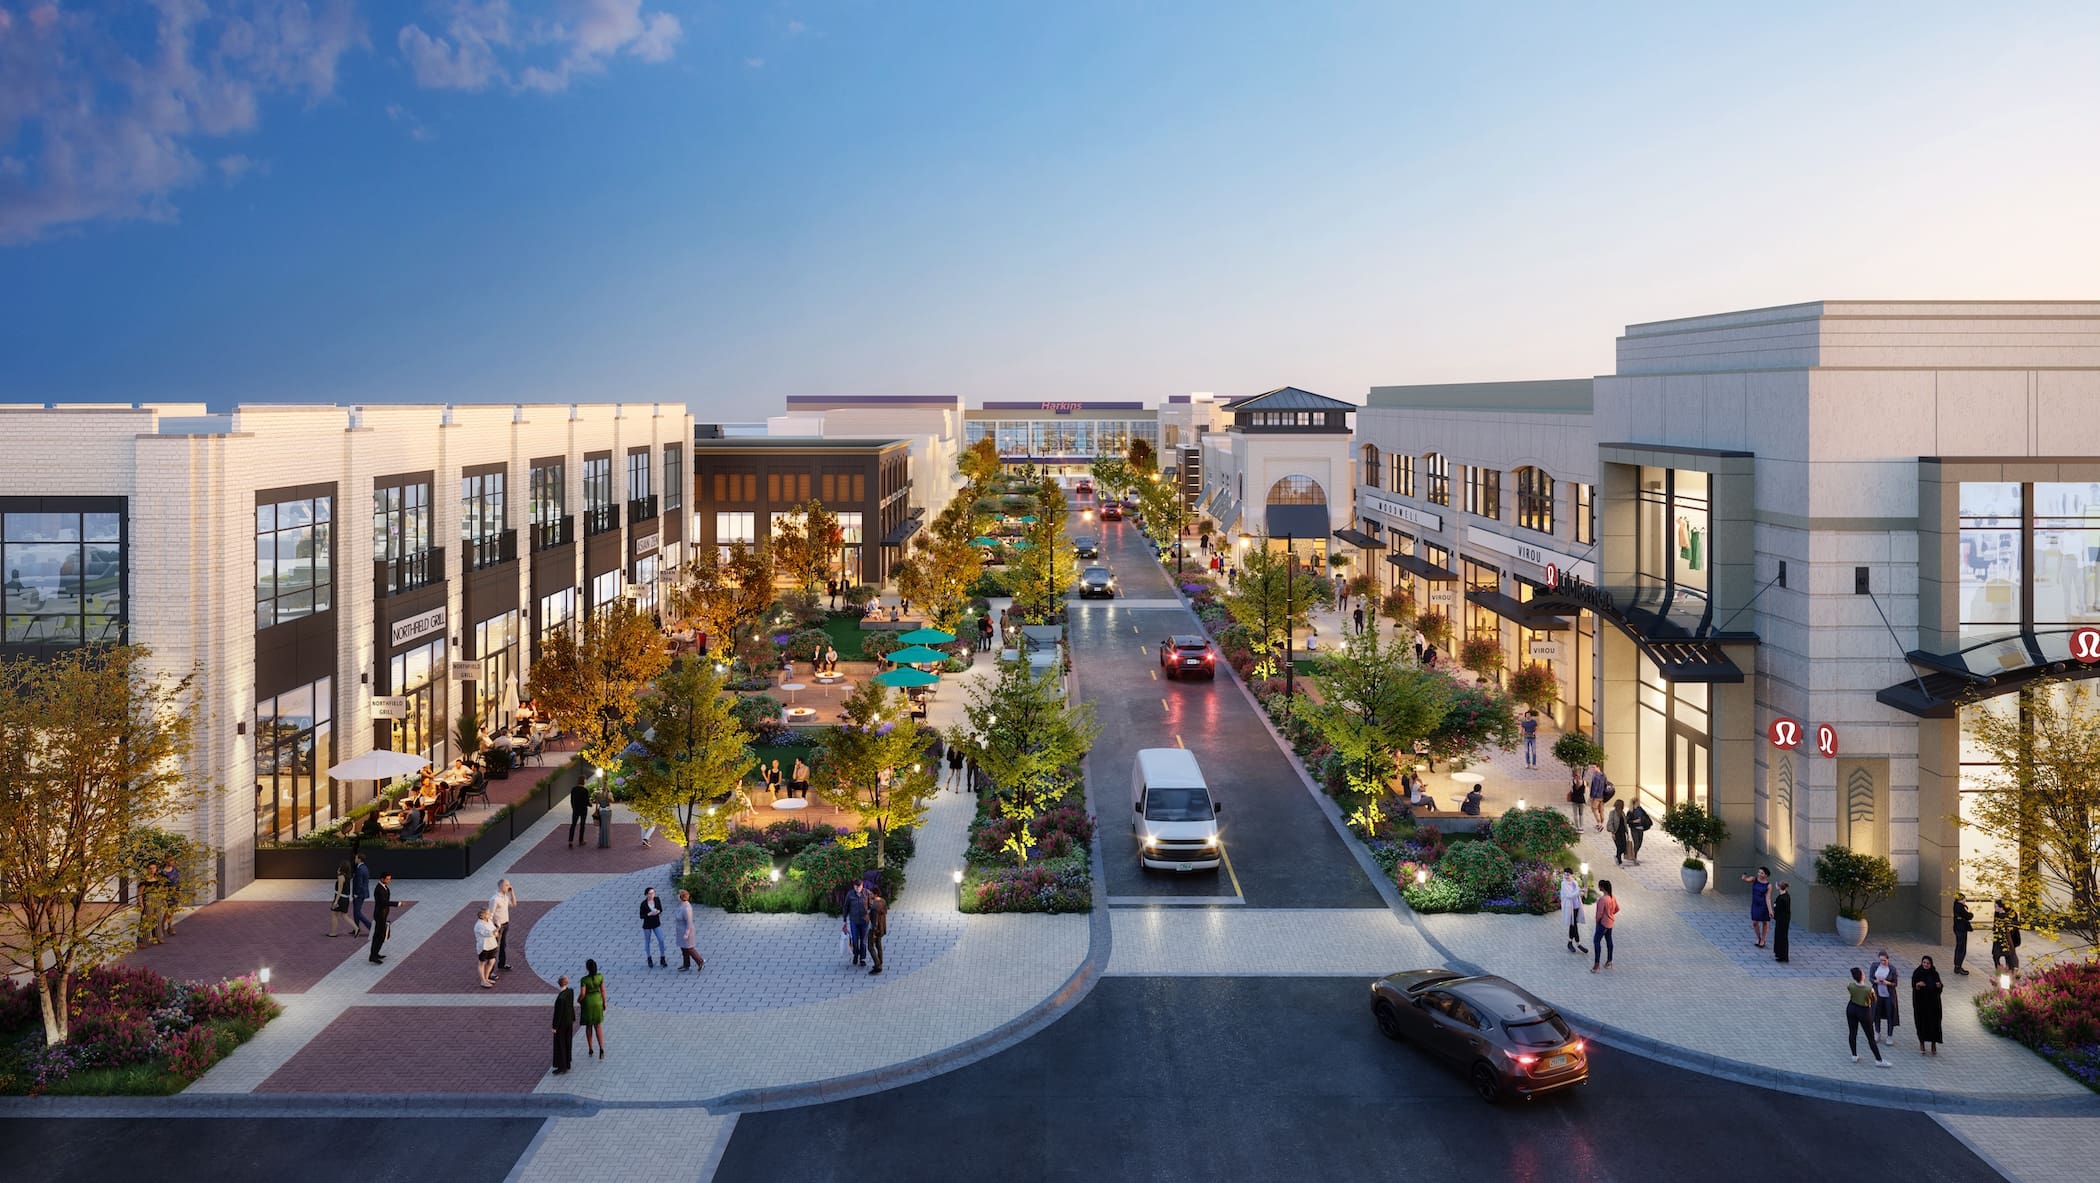
Here is the straightforward timeline. Past era was standard enclosed mall retail: department stores, national chains, predictable sales cycles. The present period is defined by adaptation attempts. The property has been repositioning toward a mixed-use format, integrating more dining options and rethinking how the remaining storefronts serve a smaller trade area. The future remains uncertain and is being shaped by broader retail trends rather than any specific master plan from the owners. What actually drives change at a property like this is the demographic radius. Northfield has roughly 24,000 residents. The surrounding area picks up college students from St. Olaf College and Carleton, which adds a fluctuating population of maybe 6,000 to 8,000 depending on the academic calendar. That student population is transient and price-sensitive. The year-round residents tend to be older and more established. These two groups shop differently. Understanding which one your tenant base serves matters more than you'd think.
How The Mall Adapted To Declining Department Store Traffic
When an anchor leaves, the immediate problem is vacancy. Empty space kills morale for the remaining tenants and makes the interior feel less safe and less inviting. The standard workaround is converting department store square footage into other uses. Sometimes that's more retail. Sometimes it's medical offices. Sometimes it's storage or logistics. At Northfield, the vacated space was slowly absorbed by neighboring retailers or left vacant during search periods. I worked a property conversion a few years back where we had a similar anchor departure. The trick is not to fill every vacancy with another retailer. Too many similar stores cannibalize each other and you end up with a string of stores closing in sequence. Instead, diversify. Put in services people can't get online. A salon, a pediatric clinic, a gym, a self-storage facility. Things that require physical presence. That strategy stabilized a property I managed for about three years before we sold it.
Get the Full Details
The Online Shopping Factor Nobody Talks About Correctly
Everyone mentions Amazon but doesn't explain the nuance. Online shopping hit regional malls harder between 2015 and 2020, then plateaued. What happened is that basic goods moved online first. Clothing, electronics, home goods. The categories that are easy to ship and easy to compare. What stayed in physical stores longer were experiences and immediate-purchase items. People still buy certain things in person because they want to try them on, touch them, or walk out with them today. The counter-intuitive part is that some malls actually saw traffic increase after the initial online shock. Not growth in sales, but growth in visits. People use malls as social spaces even when they aren't buying much. Food courts got busier. Entertainment tenants like movie theaters became more important. This is why the Shops At Northfield has likely leaned into dining and service-oriented tenants rather than fighting to bring back apparel anchors that no longer make financial sense.
Practical Challenges Of Managing A Transitioning Property
Maintenance costs don't drop just because occupancy drops. You still pay for heating, cooling, parking lot resurfacing, lighting, security. Those fixed costs per square foot of leased space increase as vacancies grow. I learned this the hard way at a property where we went from 90 percent occupied down to about 60 percent before we stabilized. The annual operating budget looked fine on paper until you divided expenses by actual gross leased area instead of total area. Then the numbers looked very different. A specific problem I ran into: We had a tenant whose lease had an operating expense clause based on total building square footage, not leased square footage. When three anchors left over 18 months, our CAM (common area maintenance) charges skyrocketed per-tenant because the same expenses were spread over fewer paying tenants. The workaround was negotiating lease amendments with remaining tenants to recalculate CAM based on occupied area, plus using reserve funds to cover the gap during the transition period. It bought us time to attract new tenants without driving everyone out with sudden expense increases.
What The Future Actually Looks Like For Properties Like This
There are a few possible paths. One is continued slow decline where vacancies persist and the property becomes a shadow of its former self. Another is successful repositioning into a mixed-use lifestyle center format. The third is complete redevelopment into something entirely different, like residential or industrial. Which path happens depends on land values, zoning, infrastructure, and local demand. The realistic assessment for The Shops At Northfield is somewhere between continued adaptation and gradual repositioning. The location has value. It sits on major road access with decent visibility. It has an existing building that can be modified rather than requiring a complete teardown. Those are advantages. The disadvantage is that the regional retail market is fundamentally smaller now than it was in 1995. A mall that made sense then may need to be half its original size to make sense today. The key metric nobody checks but should: sales per square foot of leased space, not just occupancy percentage. A mall at 75 percent occupancy with strong per-square-foot sales is healthier than one at 90 percent occupancy with declining sales. Tenants don't stay in dying properties. They leave when their individual performance drops, regardless of overall occupancy numbers. Watch the tenant turnover rate more than the vacancy rate.

Local economic conditions matter too. Northfield's economy is tied to higher education and healthcare. Those are relatively stable employers. That stability provides a floor for retail demand, but it also means the ceiling is capped. You won't see luxury retail here. You'll see value-oriented and service-oriented tenants. Understanding what that tenant mix looks like helps predict what kind of evolution the property will actually undergo.