Understanding The Shift From Combustion To Electric In Practice
The transition away from internal combustion has been happening for about a decade now, but the real acceleration started around 2020 when major OEMs committed their entire lineups to electric. This isn't a gradual change — it's a complete restructuring of how cars are designed, built, and sold. Manufacturing plants have to be redesigned. Battery supply chains, which barely existed at scale five years ago, now require millions of cell units. Charging infrastructure is being built from scratch in most markets. The competitive landscape has shifted so dramatically that companies who spent 80 years perfecting the internal combustion engine are suddenly on the same footing as Tesla and new Chinese players like BYD. What most people miss when they think about this is the sheer breadth of the impact. It's not just about swapping an engine for a motor. It's about battery supply chains, charging networks, software platforms, grid capacity, and the economic viability of dealerships that made most of their money on service and maintenance for gas cars. The entire automotive ecosystem is being recalibrated, and understanding what's actually happening beneath the surface is important if you want to evaluate where this is going next.
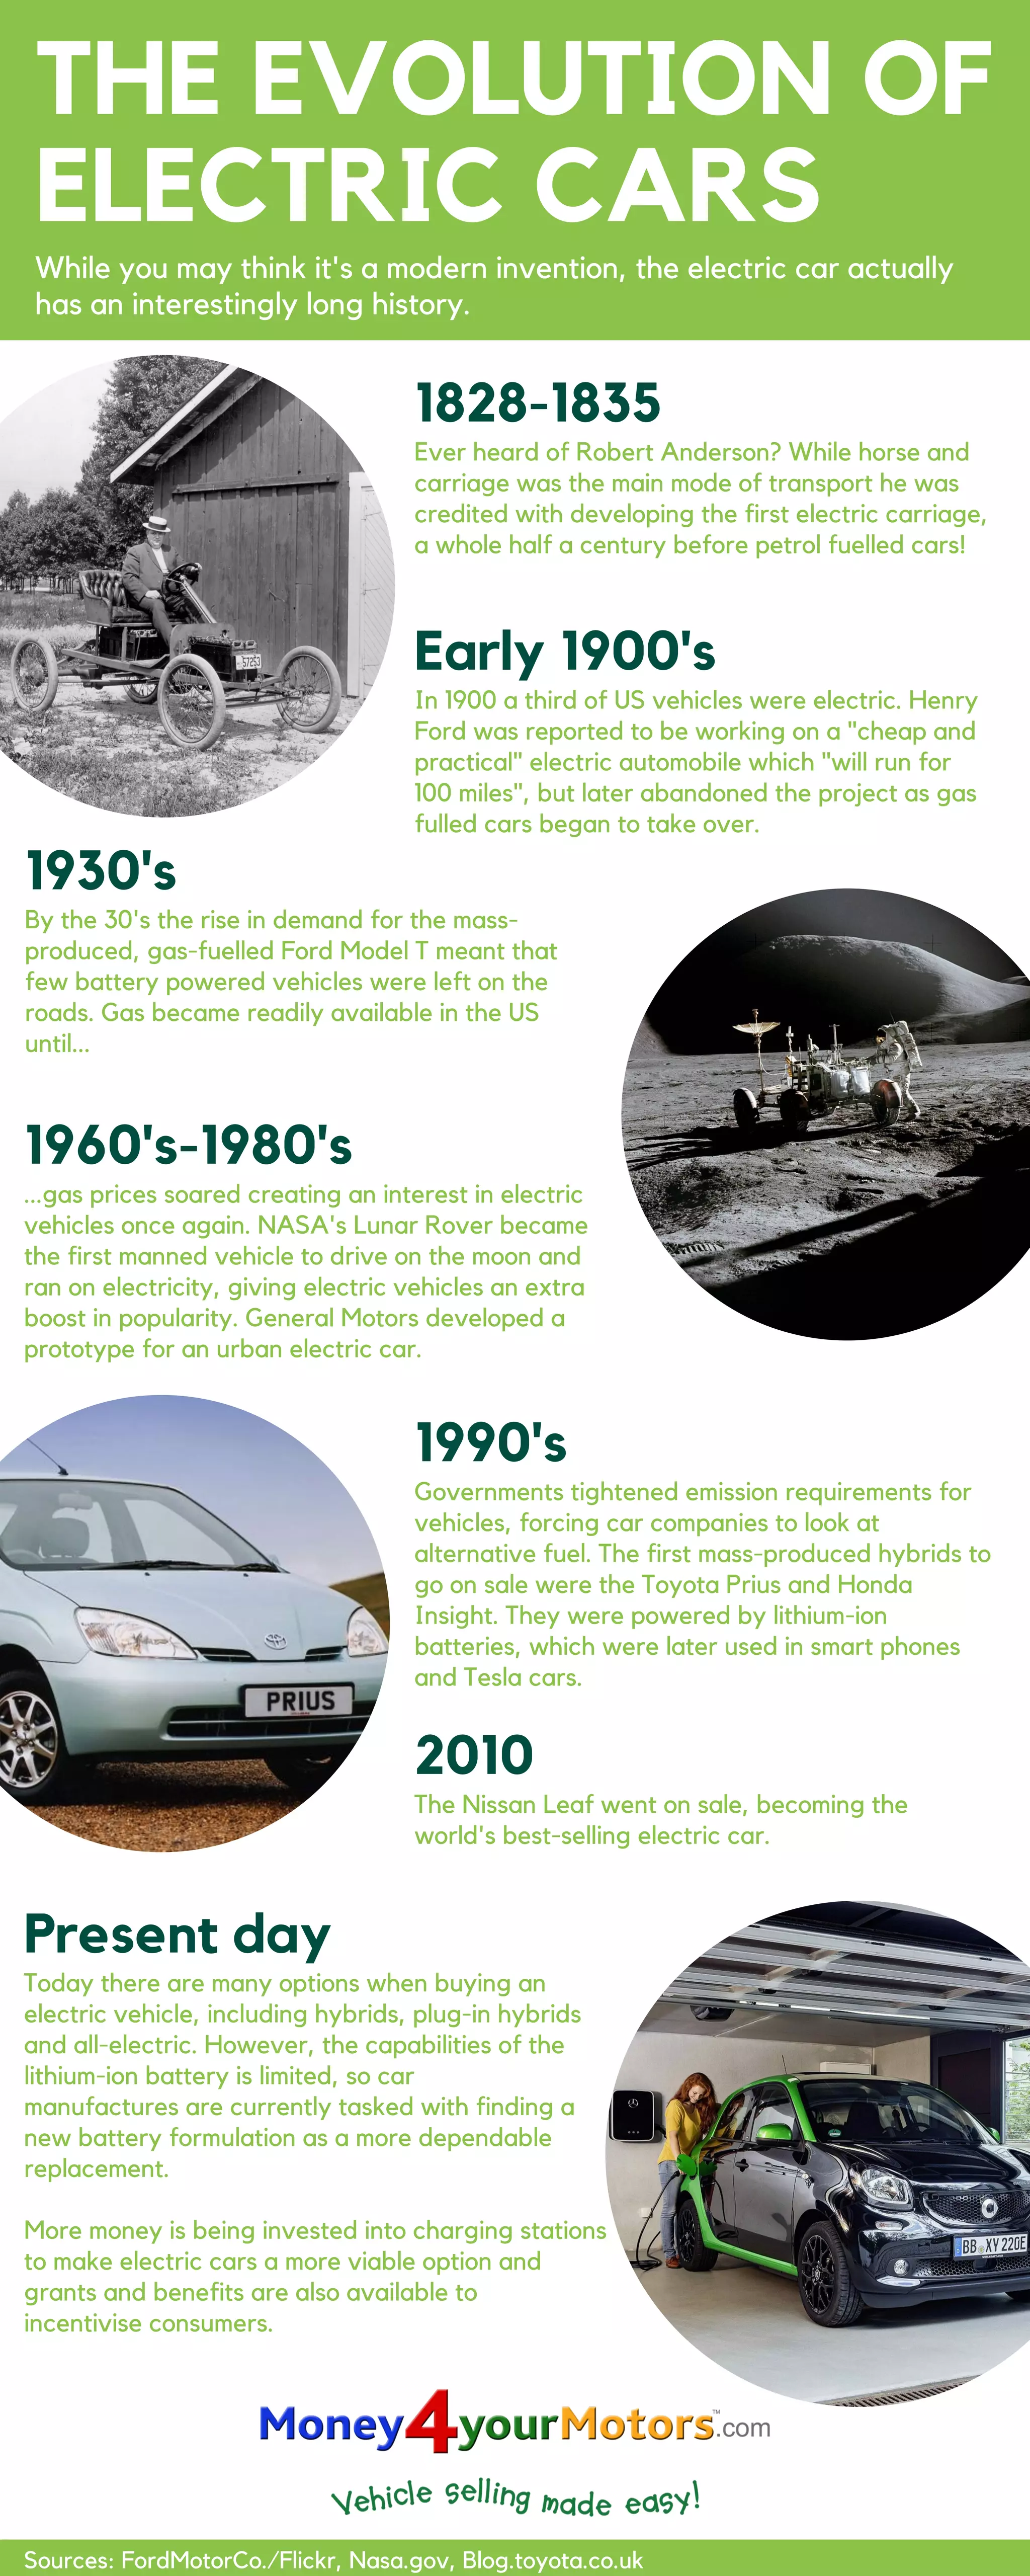
The Evolution Of Electric Cars A Gamechanger For The Automotive Industry
At its core, the transition is technically straightforward. You replace the engine, transmission, exhaust system, and fuel tank with a high-voltage battery pack, an electric motor or two, and a set of power electronics that manage energy flow. The car becomes lighter in some areas and heavier in others, but the packaging is far simpler — no complex drivetrain tunnels, no exhaust routing, fewer moving parts overall. Maintenance drops significantly because there's no oil to change, no spark plugs, no timing belts, and regenerative braking reduces wear on brake pads considerably. What most observers underestimate is that modern EVs are essentially computers that move. Tesla Model 3s and 6s can receive software updates over the air that add features, improve range estimates, or fix bugs months after you've driven the car off the lot. Traditional manufacturers are still struggling to build the organizational capability to do this. This isn't a minor difference — it's a structural one that separates companies that understand the new paradigm from those that don't. Battery chemistry is where things get interesting for anyone trying to understand the trajectory. Most production EVs use lithium-ion cells, but there are meaningful variations. NMC (nickel manganese cobalt) batteries dominate the long-range segment. LFP (lithium iron phosphate) is cheaper, has a longer cycle life, and doesn't rely on cobalt, which is why it appears in base-model vehicles like the standard-range Model 3 and many Chinese offerings. Sodium-ion is just beginning to enter production as a lower-cost alternative for entry-level vehicles. Solid-state batteries remain in the development phase despite years of press releases promising imminent commercialization — don't expect them in consumer vehicles before 2028 at the earliest, and even then the volumes will be modest.
The economics are still complicated and heavily subsidized in many markets. Most legacy manufacturers are still selling EVs at a loss or with significantly thinner margins than their ICE counterparts. The total cost of ownership usually favors electric when you factor in fuel savings and reduced maintenance over five to seven years, but the upfront purchase premium remains a barrier for a large portion of the market. Government incentives in the US, EU, and China have been critical in closing that gap, and policy shifts could change the math substantially in either direction.
Get the Full Details

What Actually Matters When Evaluating An EV Purchase Or Investment
The useful questions aren't the ones about range numbers or acceleration figures. Those are marketing points. The questions that matter are about how you actually use a vehicle and whether an EV fits that pattern. If you can charge at home, live in a region with moderate temperatures, and drive mostly within a 200-mile daily radius, an EV is likely the right choice for you. If you frequently take long road trips through areas with sparse charging infrastructure, live in an apartment without dedicated parking, or need a vehicle for heavy towing regularly, you should probably wait or look at a plug-in hybrid instead. Cold weather is one of those things that nobody warns you about until you experience it. Battery chemistry degrades in low temperatures, and while thermal management systems help, you can realistically expect a 20 to 30 percent reduction in range during sustained winter driving. I learned this the hard way when I purchased a used EV in Minnesota. The advertised range was 250 miles. In January, with the heater running and temperatures around zero Fahrenheit, I was getting closer to 180. The workaround was straightforward: pre-condition the battery while the car is still plugged in before you drive, which brings the pack to optimal temperature using grid power rather than draining the battery itself. This alone recovers most of the lost range on typical commutes. Charging speed is another area where the specs on paper don't match real-world usage. A car might advertise 200 kW peak charging, but that's only achievable within a narrow state-of-charge window, usually between 10 and 40 percent. As the battery approaches 80 percent, charging power tapers dramatically to protect cell longevity. A 15-minute stop at a fast charger typically adds 150 to 200 miles of range, not the 200 miles the headline number suggests. If you're doing road trips, plan around this reality rather than assuming the published charging curves are accurate for your actual experience.
The Supply Chain And Manufacturing Changes Nobody Talks About
Battery production is the single biggest bottleneck in the entire transition. Building a gigafactory costs between two and five billion dollars depending on capacity and location. The equipment is specialized. The raw materials — lithium, nickel, cobalt, graphite — come from a concentrated set of mining and refining operations, many of which are in politically unstable regions or subject to export restrictions. China currently controls roughly 60 to 70 percent of global battery cell manufacturing and an even larger share of refining. This isn't a temporary imbalance — it's a structural dependency that the US and EU are trying to address through subsidies and tariffs, but rebuilding that capacity takes years, not months. Grid capacity is a related constraint that gets ignored in most discussions. Widespread EV adoption increases electricity demand substantially. A fleet of one million EVs charging simultaneously could add hundreds of megawatts of load to a local grid. Utilities are planning for this, but the infrastructure upgrades — transformer replacements, distribution line improvements, substation expansions — are slow and expensive. Smart charging and time-of-use rates are being implemented to flatten demand peaks, but adoption is inconsistent and depends heavily on local utility programs. For people working in the industry, the skills gap is real and growing. Traditional automotive engineers know engines, transmissions, and exhaust systems. EV engineering requires expertise in high-voltage systems, battery management, power electronics, and thermal management. Many manufacturers are hiring from aerospace and consumer electronics because the talent pool in automotive specifically is too small. This is creating wage inflation in certain specializations and putting pressure on project timelines.
Where The Industry Actually Stands And Where It Isn't Going
Electric vehicles will continue to gain market share, but the timeline is slower and messier than the headlines suggest. The technology works well for a significant portion of drivers, but it doesn't work equally well for everyone. The infrastructure is adequate in urban and suburban areas with home charging access and poor to inadequate everywhere else. The economics are favorable when you factor in total cost of ownership but unfavorable at the point of sale for most consumers without subsidies. Battery recycling infrastructure is in its infancy despite being essential for long-term sustainability. Some segments of the market will resist electrification longer than others. Heavy-duty trucking, aviation, and marine applications face physical limitations that make batteries impractical with current chemistry. These sectors will likely see hydrogen fuel cells or advanced synthetic fuels play a role, though those technologies face their own challenges. The passenger car market is where electrification will achieve critical mass, and that transition is mostly a question of battery cost decline and charging infrastructure expansion rather than fundamental technological breakthroughs. If you're evaluating this from an investment or career perspective, the areas with the most durable opportunity are battery manufacturing, charging infrastructure, and software-defined vehicle platforms. The areas with the most uncertainty are raw material supply chains, which are subject to geopolitical disruption, and the long-term viability of current business models for dealerships and service centers that relied on ICE maintenance revenue. The companies that figure out how to adapt those models will survive. The ones that don't will face significant pressure within the next five to seven years.