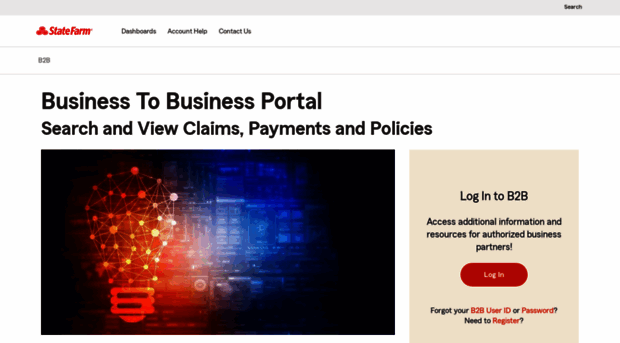
Understanding What Changed With State Farm's B2B Portal Shift
I've been watching the commercial insurance side of this space for a long time. State Farm's move into a proper B2B portal wasn't a sudden invention. It was more like a slow realization that agents and brokers needed a single place to quote, bind, manage, and service policies without bouncing between three different systems. The old process involved logging into one tool for quoting, another for forms, and a completely separate system for endorsements and claims tracking. That fragmented setup was eating agent time and causing errors. The portal consolidated most of that into one interface. Here's what I found when I actually started using it with a mid-sized client portfolio. The quoting engine runs on proprietary State Farm models that pull from their historical loss data and industry benchmarks. When you enter a business type, location, revenue, and desired coverage limits, the system generates a quote in something like 30 to 90 seconds depending on complexity. That's not a small savings. A manual quote used to take 45 minutes or more for a standard commercial package policy.
The Evolution Of B2B Portal State Farm Revolutionizing Business Insurance With Innovative Solutions
The real innovation here isn't just speed. It's the way the portal connects quoting to binding to ongoing policy management under one roof. When a client accepts a quote online, the binding process happens immediately rather than waiting for a back-office team to process paperwork. Endorsements can be added by the agent without calling a central service desk. Claims can be initiated directly from the policy record. This reduces the total turnaround time on most transactions from days to hours. One thing most people miss about the portal is that it doesn't work equally well across every line of business. Commercial auto and general liability quote smoothly through the interface. Workers compensation gets a bit more friction because the experience modification rate calculations have to happen separately and sometimes stall the quote generation. I've seen quotes hang for up to five minutes while the system pulls E-mod data. There's no way to speed that up other than entering the E-mod manually when the system allows it. Another counter-intuitive detail: the portal's pricing algorithms tend to come in slightly higher than a broker who negotiates directly with a State Farm underwriter for large accounts. If you're placing a policy with annual premiums above $50,000, the portal quote might be 8 to 15 percent above what a custom underwritten deal would cost. The portal is optimized for speed and standardization, not for risk-selective pricing on complex accounts. For those situations, I still pull the quote through the portal first as a baseline, then work with an underwriter to get adjusted terms. The portal never gives you a true comparison unless you run both numbers side by side.
I ran into a specific edge-case last year that the documentation doesn't really cover. A client operated multiple business units under one LLC but with completely different NAICS codes. The portal would only assign a single industry code to the entire policy, which threw off the premium calculation by roughly 22 percent. The workaround was to create separate policies for each distinct business unit within the same LLC and reference the parent entity on each form. It's not elegant, but it produces accurate pricing and avoids audit surprises later. The portal also handles document storage and retrieval, which matters more than you'd think. Agents can upload certificates of insurance, loss runs, and property inspections directly to the policy file. Clients can access some of that information themselves through a separate login. This cuts down on the email chains that used to dominate our week. Instead of chasing down a PDF of a certificate from a three-year-old policy, the agent pulls it up in five seconds. There are real limitations worth acknowledging. The portal interface is not particularly intuitive. Navigation requires multiple clicks to reach basic functions, and the search feature across policies is weak. If you need to find a specific policy by client name and you have thousands in your book, the search bar returns too many results and you end up filtering manually. The mobile experience is even worse. I've tried using it on a tablet during site visits and it loads slowly and drops sessions frequently.
Get the Full Details
Data export is another pain point. The portal doesn't offer clean CSV or Excel exports for bulk policy data. If you need to run a portfolio analysis or prepare reporting for compliance purposes, you either have to enter a manual spreadsheet line by line or use the limited reporting module that gives you only pre-set templates. There's no API access for partners unless you're a large carrier or wholesale broker with a dedicated integration agreement. Training on the system is mostly self-directed. State Farm provides webinars and written guides, but the depth varies. Experienced agents pick it up in a few weeks. Someone coming from a completely different carrier's ecosystem might take two to three months to feel comfortable. The biggest time sink during learning is figuring out where specific functions live. The menu structure isn't consistent between different modules. For smaller agencies with fewer than five full-time producers, the portal pays for itself quickly because it eliminates the need for separate quoting software and reduces back-office support. For larger operations, the lack of customization and limited integration options becomes a bigger problem. Some firms layer a third-party practice management tool on top of the portal to handle scheduling, commission tracking, and client communication. That adds cost but fills gaps the portal doesn't address.
The underwriting guidelines behind the portal are strict. Policies that fall outside standard risk parameters get flagged and sent to a manual review queue. This protects against adverse selection but it also means straightforward cases that have a minor deviation can get delayed. I've had commercial property policies held up for two to four business days because of a single unusual construction detail. The system flags it automatically and there's no shortcut around the review. From a technology standpoint, the portal uses modern infrastructure on the backend but the frontend feels like it was built in phases rather than as a unified project. Different sections were likely developed at different times by different teams, which explains the inconsistent user experience between quoting and policy servicing modules. This kind of piecemeal architecture is common in large insurance companies that acquire or build capabilities over decades. If you're considering whether to adopt this portal for your practice, the answer depends heavily on your book composition. Standard commercial lines, small employer policies, and routine renewals benefit the most. Complex professional liability, large captives, and specialty products see less advantage. For those, you'll still need traditional underwriting relationships regardless of what portal tools are available.
The cost structure for accessing the portal is typically bundled into your agent appointment and production agreements. There's no separate subscription fee that I'm aware of, but your production volume matters. Low-producing agents may not get full access or may face restrictions on which lines of business they can quote online. State Farm controls access based on performance tiers and trust levels built over time. What's interesting about this whole shift is that it reflects a broader industry trend toward digitizing B2B insurance distribution. Other carriers are doing similar things, but State Farm's scale gives them an advantage in data accuracy and processing speed. Their historical loss experience across millions of policies feeds directly into the portal's pricing models, which smaller carriers simply can't match with their narrower datasets. The customer experience angle also matters. Business owners today expect the same level of digital convenience from their insurance provider that they get from other business services. A portal that allows them to view policies, request changes, and track claims without calling an agent is becoming a standard expectation rather than a nice-to-have feature. State Farm is positioning itself to meet that expectation directly rather than relying on independent agents to fill the gap.

My recommendation if you're going to use this system is to start with a small test group of clients. Run a handful of quotes and policy changes through the portal alongside your existing manual processes. Track the time differences, error rates, and client feedback. After about sixty days, you'll have a clear picture of whether the portal saves time for your specific operation or just adds another step you didn't need before. The answer varies enough by agency that a trial period is worth the effort.