How Currency Rates Actually Work When You Move Money
When you go to convert money, the rate you see on your bank screen is rarely the same one that shows up on CNN or Reuters. This is because every institution builds its own margin into the price they hand you. Banks typically charge between 2% and 5% above the mid-market rate. Credit card networks like Visa and Mastercard sit closer to 0% with their own small foreign transaction markup layered on top. I have sat across from accountants who have no idea why a wire transfer of 900 Euros to Dollars came out twenty dollars short of what the overnight spot rate suggested, and half the time it was just a weekend spread widening.The Everchanging Face Of Currency Conversion 900 Euros To Dollars
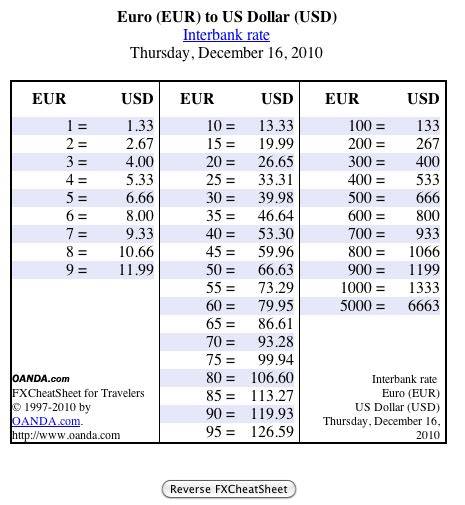
The core of converting 900 Euros into US Dollars is straightforward math, but the execution is where people get hit with unexpected fees. Take your amount, divide by the EUR/USD rate, and multiply by the USD. Right now, if the rate sits around 1.08, that gives you roughly 833 dollars. But nobody gets 833 dollars unless they are checking interbank rates on a Bloomberg terminal at 3 AM, which is not realistic for anyone doing this outside a hedge fund. The actual cash-in-hand number will be somewhere between 810 and 820 depending on where you make the trade.The mid-market rate is the textbook figure you see on Google. It is the rate at which large banks trade with each other overnight. It is completely meaningless for retail customers, but it serves as the baseline that every fee structure references. Your bank is not charging you the mid-market rate. They are quoting you a rate slightly below it, which means you receive fewer dollars than the math suggests. The difference is their profit, disguised as a "favorable rate." I ran into this exact problem last year when a client needed to move 900 Euros to a US-based contractor. She checked the rate onXE.com and saw she should get about 972 dollars. Instead, her bank credited 941 dollars after the conversion. The spread alone cost her thirty-one dollars, and that was on a premium checking account with no stated foreign transaction fee. I had her resend the money through a Wise account instead, which used the real mid-market rate and charged a flat fee of about two dollars. She ended up with roughly 967 dollars, which is a difference worth noting on a small amount like this.
Where You Convert Matters More Than the Rate Itself
Different channels offer dramatically different outcomes. A physical bank branch is the worst option by far. You will walk out with a rate that is four to six percent below mid-market. Online-only services like Wise, Revolut, or OFX come much closer to the real rate because they use interbank liquidity pools and layer their fees as transparent commissions instead of hidden spreads. Credit cards are fine for spending, but they are terrible for cash conversion because they add another markup on top of the network rate.Wire transfers via SWIFT introduce yet another variable. Each intermediary bank along the route takes a cut, usually between fifteen and thirty dollars per hop. This is called a "correspondent banking fee," and it applies even when both the sender and receiver are in developed economies. For a 900 Euro conversion, the fees can eat five to eight percent of your total if you route it through a small regional bank with poor correspondent relationships.
Timing and Market Conditions
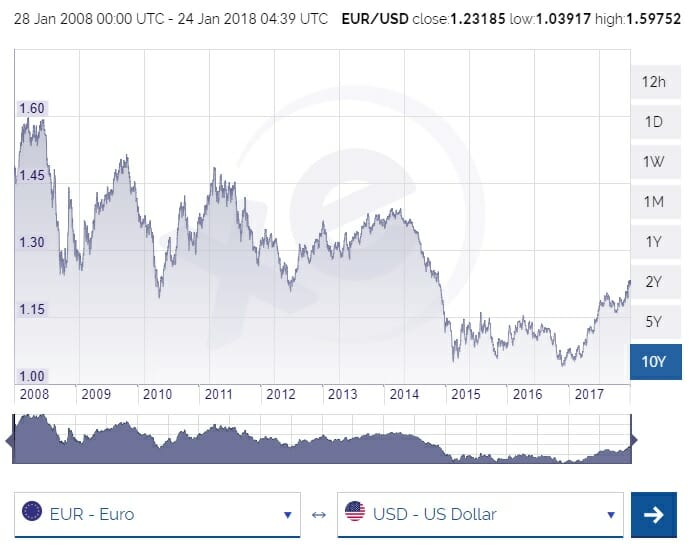
Currency rates move constantly. They respond to interest rate decisions, inflation data, geopolitical news, and even quiet shifts in central bank balance sheets. The EUR/USD pair is one of the most liquid in the world, which means the spread stays tighter than most pairs, but it is never truly stable. A single FOMC meeting statement can move the rate by a hundred pips in thirty seconds, which is about one percent of the pair's value.If you are making a one-time conversion of 900 Euros, timing matters less than most people think because the absolute dollar difference is small. But if you plan to do this repeatedly, locking in a forward contract through a broker like OFX or Airwallex can protect you from adverse moves for up to a year. These contracts let you set the rate today for a future exchange, which removes the guessing game entirely. The downside is that you commit to the trade even if the rate moves in your favor later.
Get the Full Details
Common Mistakes People Make
Many people check the live rate on their phone and assume that is the rate they will actually receive. This assumption is wrong almost every time. The quoted rate at the point of sale includes the institution's spread. Another frequent error is ignoring the total cost, focusing only on the fee and forgetting about the rate markup. A zero-fee transfer can still be expensive if the spread is wide. I always calculate the final USD amount my clients receive and work backward to find the effective rate they were given. This reveals the true cost every time.Some older banking apps still display the rate in the wrong direction, showing USD per EUR instead of EUR per USD, which confuses users into calculating the inverse. This is rare now, but it still happens with legacy platforms at regional credit unions. Always double-check which convention is being used before confirming a transfer.
When Standard Conversion Fails You
Not every situation is handled well by online converters or traditional banks. If you need to move 900 Euros to an account in a country with capital controls, such as Nigeria, Turkey, or Argentina, most standard services will simply decline the transaction. In those cases, peer-to-peer platforms or local exchange houses become the only viable option, though they carry higher risk and wider spreads. Similarly, conversions involving currency pairs like EUR/TRY or EUR/ARS are not available on most retail platforms and require specialized brokers.There is also the issue of minimum transfer amounts. Some services charge a flat fee regardless of size, which makes small conversions disproportionately expensive. Transferring three hundred Euros might cost the same ten-dollar fee as transferring three thousand, which means the percentage hit changes from three percent down to one third. For larger amounts, fixed-fee models are clearly better. For smaller ones, they are brutal.
What You Should Actually Do
Before initiating any conversion, check the mid-market rate on a neutral site likeXE.com or OANDA. Then compare what your chosen provider is actually quoting. Calculate the difference and see if it falls within normal margins, which for reputable online services is usually between zero point five and one percent. If the gap is larger, look for another provider. Keep a running tab of the effective rate you received on previous conversions so you have a baseline for comparison.I keep a simple spreadsheet tracking the EUR/USD rate I received on every transfer I have made over the past five years. It is not perfect, but it shows whether a provider is consistently worse than the market average. Over time, this data makes it obvious which companies are squeezing their customers and which are competing on price. The spreadsheet has saved me thousands of dollars in avoided bad conversions.