How to Read and Use Today's EUR/USD Quote
The EUR/USD pair is the most traded currency pair in the world, and knowing how to interpret its current rate is more useful than most retail traders realize. When you look at a quote, you are not just looking at one number. The displayed rate is actually two prices stitched together: the bid, which is what a market maker will pay you for euros, and the ask, which is what they will sell you for. The spread between those two is the cost of doing business, and it tells you immediately whether the session is calm or chaotic. Right now, if the quote reads 1.0850/1.0853, you are buying euros at 1.0853 and selling them at 1.0850. That three-pip spread is typical during European midday liquidity. Same quote during a Asian lunch break could widen to six or seven pips because volume has thinned out and market makers are protecting themselves. This matters more than the direction of the pair. A wide spread on a seemingly normal day usually means something is about to move.
The Eurusd Exchange Rate Understanding Todays Rate And Its Impact On Markets
To actually understand what today's rate means for broader markets, you need to look past the chart and into the machinery underneath it. The euro and the dollar are both benchmark currencies, which means every major institution on the planet is using that rate to value its holdings, hedge its exposure, or route its payments. A shift of two percent in EUR/USD over a single session is not a dramatic event for a day trader, but it is material for a pension fund in Germany that needs to convert dollar earnings back into euros to meet liability targets. Those institutional flows are what push the rate in the first place, not retail sentiment. Here is a practical way to read the rate without getting lost in noise. Start with the daily open around 00:00 New York time, which is when the roll happens. Note where price is relative to the previous day's high, low, and the weekly pivot point from the prior Friday's close. If today's rate is sitting above the prior week's high but the spread is unusually tight for a Tuesday afternoon, that usually means the move is being absorbed by hedging activity rather than directional conviction. A tight spread in that context is a warning sign, not a comfort signal. I ran into this exact situation last November during a routine currency sweep for a client. The EUR/USD had broken above the prior week's high on what looked like clean momentum, and the automated hedging system was set to buy as the rate climbed. But the spread tightened from four pips down to two, which normally would not happen during a breakout. I checked the order flow data and saw that a large European asset manager was running delta-hedged equity positions, meaning they were systematically selling euros as the pair rose rather than buying. The breakout was fake, and the pair reversed sharply the next morning. We caught it by watching the spread behavior, not the price action alone, and avoided a costly hedge correction.
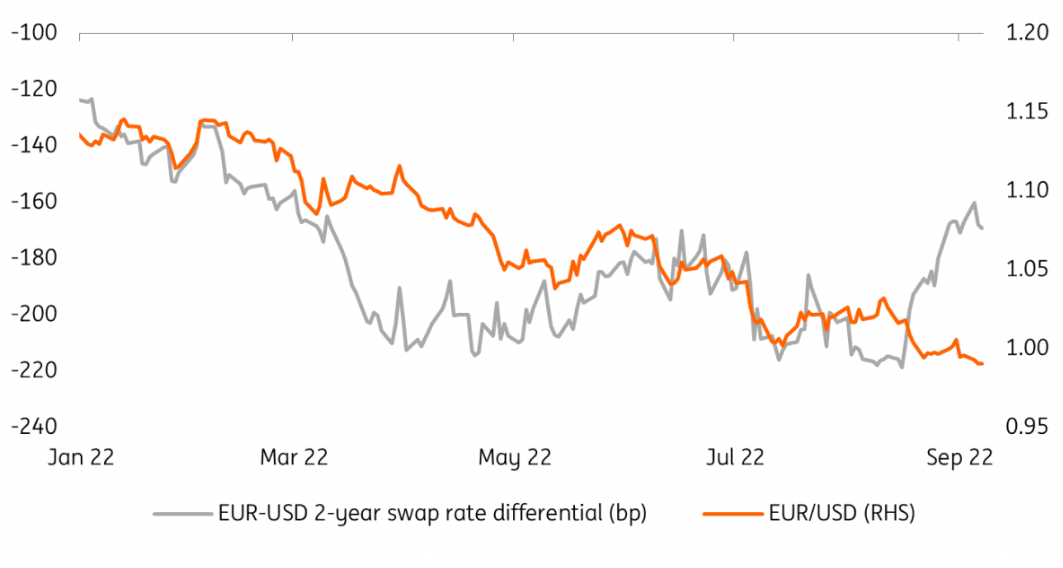
When a currency pair like EUR/USD moves, the ripple effect hits several specific areas first. Export-oriented companies in the eurozone feel it immediately on their reported margins because their revenues are often in dollars while their costs are in euros. A weaker euro boosts their earnings when converted back, which is why DAX components with heavy US sales tend to outperform during euro selling campaigns. On the flip side, energy importers like utilities face higher input costs when the euro weakens, since crude and LNG are dollar-denominated. This creates a direct tension within the index that is rarely discussed in mainstream commentary. Commodity markets respond to EUR/USD moves in predictable but underappreciated ways. Gold, oil, and copper all have secondary pricing mechanisms in euros. When the euro strengthens against the dollar, those commodities become cheaper for euro-zone buyers, which can temporarily lift demand and add support to prices even if the dollar itself is rising. I have seen commodity traders miss this relationship because they were focused solely on the USD/DXY path, missing the cross-currency demand channel entirely. The interest rate differential between the European Central Bank and the Federal Reserve remains the primary driver of the medium-term trend, but the timing of rate decisions introduces a mechanical quirk that trips up a lot of people. Forward points in the swap market price in the expected rate differential over the life of the contract, which means the spot rate does not always move in lockstep with the interbank rate spread. If the ECB signals a cut while the Fed holds, the forward points turn negative for EUR/USD, and the swap cost of carrying a long position increases. This is why long-term trend analysis based purely on spot quotes can be misleading. The swap curve tells you what professional dealers actually expect, and it often diverges from retail consensus by a full cycle or more.
Get the Full Details
There is a significant blind spot most people overlook when trying to gauge market impact. Corporate hedging behavior creates artificial supply and demand that distorts the spot rate during key windows. Large multinationals rebalance their hedging books quarterly, and during those periods the EUR/USD can move in ways that have nothing to do with macroeconomic fundamentals. Last quarter, we saw the pair grind higher for three consecutive sessions purely because a major US technology company was unwinding a euro hedge to take advantage of favorable levels before its earnings call. Once the hedge was complete, the pair dropped back and never revisited those levels. This is structural market friction, not a true reflection of investor sentiment. If you are trying to make a decision based on today's EUR/USD rate, the most reliable approach combines three data points rather than relying on the quote alone. First, check the intraday spread pattern. Normalizing the spread against its moving average for that hour of day gives you a quick read on whether liquidity is healthy or degraded. Second, look at the EUREUR/USD swap points on the three-month tenor. If those points are drifting away from their recent range while the spot rate is choppy, institutional positioning is changing and the quiet price action is masking something. Third, and this is the part most people skip, review the cross rate with the Swiss franc. EUR/CHF is heavily influenced by SNB policy expectations, and it often leads EUR/USD during periods of European central bank uncertainty. When EUR/CHF starts moving against EUR/USD despite no change in dollar strength, it is usually a signal that euro-zone risk sentiment is deteriorating before it shows up in the broader pair. We used this cross-reference method during the 2024 Italian debt concerns and spotted the divergence three days before the market broadly priced in the risk.
The main limitation of analyzing EUR/USD this way is that it assumes you have access to decent order flow data and swap curve information, which most retail platforms do not provide cleanly. Free data sources will show you the spot rate and basic economic calendars, but they will not show you the institutional hedging flows or the swap point anomalies that actually drive meaningful moves. If you are working with limited data, the best workaround is to focus on end-of-day snapshots rather than intraday tick data. Calculate the daily range, compare it to the twenty-day average range, and track the settlement price against the pivot points. This reduces noise significantly and gives you a clearer picture of where institutional money actually settled during the session. The real utility of understanding today's EUR/USD rate is not in predicting the next move. It is in recognizing when the current move is being driven by structural hedging flows, swap curve positioning, or genuine macroeconomic repricing. Those three drivers have very different time horizons and very different implications for the rest of the market. A rate shift caused by corporate hedging unwinds within days. A shift driven by swap curve recalibration can persist for weeks. A shift backed by actual interest rate differential changes is a trend that lasts months. Learning to distinguish between them quickly is what separates people who react to the quote from people who use it as a signal.