Working With The Eur/Usd Pair On A Daily Basis
The eur/usd pair is the most liquid currency cross in global markets, which means you will rarely have trouble finding a rate. But the rate you see on google is not the rate you get. I spent years working treasury operations for a mid-size European exporter, and the first time someone told me our bank was quoting us a spread that added up to nearly forty euros a day on a single transaction, I just sat there staring at the screen. Here is what actually happens when you try to figure out what 33 euros converts to in dollars, and why the number on your screen might be misleading.
The Eurusd Exchange Rate Understanding The Value Of 33 Euros In Dollars
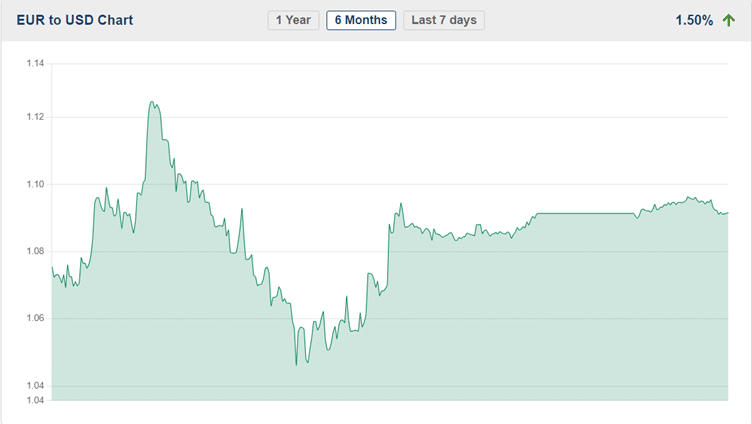
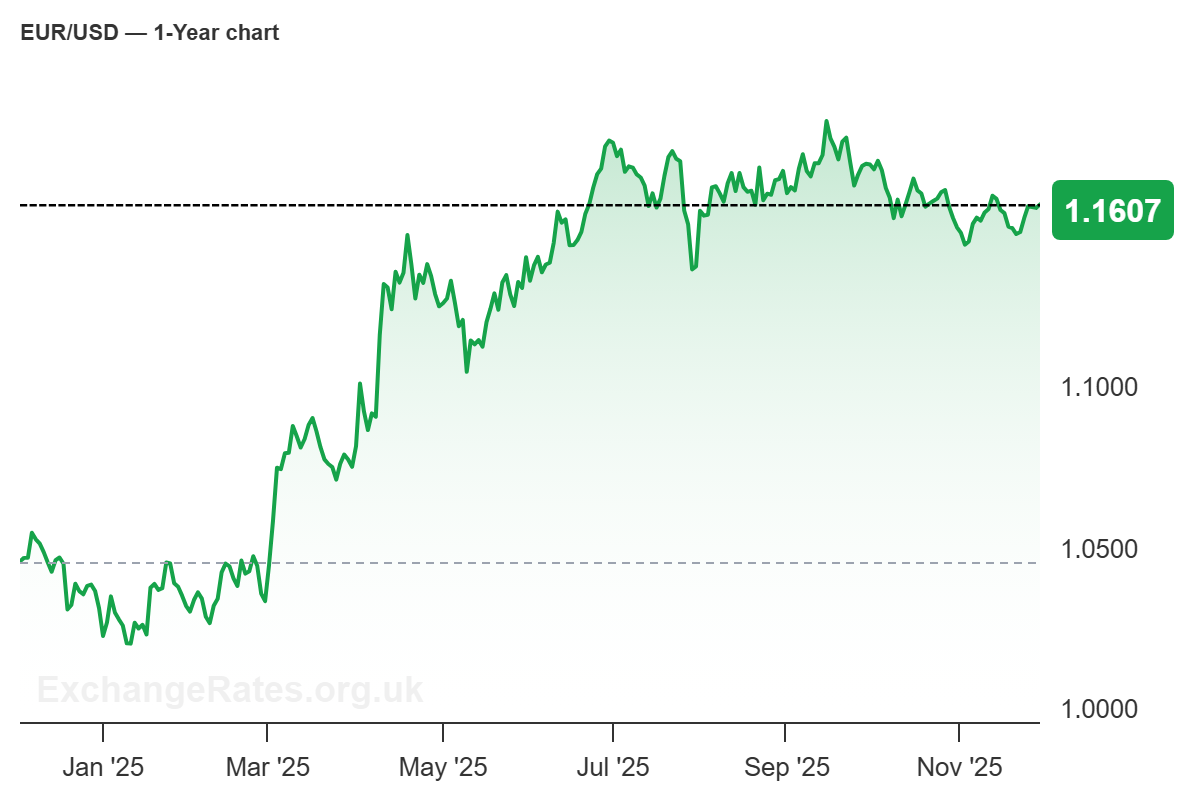
To convert thirty-three euros into US dollars, you multiply 33 by the current EUR/USD exchange rate. If the rate sits at 1.0850, then 33 times 1.0850 equals 35.81 dollars. That is the textbook calculation. Nobody actually gets that number though. When a retail customer walks into a bank or uses a currency app, they are dealing with a bid-ask spread. The bank buys euros from you at one price and sells them at another. The spread on EUR/USD through a typical consumer channel runs between 0.5 and 2 percent, sometimes more if you are using an airport kiosk or a remittance service. A credit card company might apply a foreign transaction fee of 2.7 percent on top of whatever dynamic currency conversion rate they push at the terminal. I learned this the hard way in 2019. A supplier in Germany sent an invoice for exactly 33 euros. I went to my business banking portal, saw the rate posted at 1.0842, and initiated the payment. When the money landed on the supplier side, they complained they received less than expected. It turned out my bank had marked the transaction as a cash advance instead of a wire, pulled the rate at 1.0780 instead of the mid-market rate, and charged a flat $25 processing fee. The difference between what I expected to pay and what actually left my account was about six dollars. I ended up using SWIFT gpi tracing to identify where the rate got modified and got the discrepancy adjusted the next business day. The workaround was straightforward after that: I switched to a dedicated FX platform that locked in the rate at execution rather than allowing slippage, and I stopped assuming the quoted rate was the executed rate.
The key distinction here is between the mid-market rate, which is the midpoint between what buyers and sellers are willing to trade at, and the actual executed rate that any individual institution offers you. Financial markets report the mid-rate continuously throughout the trading day. Retail converters round it. Banks profit from the gap.
Get the Full Details
Why The Spread Matters More Than You Think
On a small amount like thirty-three euros, the spread might look negligible. At a 1.5 percent spread, you are looking at roughly fifty cents in hidden cost. That seems harmless. But when you are reconciling monthly invoices or running a budget, those fifty-cent discrepancies accumulate across dozens of transactions and quietly erode margins. Large institutional players access interbank rates with spreads measured in fractions of a pip. A pip on EUR/USD is 0.0001. The interbank spread can sit at 0.1 to 0.3 pips during normal liquidity. Retail consumers are often pricing in spreads of 50 to 200 pips without realizing it. That is a difference of three to four orders of magnitude. If you need to convert thirty-three euros regularly, the practical move is to use a regulated FX broker or a multi-currency account like Wise or Revolut, where the spread typically runs 0.3 to 0.8 percent. These services display the mid-market rate prominently and charge a transparent fee. You will still pay more than the interbank rate, but significantly less than a traditional bank or airport exchange booth, which can hit 5 percent or higher on small denominations.
The Timing Problem Nobody Talks About
EUR/USD moves throughout the day. The pair is most active during the overlap of the London and New York sessions, roughly 8 AM to 12 PM Eastern Time. During that window, spreads tighten and prices are efficient. Outside those hours, especially during Asian trading or around holidays, the spread widens and you can get filled at a worse rate even if the headline number looks similar. I once had a client who needed to pay a Polish vendor 33 euros on a Friday afternoon. The rate looked fine at 1.0910. The trade didn't settle until Tuesday because the SWIFT network was slow over the weekend. By Tuesday, the rate had dropped to 1.0820 because of a sudden euro sell-off following ECB commentary. The client lost about three dollars on timing alone. Setting a limit order or scheduling the payment in advance on a platform that supports rate alerts prevents that kind of exposure.
What You Should Actually Check Before Converting
Before you convert anything, look at the total cost, not just the headline rate. Add up the spread, any flat fees, and any hidden markup. A rate of 1.0850 with a 3 dollar fee is worse than a rate of 1.0820 with no fee if you are converting a small amount. Do the math on the final dollar output, not the percentage input. Also verify whether the quote is a guaranteed rate or a floating one. Some apps show you 1.0842 but reserve the right to adjust it before execution. Guaranteed rate locks, usually available through brokers for a small premium, eliminate that risk entirely. For a one-time conversion of thirty-three euros, the premium might not be worth it. For recurring conversions, it saves headaches. The bottom line is that thirty-three euros converts to roughly thirty-five to thirty-six dollars at current market rates, but the exact amount you receive depends entirely on which channel you use, when you execute the trade, and whether you understand how the spread works. Most people overpay without noticing because the difference is small enough to ignore on a single transaction but large enough to matter when you add them up over a year.