What Bonds Actually Are, Without the Textbook Fluff
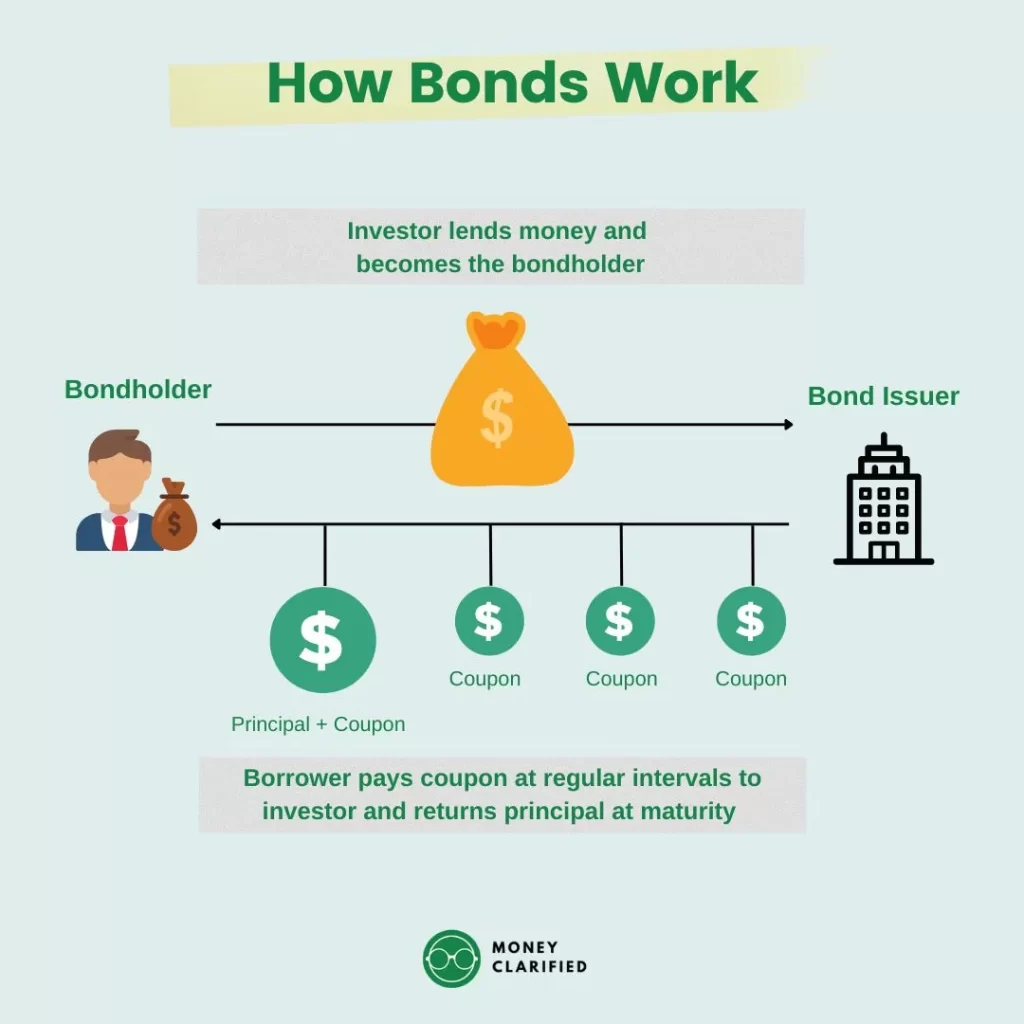
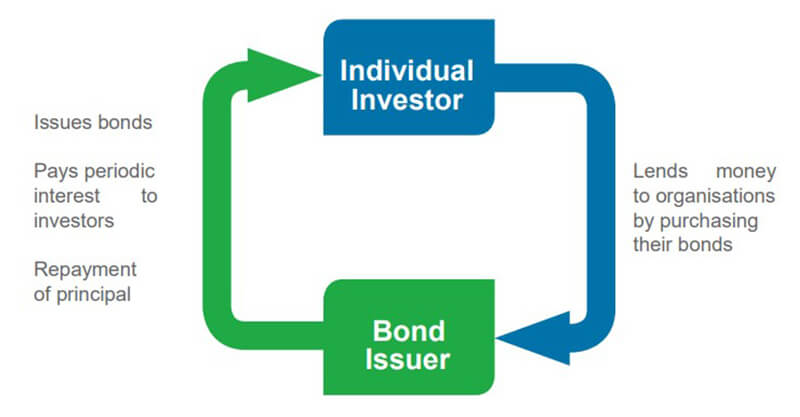
A bond is a loan. You lend money to an entity—government, municipality, corporation—and they pay you back with interest on a set schedule. That's the entire structure. The complications come from how that simple mechanic behaves when rates change, when credit quality shifts, and when you're actually trying to make money rather than just understand the definition. I've spent years watching retail investors treat bonds like they're inherently safe because "they're fixed income." That assumption costs people real money. I learned it the hard way during the March 2020 selloff when even investment-grade corporate bonds dropped 15-20% in a matter of days. Liquidity vanished. Bid-ask spreads widened to obscene levels. If you needed to sell, you sold at a loss regardless of what the textbook says about bonds being stable.
The Essential Guide To Financial Bonds Meaning How Bonds Work As A Core Investment Tool
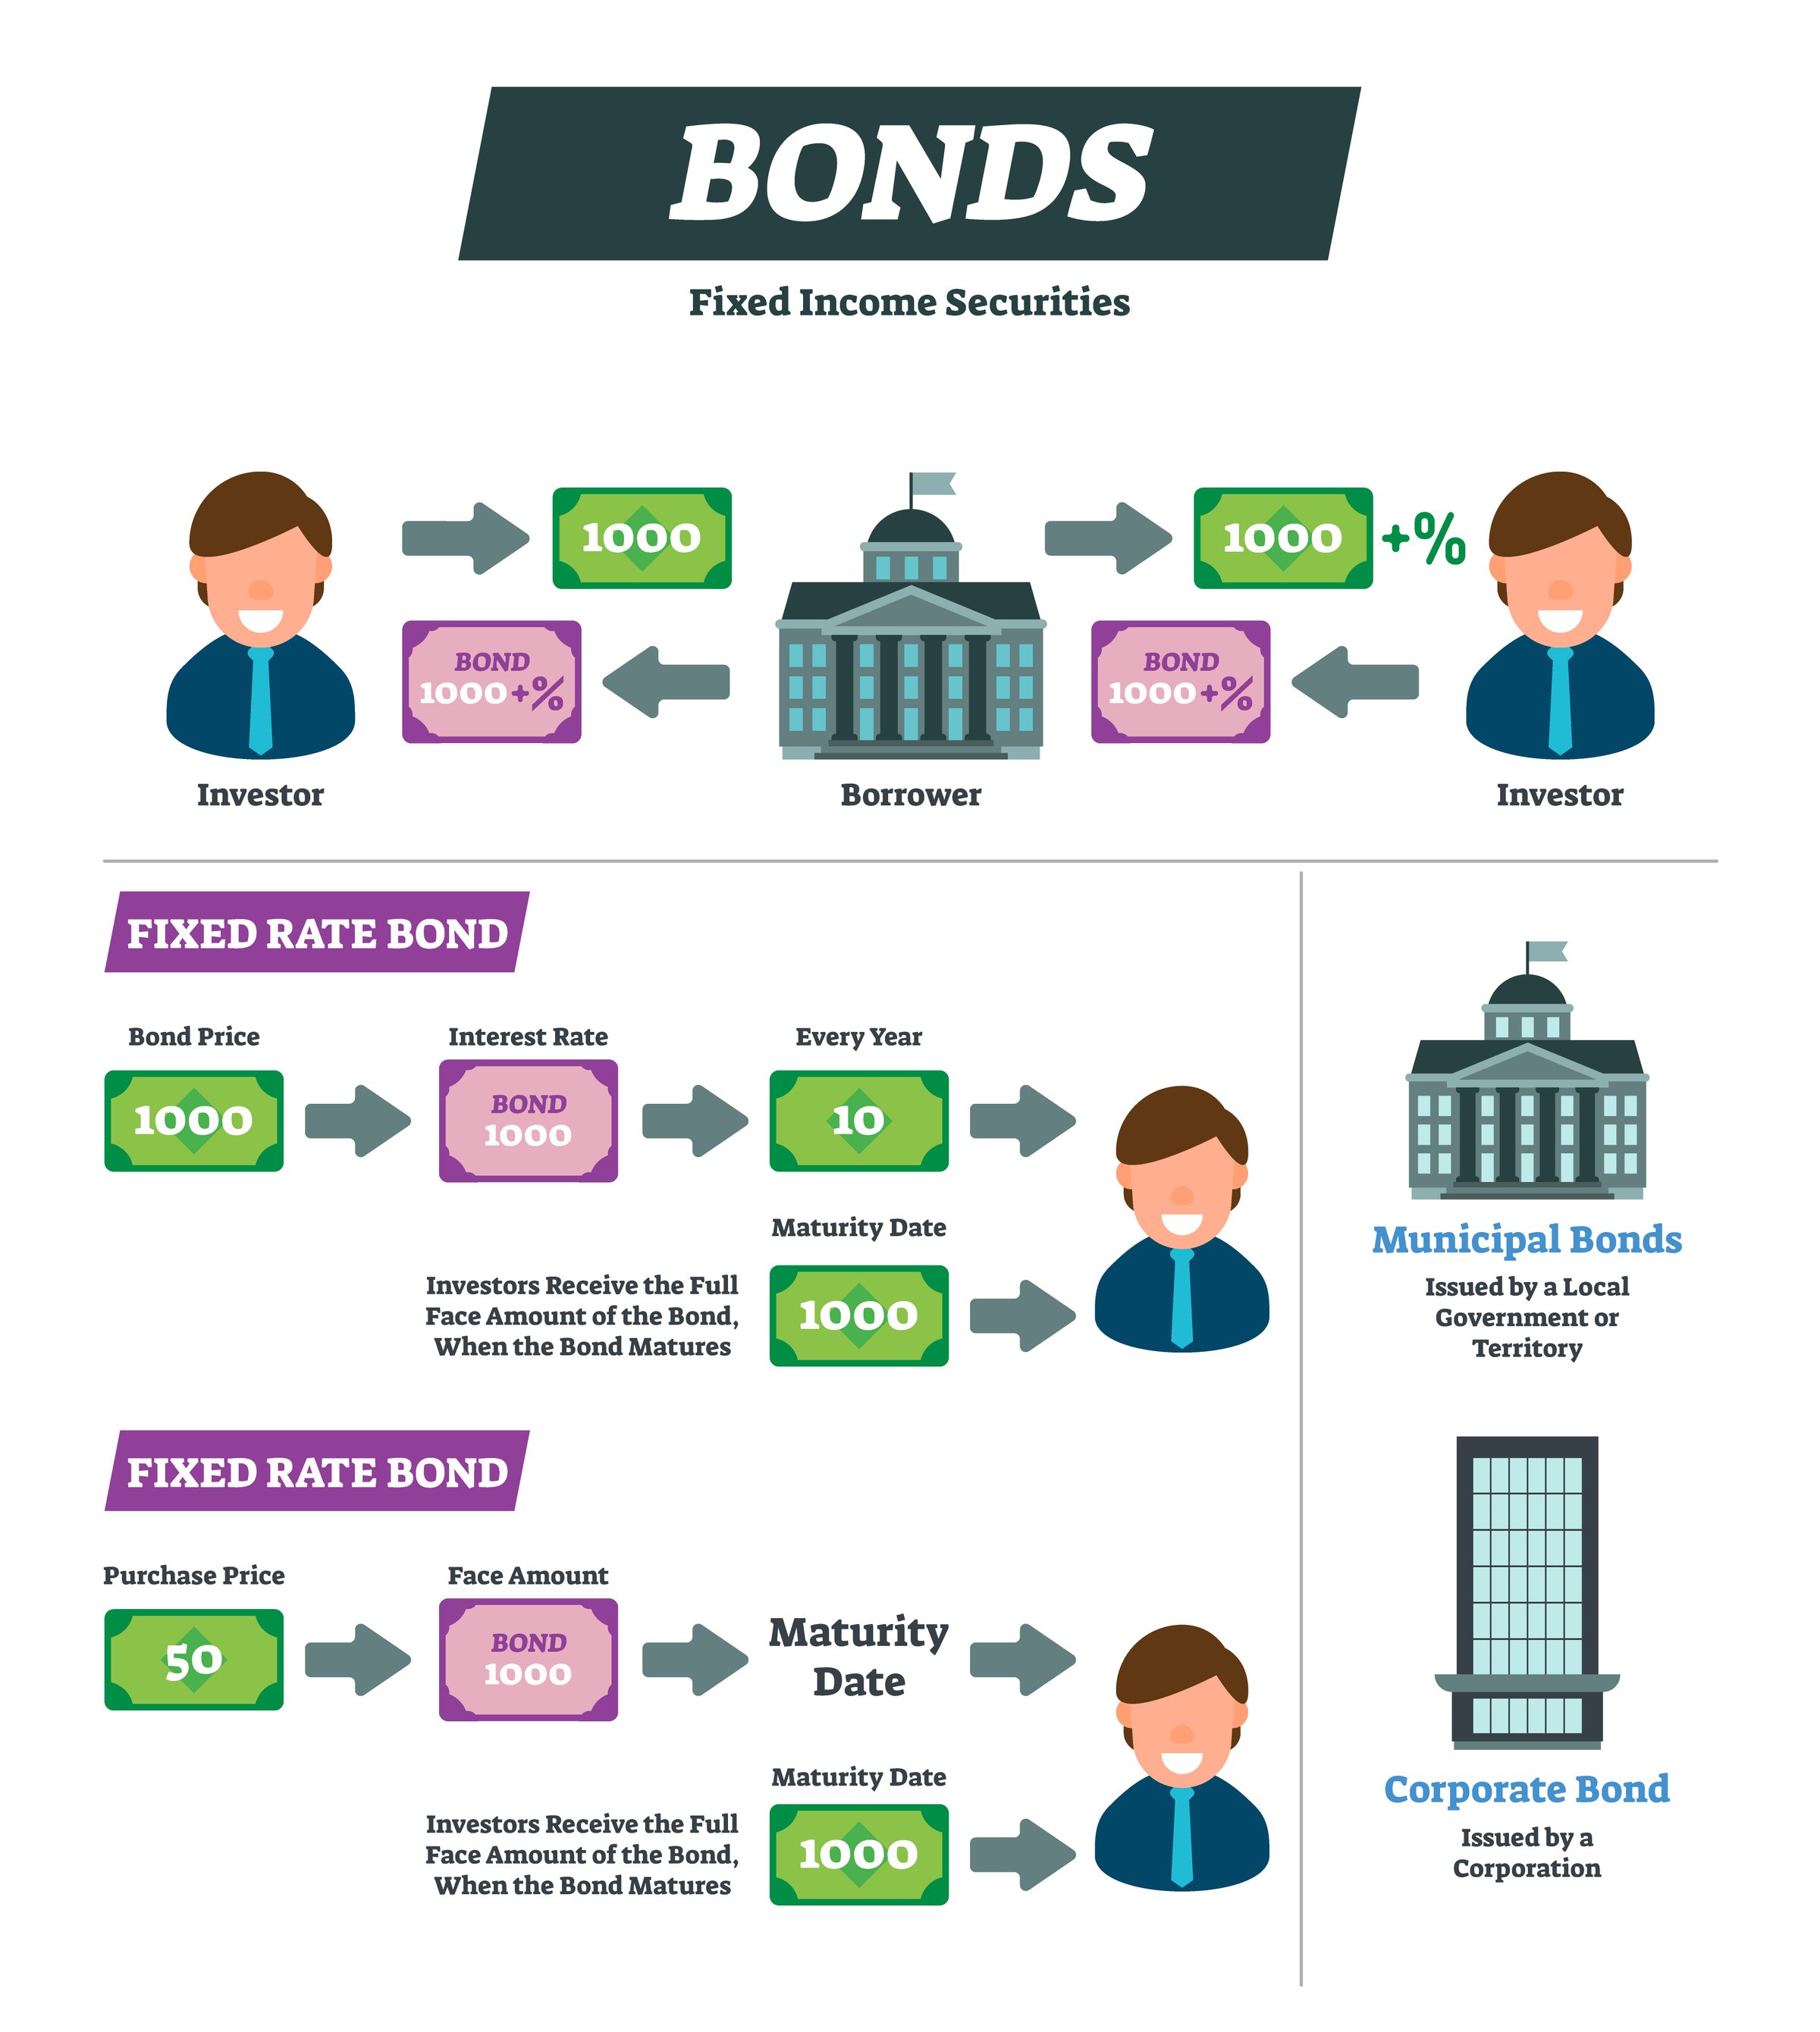
Before we get into the mechanics, here's the core concept everyone misses: bond prices move inversely to interest rates, and the magnitude of that movement depends on duration. Duration isn't just a number in a spreadsheet. It's a measure of how sensitive your bond's price is to rate changes. A bond with a duration of 5 years will lose roughly 5% of its value if rates rise by 1%. Gain roughly 5% if rates fall by 1%. That's it. Simple arithmetic. Brutal in practice. Here's how the actual pieces fit together. When a bond is issued, it has a face value—usually $1,000 per bond—and a coupon rate. If you buy a 10-year Treasury note with a 4% coupon, you receive $40 annually until maturity, when you get your $1,000 back. Easy. But you rarely buy bonds at issuance anymore. Most trading happens on the secondary market, where prices fluctuate based on prevailing rates. When rates go up, existing bonds with lower coupons become less attractive. Their prices drop. When rates go down, older bonds with higher coupons become valuable, and their prices rise. This is the fundamental price mechanism. Everything else—yield curves, credit spreads, convexity—is a refinement of this basic relationship.
The yield to maturity is what most people actually care about. It's the total return you'd receive if you held the bond until it matures, accounting for the purchase price, the coupon payments, and the face value at redemption. If you buy a bond at a discount—say $950 for a $1,000 bond paying 4%—your yield to maturity is higher than 4% because you're also capturing the $50 gain at maturity. If you buy at a premium—$1,050—you're actually getting a lower effective yield than the coupon rate suggests. Credit quality determines risk. Government bonds, particularly US Treasuries, are considered risk-free on the default side. Municipal bonds vary by issuer. Corporate bonds range from investment grade (BBB- and above) to high yield or "junk" (BB and below). The spread between a corporate bond yield and a Treasury yield of the same maturity is called the credit spread. It compensates you for taking on default risk. When spreads widen, it usually means the market is worried. When they compress, complacency is the default mood. Now for something most beginners don't understand: bond funds behave fundamentally differently from individual bonds. When you buy an individual bond and hold it to maturity, you lock in your yield regardless of what happens to rates. Your principal is returned at par. With a bond fund, there is no maturity date. The fund constantly buys and sells bonds, and its net asset value fluctuates with the market. In a rising rate environment, bond funds lose value indefinitely. They don't recover on their own the way individual bonds do when held to maturity. This distinction matters enormously for retirement accounts and long-term holders.
Get the Full Details

I ran into a specific edge case last year that illustrates why mechanical understanding isn't enough. A client came to me with a portfolio of individual municipal bonds purchased at various times. She wanted to understand her tax-equivalent yields. The standard formula is municipal yield divided by one minus your marginal tax rate. But several of her bonds had original issue discount—which means they were issued below face value and accrue imputed interest over time. The tax treatment of OID is different from regular coupon income. She was effectively underreporting her taxable income on those positions. I had to pull the bond sale confirmations, calculate the accretion schedules, and adjust her projected tax liability. It added roughly eight hours of work but prevented a significant correction come filing season. Another counter-intuitive point: not all bonds are created equal, and "bond" as a category is misleading. Floating rate notes adjust their coupons periodically based on a reference rate like SOFR. Their duration is essentially near zero, which means they're nearly immune to interest rate risk. But they carry reinvestment risk—when rates fall, your coupon falls with them. Conversely, zero-coupon bonds have the highest duration of any bond type because they pay nothing until maturity. A 30-year zero-coupon bond has a duration closer to 30 years, making it extremely volatile in a changing rate environment despite having no periodic payments to confuse the picture. The callable bond is another trap. Many corporate and municipal bonds include a call provision that lets the issuer redeem them before maturity, usually when rates have fallen. You think you're locking in a 5% coupon for 10 years. Rates drop to 3%. The issuer calls your bond. You're forced to reinvest at lower rates. This is called reinvestment risk, and it's asymmetric—you capture the upside of falling rates as price appreciation, but the issuer steals it back through the call. When evaluating callable bonds, always look at the yield to worst, not just yield to maturity. Yield to worst assumes the bond is called at the earliest possible date, giving you the lowest possible return scenario.
TIPS—Treasury Inflation-Protected Securities—are often misunderstood. The principal adjusts with CPI, and your coupon is applied to the adjusted principal. Sounds great. But here's the catch: you pay taxes on the inflation adjustment each year even though you don't receive that money until maturity. This isphantom income, and it's a tax drag in taxable accounts. TIPS work best in tax-advantaged accounts like IRAs where the adjustment doesn't create annual tax liability. In a taxable account, the combination of lower real yields and annual taxation of phantom income often makes nominal Treasuries the better choice depending on your bracket. Convexity is the technical concept that separates people who actually understand bonds from people who memorized a formula. Duration assumes a linear relationship between price and yield. It doesn't exist. The actual relationship is curved. Convexity measures that curvature. For most bonds, positive convexity means that when rates fall, prices rise more than duration predicts, and when rates rise, prices fall less than duration predicts. It's a free lunch of sorts. But some bonds—particularly mortgage-backed securities—have negative convexity. When rates fall, prepayments accelerate, and the bond's duration shortens unexpectedly. When rates rise, prepayments slow, and duration extends. This is exactly backward from what you want, and it's why MBS can behave wildly during rate transitions. Here's what I wish everyone understood about bond portfolio construction: you don't choose bonds based on yield. You choose them based on your liability structure. If you're building a bond ladder for retirement income, you match maturities to your spending needs. If you're managing duration for a pension fund, you align the portfolio's duration with the liability duration to hedge interest rate risk. If you're a retail investor trying to preserve capital, short-term Treasuries or T-bills are often the right answer, even though the yield looks pathetic compared to corporates. The yield chase is where people get burned. A 2% yield on a 3-month T-bill is functionally risk-free. A 6% yield on a 10-year junk bond is compensation for taking on real risk.
Transaction costs are another hidden factor. Individual bonds traded on the secondary market have bid-ask spreads that can be enormous, especially for lower-rated or less liquid issues. A spread of 50 basis points on a $1,000 bond means you're instantly down 0.5% the moment you buy. High-yield bonds can have spreads of 200-400 basis points. This is why bond ETFs and mutual funds exist—they aggregate liquidity and reduce transaction costs. But as I mentioned earlier, the fund structure changes the risk profile entirely. There's no maturity anchor. You're exposed to ongoing market fluctuations. The realistic approach for most people is a layered one. Core holdings in broad Treasury or aggregate bond funds for liquidity and low cost. Satellite positions in individual bonds or sector-specific funds when you have a specific view or need. Keep duration aligned with your time horizon. Don't chase yield without understanding what risk you're actually accepting. And for God's sake, don't assume "bond" means "safe." Bonds are a tool. Like any tool, they can hurt you if you use them wrong. If you want a practical starting point, look at the Barclays Aggregate Bond Index composition as a benchmark. It's roughly 40% government, 28% corporate, 26% asset-backed, and the rest muni and other. From there, decide your duration target based on how long you need the money locked away. Short duration (under 3 years) for emergency funds and near-term goals. Medium duration (3-7 years) for balanced portfolios. Long duration (7+ years) only if you understand the rate risk and have a long time horizon. The yield curve can invert, and when it does, short-term rates exceed long-term rates, punishing duration extension. It happened in 2022 and 2023. People who blindly bought long-duration bonds lost significant capital while waiting for a recovery that took years to materialize.
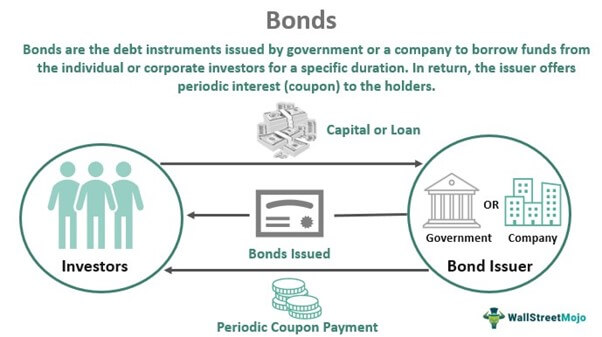
The bottom line: bonds are loans with pricing mechanics that reward understanding and punish complacency. The math is straightforward. The behavior under stress is not. Pay attention to duration, credit quality, call features, and tax implications. Keep expectations proportional to the risk you're taking. And remember that the quiet period is when bond losses accumulate—invisibly, slowly, until something breaks and you realize you've been holding something far riskier than you thought.