What a Deposit Slip Actually Is
A deposit slip is a small bank form used when you hand cash or checks to a teller. It lists the amounts you're putting into your account and asks the bank to credit that total to you. That's basically it. Most people haven't filled one out since the early 2010s, which is why so many feel lost when asked to use one at the branch. These days banks call them deposit tickets or deposit vouchers interchangeably. The form structure stays roughly the same across institutions, though the layout shifts a bit. Some banks pre-print your account number on them. Some don't. Both work fine.
Where to Get One and How to Fill It Out
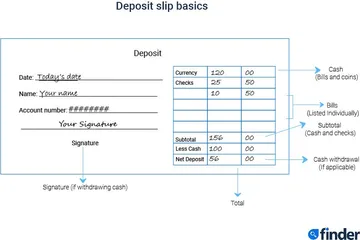
You pick up a blank deposit slip at the branch or download it from your bank's website. If you bank online regularly, The Essential Guide To Deposit Slips What You Need To Know includes finding your bank's forms page, which usually lives under the banking or services section of the site. Search for "deposit ticket" or "cash deposit slip" and you will find a PDF ready to print. Here is the actual process. Write the date. Print your full name exactly as it appears on the account. Write your account number below it. If the slip has a separate line for routing number, fill that in too—some slips don't have that field and that's normal. List each check separately with its issuer name and dollar amount, then add up the subtotal. Enter your cash total on the cash line if you have any. Write the total in the large box at the bottom, both numerically and in words if there's a field for it. Sign the slip where required. I have seen people skip the signature line on a slip and the teller just re-wrote it at the counter anyway. A missing signature doesn't invalidate the deposit but it does slow things down because the teller has to verify your identity through another method. I filed a corrected slip once and the whole thing took forty extra seconds. Not terrible, but annoying when the line is long.
The Essential Guide To Deposit Slips What You Need To Know
This section covers the parts beginners consistently mess up. It is not a comprehensive list of every field on every possible deposit slip from every possible bank. It is the stuff that trips people up in practice. The first problem is writing the total in the small box versus the large total box. The small box near the top usually shows your individual line totals. The large box at the bottom is what actually gets posted. I have watched a teller point to the wrong box on two separate occasions, which is embarrassing for everyone involved. Always double check the final figure matches between your mental math and the slip before handing it over. Another common mistake involves mixing up "credit to checking" and "credit to savings" on dual-account slips. When the slip has two destination boxes, put the right amount in each box. Do not assume the teller will split it evenly or ask you. They usually will not. Just write the correct amount in each.
Get the Full Details

If you are depositing checks from multiple payers, list them one per line. Do not group them into a single entry like "checks totaling $542." The bank's deposit imaging system reads each line individually. Grouped entries confuse the automated clearing house process and can trigger a hold or require manual review. One time I combined three checks into one line because I was in a hurry. The branch held $318 of it for two business days instead of processing the rest immediately. It would have been done same day if I had just written the three lines out properly.
Edge Cases and Workarounds
There is a scenario that catches most people off guard. When you deposit a check payable to someone else, like a joint tax refund or a reimbursement from a friend, the endorsement matters more than the slip. The slip itself does not capture endorsement information. You must sign the back of the check and write "For deposit only" with your account number below it. If the check is made out to two people, both usually need to sign unless your bank policy allows one signature. Most banks do allow one, but not all, and telling a teller "my bank lets me sign once" does not override their local policy. I ran into this exact issue last year with a contractor payment deposited to a business account. The check was signed by one owner only, and the other owner's signature was missing. The branch manager flagged it and asked for a letter of authorization from the second owner. I literally had to email the person at 6 PM, get a scanned letter, and resubmit the next morning. The slip was never the problem. The endorsement was. I learned to check both signatures before walking into the bank. Another edge case is depositing foreign currency checks. Standard deposit slips do not accommodate foreign-draw checks well. You need to note the currency and amount on the slip, and the teller will process it through a different clearing path. Expect a longer hold. Some smaller branches cannot process them at all and will transfer the item to a regional processing center. This adds roughly two to four business days to clearance compared to a domestic check.
Micro-deposits from some online platforms occasionally bounce back if the slip shows an amount different from what the originating system submitted. It sounds obvious, but I have seen tellers deposit $0.43 when the slip read $4.30 because the decimal was misread during quick handwriting. The return came back the same day. Always verify the numeric total before finalizing the slip.

What Happens After You Hand Over the Slip
The teller scans the slip and every check through the imaging system. The slip itself becomes part of the deposit record. Your account receives a transaction entry showing the total. Each check gets its own entry in the bank's internal ledger. The Federal Reserve or your local clearinghouse processes the checks next, which means they move from your branch to the paying bank through that network. Availability depends on the check type and your bank's policy. The Expedited Funds Availability Act sets baseline rules, but banks often exceed those limits. A standard direct deposit arrives the same business day. A local paper check may be available within one business day. Non-local checks often fall under the two-to-five business day window. Remote deposit capture through your phone does not use a physical slip at all, which is worth noting because it removes this entire process from your life if your bank supports it. One detail most people ignore: the slip receipt. The teller gives you a copy of the deposit slip stamped with the transaction details. Keep it. It is your proof of deposit if a check fails to clear or the amount posted incorrectly. I once had a $1,200 check show up as $120 in my online balance. The receipt showed the correct amount on file at the branch. The dispute resolved in under twenty minutes because I had the stamped slip. Without it, I would have been arguing against memory.
When Deposit Slips Are Actually a Bad Idea
Deposit slips are not useful for mobile deposits, ATM deposits, or wire transfers. They only apply to in-branch cash and check deposits handled face-to-face with a teller. If you are depositing recurring paychecks, setting up mobile deposit is faster and leaves a digital trail automatically. The physical slip adds nothing in that scenario. They also fall apart when depositing large volumes of scattered checks. I worked a payroll week once where I needed to deposit twenty-three small checks from various vendors. Filling out individual slips for each batch took about twelve minutes. Using the mobile deposit app took four minutes and eliminated the chance of a handwriting error entirely. For anything over ten checks, the app is usually the better choice. There is also a fraud risk with physical slips left on the counter. The slip shows your account number and recent deposit amounts. A crowded branch counter makes it easy for the next customer to glance at the form. Some banks have started masking the account number on printed copies for this reason, but not all. If you want to protect that information, cover the slip with your hand while waiting for the teller to process it, or tear off the customer copy and shield it until you leave the counter.
Finally, deposit slips do not prevent overdrafts. They do not verify your balance before submission. A teller will still let you deposit into a negative account if your bank allows it. The slip is just a paper instruction. It does not change account status or availability. If you are worried about a pending withdrawal pushing you into the negative, check your balance first through the app or online portal before going to the branch. The slip cannot help you avoid an overdraft fee.

Quick Reference Checklist
Before you hand a deposit slip to a teller, verify these items: Date is current and written in the correct format your bank requires. Account number matches the account you intend to credit. One digit off will route the money to the wrong place and correcting it takes a business day or two.
Check amounts are written clearly with no smudges. Illiterate handwriting causes manual review delays of one to two business days. Totals match between your line items and the final deposit figure. Recalculate once before handing the slip over. Endorsements are complete on every check being deposited, including "for deposit only" notation where appropriate.
Receipt is obtained and kept until the deposit posts correctly, which typically takes one business day for standard transactions. That is the whole thing. It is a low-tech tool that still exists because many people walk into branches every day and need something simple to write down what they are depositing. It works fine when you get the details right and causes small problems when you rush it. There is no hidden complexity here. Just write the numbers, sign the line, and keep the receipt.