Working-Class Kids and the Middle-Class Squeeze
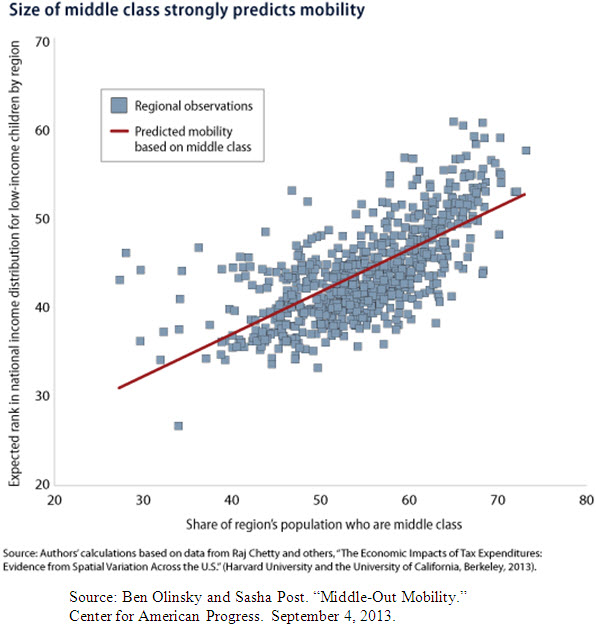
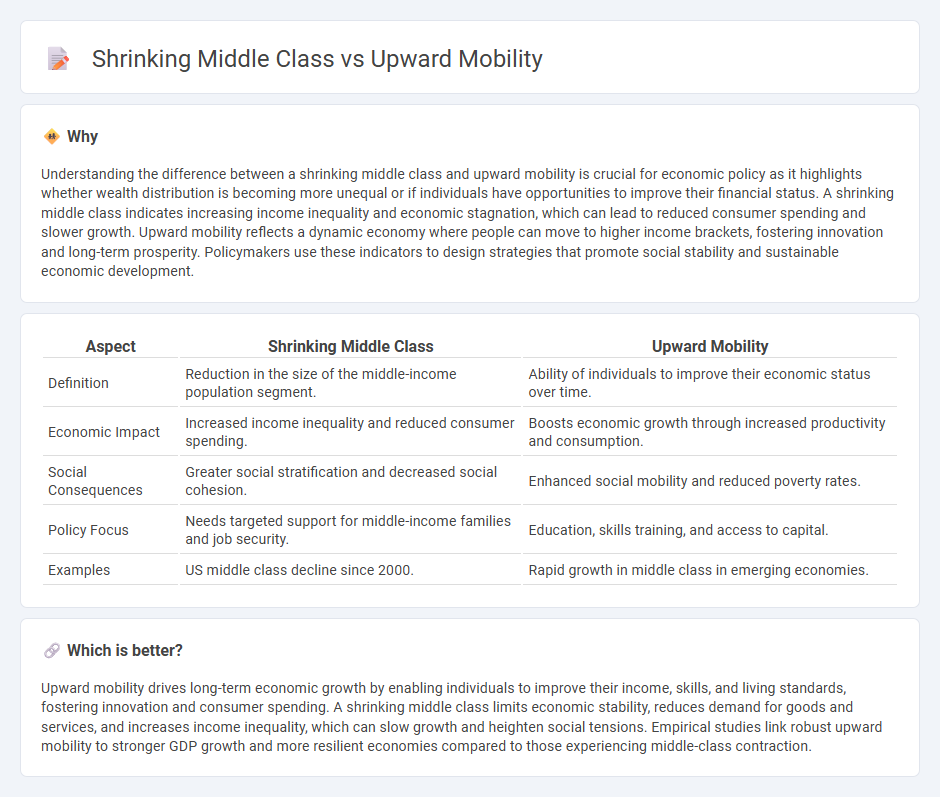
I've spent more years than I want to admit watching families get caught in the gap between what they were raised to expect and what their bank account actually allows. The middle class isn't disappearing in a dramatic fashion. It's getting squeezed from both sides by housing costs, student debt, wage stagnation, and a cultural narrative that insists upward mobility is a straight line anyone can climb if they just work hard enough. That narrative is mostly wrong, and pretending otherwise makes people feel like they're failing when the math was never on their side. Upward mobility means different things depending on where you start. For someone earning minimum wage, moving into a $45,000 salary job feels like progress. For a middle-income family making $90,000, getting to $120,000 might feel stagnant because their cost of living has already shifted. The aspirational version of upward mobility is usually painted as owning a home, sending kids to college without massive debt, retiring comfortably, and maybe having a bit of savings left over. The reality for a lot of people looks more like surviving month to month while hoping something changes.
The Elusive Middle Class Navigating The Aspirations Vs Reality Of Upward Mobility
Here's the part most advice columns skip. Education is still one of the more reliable paths out of low income, but it's also the most expensive. A 2023 Federal Reserve report showed that roughly 44% of Black households and 36% of Hispanic households carry student loan debt, compared to about 27% of White households. The debt doesn't just sit there. It delays home buying, retirement savings, and wealth accumulation by years or decades. I've sat across tables from people who have master's degrees and still can't qualify for a mortgage because their debt-to-income ratio is too high from loans they took out for careers that don't pay enough to offset them. That's not a personal failure. That's a structural problem. Housing is another place where the math quietly breaks. In many metropolitan areas, the median home price has outpaced median income growth by a factor of two or three over the last twenty years. A family earning the local median income today needs roughly twice the income to afford a typical home compared to what was needed in the early 2000s, even after adjusting for interest rate fluctuations. First-time homebuyer programs exist, but they're scattered, competitive, and often don't close the gap for moderate-income earners in expensive markets. One thing I ran into that nobody talks about much is the benefits cliff. This happens when a small raise or bonus pushes a household over an income threshold and they lose eligibility for childcare subsidies, food assistance, or housing vouchers. The effective marginal tax rate can exceed 50%, sometimes more. I knew someone whose employer gave a $3,000 annual raise and she ended up $1,200 worse off per year after recalculating her childcare costs, tax bracket shift, and loss of a local transit subsidy. She almost declined the raise. Not because she didn't want it, but because the net effect was negative. This is a real problem in middle-income households and it's virtually invisible in most policy discussions.
Another counter-intuitive point: diversifying your skill set across two or more income streams isn't always better than going deep in one career path. The common advice is to hustle harder, pick up a side gig, freelanced something extra. But for people already working full-time jobs with long commutes, adding a second income source often comes at the cost of health, relationships, and the ability to advance in the primary career. The data shows that deep specialization in a high-demand field usually produces more upward mobility over time than spreading yourself thin across multiple lower-paying roles. Side gigs are fine if they lead to something bigger or pay well enough to matter. Most don't. When it comes to actual strategies, here's what tends to work and what doesn't. Employer-sponsored benefits matter more than people realize. Health insurance, retirement matching, tuition reimbursement, flexible spending accounts. These are invisible parts of compensation that get ignored when people negotiate salary alone. A $5,000 lower salary offer with better benefits can be worth more than a $8,000 higher salary with worse ones. I once had a friend turn down a promotion at one company because the new role eliminated their childcare subsidy eligibility and moved them into a higher insurance tier with worse coverage. The math didn't work. She stayed and got promoted elsewhere six months later with both the title bump and the benefits intact.
Get the Full Details
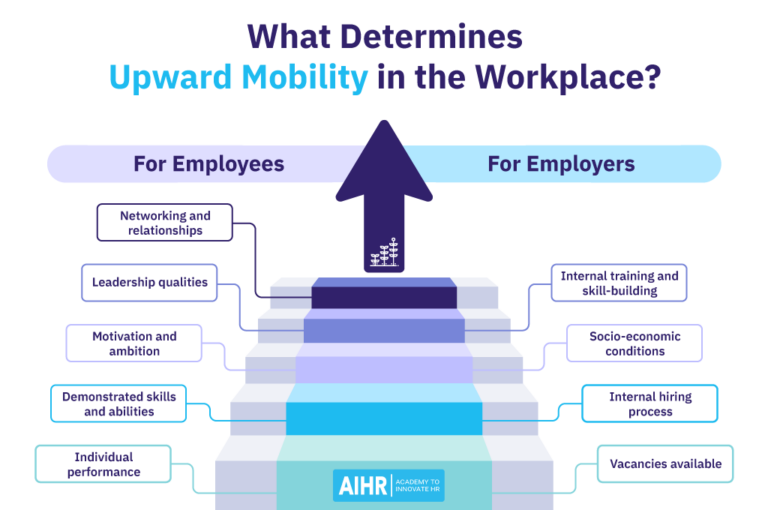
Geographic mobility is underutilized. Moving from a high-cost area to a moderate-cost area for a similar salary can effectively increase purchasing power by 30 to 50 percent. This isn't always easy. Family ties, spouse employment, and emotional costs are real. But for people whose primary goal is building wealth and reducing financial stress, it's one of the most powerful levers available. Remote work has changed this significantly. People who previously had to physically relocate for a job now have more options, though remote pay compression in some industries has somewhat offset the advantage. Networking within your target industry beats general networking. Most jobs at the middle-class level aren't filled through applications. They're filled through referrals. A 2022 study by the National Association of Colleges and Employers found that referral candidates are hired at roughly twice the rate of cold applicants and retain employment longer. This means building genuine relationships with people already in the roles or industries you want, not collecting business cards at events you don't belong at yet. Find the people doing the job you want, ask them specific questions about their day-to-day work, and offer something useful in return. Not favors. Information, skills, introductions. Relationships are built on reciprocity, not transactions. The timing of major financial decisions matters enormously. Going back to school, buying a car, getting married, having children, these decisions interact in ways that compound over decades. Someone who gets a bachelor's degree at 25, buys a modest home at 30, and starts a family at 32 follows a very different financial trajectory than someone who does the same things at 32, 37, and 40. The difference isn't just about age. It's about compounding, tax brackets, and the window of opportunity for certain programs and policies. This is why life planning matters as much as budgeting.
There are honest limitations to all of this. No amount of smart decision-making will fully compensate for being born into poverty in a high-cost area with weak schools and limited job markets. Structural factors matter. Discrimination in hiring, lending, and housing still exists and affects outcomes independently of individual choices. Some people will do everything right and still not see the mobility they're aiming for, simply because the starting line is further back than others'. Acknowledging this doesn't mean giving up. It means being realistic about what individual actions can and cannot achieve. For those who have some resources to begin with but are stuck between comfortable and secure, the main obstacle is often over-optimism about investment returns and under-investment in career advancement. People will spend hours researching stocks and ETFs while spending almost no time developing skills that directly increase their earning power. The biggest single factor in upward mobility for the middle class is income growth. Investment returns are secondary, especially in the early and middle stages of a career. Focus on making more money first. Optimize investments later. If you're looking at practical next steps, start by mapping your current position honestly. Income, expenses, debt, assets, skills, network, and geographic flexibility. Then identify the single highest-leverage action you could take in the next twelve months. For most people, that's either changing jobs, changing locations, or changing career tracks. Everything else is optimization around that core decision.