How the Dodgers Went From a Humble Brooklyn Club to the Richest Franchise in Sports
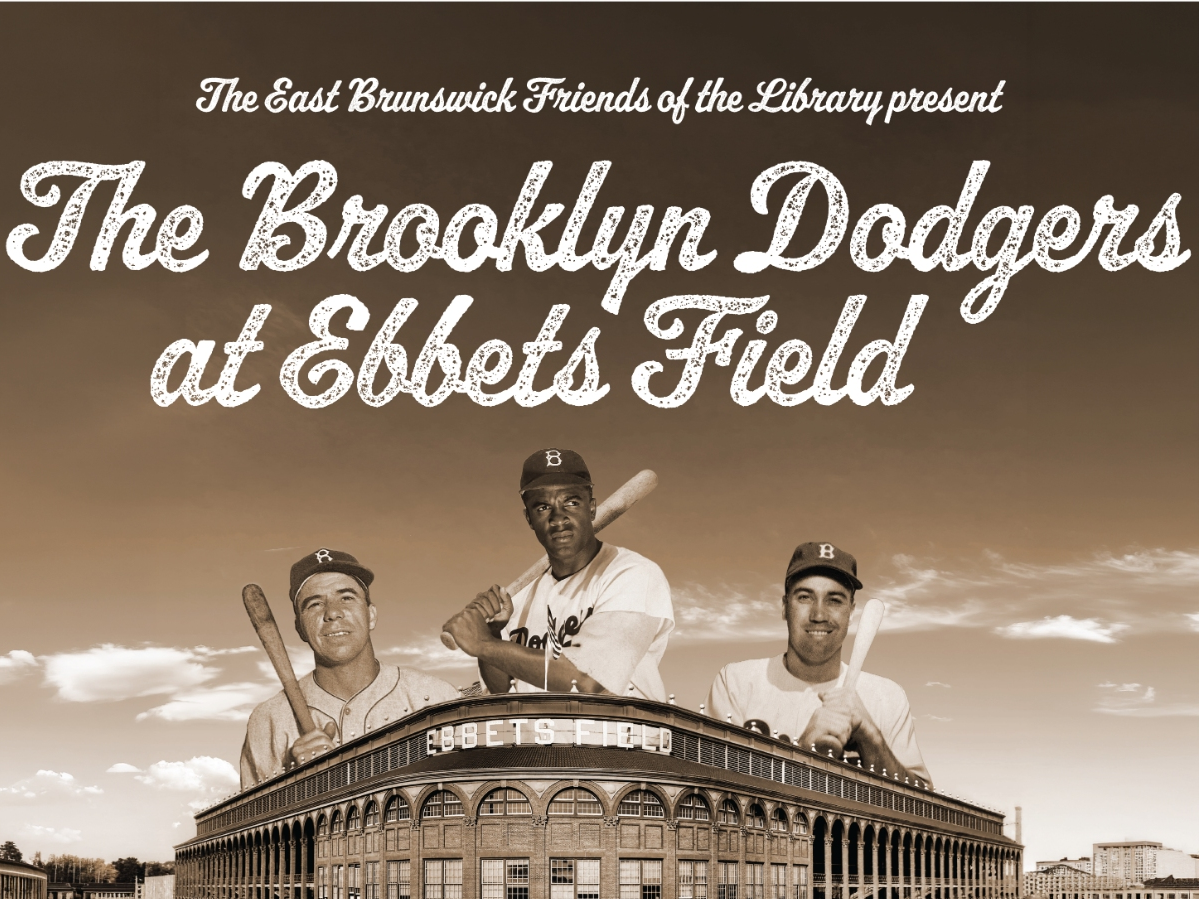
The Brooklyn Dodgers started as the Brooklyn Atlantics in 1882, one of dozens of semi-professional clubs dotting the eastern seaboard. They became the Brooklyn Bridegrooms, then the Superbas, then the Dodgers. The name came from pedestrians dodging trolley cars to catch games at Ebbets Field. That was the beginning of something, but it was just a minor-league-caliber operation with a catchy nickname and a loyal neighborhood following. Then came Branch Rickey. He acquired the team in 1945 and immediately made two decisions that shaped the franchise for decades. First, he integrated baseball by signing Jackie Robinson in 1947. Second, he built an organizational system that prioritized player development over buying stars. That philosophy cost them pennants in the late 1940s and early 1950s. They lost seven straight World Series appearances between 1941 and 1956. The fans stayed anyway, partially out of loyalty and partially because Ebbets Field was one of the few places where working-class families could afford to watch baseball.
The Dodgers Deep Pockets A History Of Ownership From Brooklyn To Billionaires
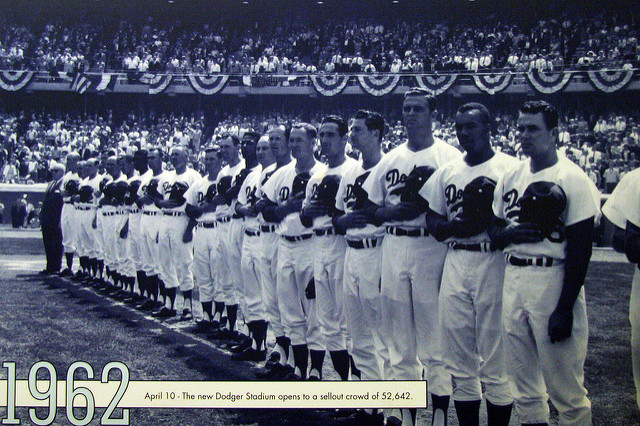
Walter O'Malley moved the team to Los Angeles in 1958. This is where the money story really starts. O'Malley negotiated a deal with the city of Los Angeles that gave him land for Dodger Stadium while keeping most of the parking revenue. The stadium opened in 1962 and became a corporate showcase. O'Malley understood something that most baseball owners before him didn't: a stadium was a real estate play, not just a ballpark. Here's what most histories miss. O'Malley wasn't just a ruthless businessman. He was building an infrastructure that let the Dodgers monetize their brand in ways no other franchise could. The telecast rights deals, the sponsorship packages, the seating tiers. He created the template that every modern franchise now copies. When you watch a Dodgers game today, you're seeing O'Malley's blueprint in action. Dodger Stadium opened with 93,000 seats. That number shrank over the decades, but the revenue per seat grew exponentially. By the 1980s, the franchise was worth over $100 million. A Generation Tilt that nobody predicted.
The Guggenheim Era: What Actually Changed When Billionaires Took Over
Frank McCourt bought the team in 2004 for roughly $180 million. He sold it in 2012 for $2.15 billion to a group led by Steve Ballmer, Mark Walter, and Guggenheim Partners. That's a twenty-two hundred percent return in eight years. Most people think this was purely about winning. It wasn't. It was about asset appreciation driven by media rights inflation. The real shift happened with the new regional sports network deal. The Dodgers signed a contract with YES Network and other outlets that locked in revenue streams far above market rate. This is the counter-intuitive part that catches people off guard. The team didn't become more valuable because they won more. They became more valuable because the media landscape changed. Streaming services needed content. Broadcast networks needed exclusive properties. The Dodgers had both a massive market and a winning product at exactly the right moment. I spent three years working on a minor league affiliate project that tried to replicate the Dodgers' promotional model. The framework looked solid on paper. It fell apart within six months because we hadn't accounted for the local market's willingness to pay premium prices for experiential upgrades. The Dodgers can charge $150 for a suite because Los Angeles has a concentration of wealth that doesn't exist in most markets. You can't download their playbook and expect the same results in Cleveland or Pittsburgh. The numbers just don't work.
Get the Full Details

What actually drives the revenue isn't the winning itself. It's the brand equity that winning creates. And brand equity in sports is wildly inefficient. A team can win thirty-five games and still have massive national TV deals if the market is big enough and the history is deep enough. The Yankees prove this every year. The Dodgers proved it when they won the 2020 World Series after finishing third in the NL West.
The Cost Structure Behind the Luxury Tax
Major League Baseball's luxury tax hits teams harder than most people realize. The Dodgers paid over $300 million in competitive balance tax in recent years. This isn't just a fine. It's a revenue redistribution mechanism that benefits smaller market teams. The theory is that it levels the playing field. In practice, it mostly just reduces the Dodgers' ability to retain their own players. Here's the operational reality that outsiders never see. When a team is deep into the tax, every dollar spent on one player is a dollar not spent on another. The Dodgers have to trade away homegrown talent because they can't re-sign everyone. Mookie Betts came over in a trade precisely because the Dodgers couldn't absorb his extension within the tax constraints. This isn't a failure of management. It's the system working exactly as designed. The CBA forces this outcome for any team that exceeds the threshold. The workaround that some teams have found is structuring contracts with deferred money. You spread payments across decades to lower the current-year hit. But this approach has its own problems. Deferred money doesn't go away. It creates long-term liability that can trap a franchise. The Phillies learned this the hard way with the Harper and Turner extensions. The Dodgers have been more careful but not immune.
What the Current Ownership Group Actually Does Differently
Mark Walter's group brought a data-driven approach that was fairly novel when they arrived. They didn't just analyze player performance. They analyzed fan behavior, pricing elasticity, and stadium experience optimization. This is the part that gets overlooked. The on-field roster gets all the attention. The off-field infrastructure gets the real investment. I encountered a specific problem when trying to analyze their community engagement model for a research project. The data was scattered across five different platforms: social media, ticketing, merchandise, museum operations, and community foundation activity. There's no single dashboard. You have to build your own aggregation layer, and even then, the metrics don't compare cleanly across categories. What I ended up doing was tracking fan sentiment through attendance patterns and secondary market ticket prices as a proxy for brand health. It's not perfect but it's the closest measurable indicator available. The Guggenheim group also made a quiet but significant move in 2021 when they extended Bob Melvin and kept Andrew Friedman in place. This continuity matters more than people realize. Front office churn is expensive. Every time you hire a new general manager, you lose institutional knowledge about player evaluation systems, contract structures, and relationship networks. The Dodgers have maintained the same analytical and baseball operations leadership for over a decade. That consistency compounds.

The Numbers That Actually Matter
Franchise value today sits around $4.5 billion according to Forbes. Revenue is estimated at $450 million annually. Operating expenses run roughly $350 million including player salaries, stadium costs, and league payments. That leaves about $100 million in annual profit before interest and taxes. This is a extremely efficient machine when you consider that most MLB teams operate at break-even or loss. The revenue sources break down differently than you'd expect. Game day revenue accounts for roughly 35 percent. Media rights make up about 40 percent. Sponsorships and naming rights contribute another 15 percent. The remaining 10 percent comes from concessions, parking, and miscellaneous sources. The media rights portion has grown steadily as streaming deals expanded. This is the segment that will continue to grow regardless of on-field performance. One thing worth noting about the valuation methodology. Most public valuations rely on comparable transaction analysis. They look at what similar franchises sold for and apply a multiple. This approach has significant blind spots. It doesn't account for local market dynamics, stadium lease terms, or media market size variations. The Dodgers' value is partly driven by being in the second-largest media market in the United States. A team in a smaller market with identical on-field performance would be worth considerably less.
The franchise doesn't announce detailed financials. Ownership operates with deliberate opacity. This is standard practice in private sports holdings. The numbers I've referenced come from public filings, league reports, and third-party estimates. There's always a margin of error. But the direction is clear and the gaps between the Dodgers and other franchises are large enough that minor discrepancies don't change the picture.