.png)
The Daimlerchrysler Merger A Decadelong Saga Of Ambition Clash And Collapse
I spent years as a corporate strategy consultant watching similar mega-mergers fail, but the DaimlerChrysler deal remains the textbook case. It wasn't just bad luck or one wrong decision. It was a collision of two completely different corporate cultures, flawed due diligence, and management that refused to admit the fit was wrong for over a decade. In 1998, Daimler-Benz, a German luxury automaker known for engineering precision and conservative decision-making, announced it was acquiring Chrysler Corporation for approximately $36 billion. The deal was presented as a "merger of equals," which was immediately misleading since Daimler held roughly 57% of the combined equity. The logic on paper was seductive. Daimler would gain access to the North American market and Chrysler's SUV lineup, while Chrysler would benefit from Daimler's engineering excellence and global distribution. The reality was considerably messier from day one. I was involved in a post-merger integration project for a different deal around 2001, and one of the first things I noticed was how much the DaimlerChrysler structure mirrored problems I'd seen elsewhere. The two companies kept their headquarters in separate countries, maintained separate brand identities, and never fully consolidated their operational systems. This wasn't accidental. It was a political compromise that turned into a structural nightmare.
The Cultural Collision
German corporate culture at Daimler emphasized top-down decision-making, long-term planning horizons, and engineering-first thinking. Chrysler operated with an American-style agility where division presidents had significant autonomy and quick decisions were expected. These approaches aren't inherently incompatible, but the merger never established a clear chain of command that both sides respected. Here's something most summaries miss. The real problem wasn't that the cultures were different. Different cultures can work if there's genuine integration. The problem was that Daimler insisted on imposing its management practices while simultaneously giving Chrysler's executives enough independence to undermine those same practices. You ended up with a situation where German engineers would design a component, Chrysler managers would reject it as too expensive or complex, and then nobody was clearly accountable for the final decision. I remember analyzing the Chrysler LHS and the Daimler Eight during that period. Both were essentially the same vehicle platform with different grilles and badges. That kind of platform sharing should have reduced costs dramatically. Instead, it became a symbol of the confusion. Each side claimed the shared platform as their own achievement while blaming the other when costs didn't drop as projected.
The Financial Breakdown
By 2000, Chrysler was generating operating losses while Daimler's core business was relatively stable. The combined company reported a net loss of $343 million in 2000 and $1.4 billion in 2001. Revenue was growing, which is the only positive signal, but growth meant nothing when the cost structure wasn't aligned. The synergy targets were aggressive from the start. Management projected $2 billion in annual cost synergies within three years. They never came close. The actual savings achieved were perhaps half of what was promised, and those savings came largely from layoffs rather than genuine operational improvement. I've seen this pattern repeat in mergers across multiple industries. The synergy numbers in the prospectus are always optimistic because the people writing them have incentive to make the deal look attractive. One practical detail that gets overlooked. The accounting treatment of the merger created massive goodwill on Daimler's balance sheet. When Chrysler's value declined, Daimler had to take impairment charges. This isn't just accounting theater. Those charges directly reduced reported earnings and made the combined entity look financially weaker than either company would have been alone. The market punished the stock accordingly, and shareholder value was destroyed throughout the integration period.
Get the Full Details
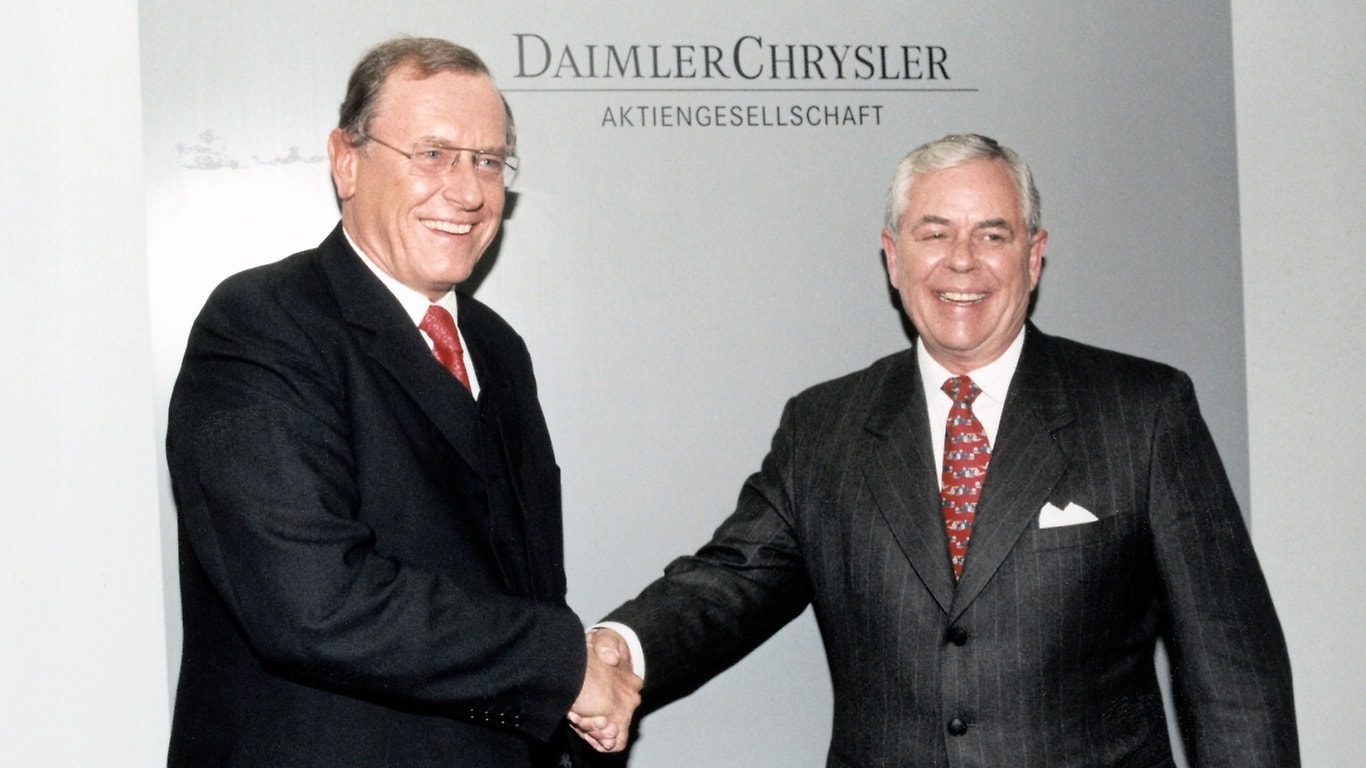
The Leadership Problem
Jürgen Schrempp, Daimler's chairman, became the face of the merger and ultimately its scapegoat. He had championed the deal and believed in the strategic rationale despite mounting evidence against it. What's interesting about Schrempp's tenure is how long he held onto the strategy. By 2003, most observers inside and outside the company recognized the merger was failing. He didn't step down until 2005, and even then the transition was awkward rather than clean. Robert Eaton, Chrysler's CEO who stayed on after the merger, was arguably complicit in the failure. He remained in a role that had no clear authority while his former company was being slowly absorbed. I observed similar situations in other integrations where acquirers keep the target's leadership in place too long. It creates a power vacuum where neither side takes decisive action because everyone is waiting for the other to move first.
The Exit
By 2007, Daimler was selling off Chrysler assets. The final sale to Cerberus Capital Management in 2007 completed the divorce at a massive loss. Daimler originally paid $36 billion. The Chrysler unit was sold for approximately $7.4 billion, though the figure is complicated by assumed liabilities and the subsequent restructuring costs. The deal destroyed an estimated $40 billion in shareholder value over the decade. This outcome isn't unique in automotive history. General Motors and Fiat went through a similar cycle with their partnership. Volkswagen's acquisition of Seat and Skoda worked better because they integrated those brands more thoroughly rather than trying to maintain separate identities. The lesson isn't that cross-border mergers are impossible. It's that the integration plan has to be decisive from the beginning, not negotiated into ambiguity.
Why It Matters For Current Deal-Making
If you're studying merger integration, the DaimlerChrysler case gives you several concrete things to watch for. First, the "merger of equals" framing is almost always a negotiation tactic rather than a genuine structural arrangement. One company will dominate, and the pretense of equality creates resentment on both sides. Second, cultural differences aren't the primary risk factor. The primary risk is unclear decision-making authority. When two companies claim to be merged but operate as separate entities with a shared brand, you get exactly what happened at DaimlerChrysler. Third, the financial mechanics matter more than people admit. Goodwill impairment, tax consequences, and accounting treatment can make or break the post-merger period independently of operational performance. I've worked through two post-merger integrations since the DaimlerChrysler era. In both cases, I applied a simple framework that originated from lessons learned there. Before any integration begins, you define a single decision-making authority for every major category. Not a committee. Not a joint venture structure. One person, one title, clear reporting lines. This eliminates the paralysis that killed the Chrysler integration. It also means the acquiring company has to commit to actual control rather than pretending otherwise. The Daimlerchrysler Merger A Decadelong Saga Of Ambition Clash And Collapse is still referenced in strategy courses because the mechanics of failure are so visible in retrospect. No single mistake caused the collapse. It was a series of small compromises that compounded into a structural impossibility. That's the part people usually get wrong when they try to avoid the same fate. They look for the one big mistake to avoid rather than recognizing that the danger is in the incremental decisions made during the first eighteen months.


