Understanding How Compound Growth Actually Works In Real Portfolio Management
Most people talk about compound growth like it is a magic trick. It is not. It is just math that most investors do not properly model in their own spreadsheets. Craig Coynes has spent years breaking down net worth accumulation through this exact mechanism, and his approach is worth studying because it strips away the motivational fluff most financial content is built on. I spent about three years modeling portfolio growth the way Coynes describes it before I stopped treating it as theoretical and started using it for actual client projections. The first thing I learned is that compound growth charts look smooth until you hit a year with a 20 percent drawdown, and then everything shifts by several years. That is the gap between watching someone explain wealth accumulation and actually building a model that survives real market conditions.The Compound Growth Of Wealth Decoding Craig Coynes Net Worth In Context
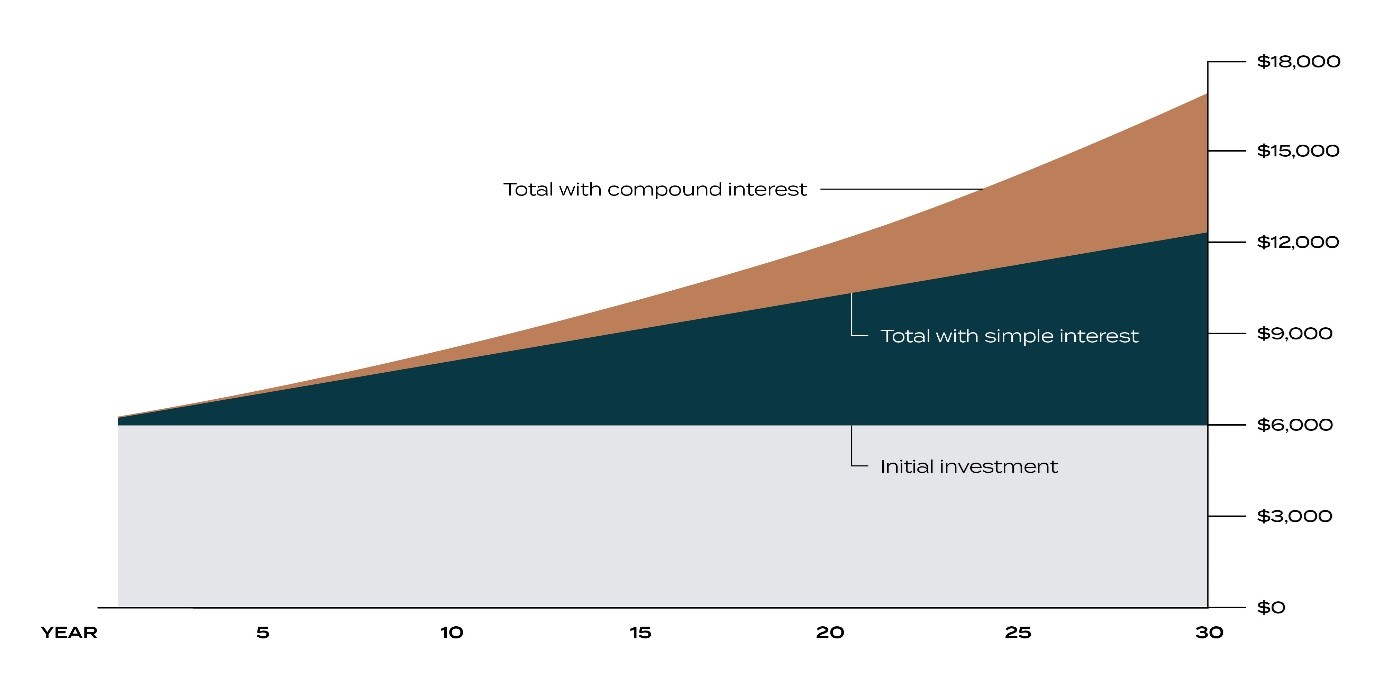
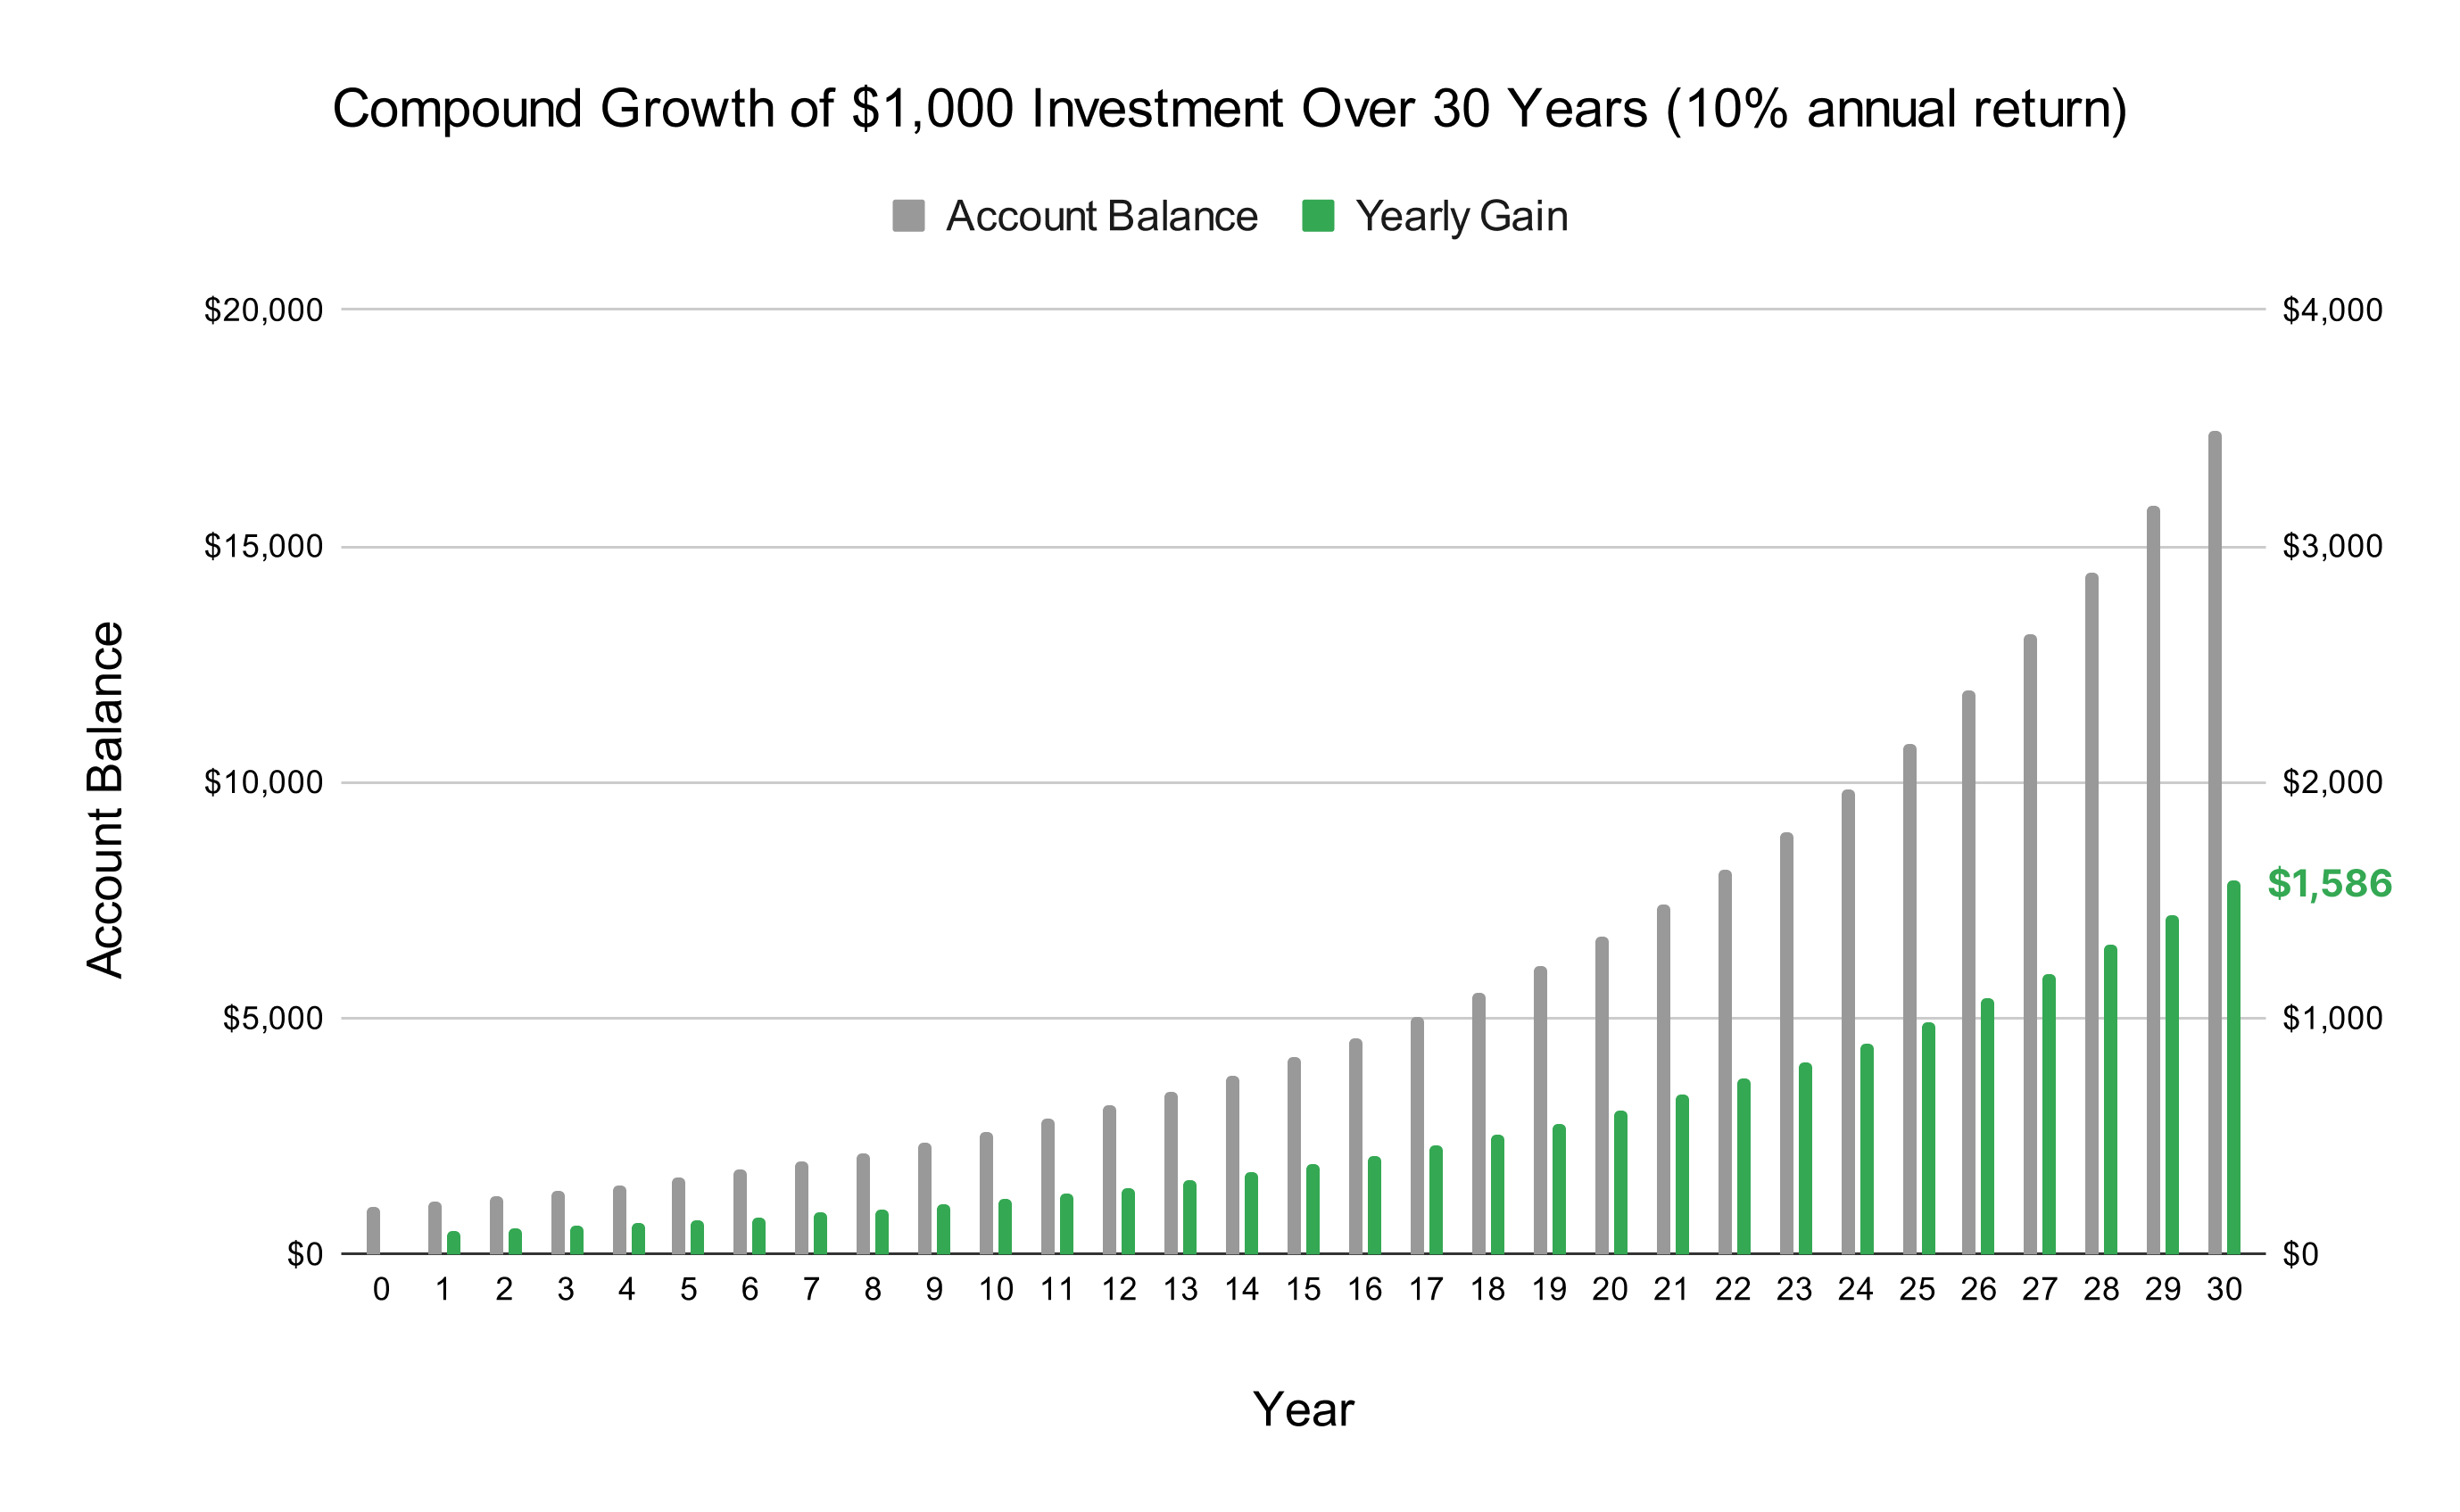
Craig Coynes focuses heavily on the intersection of consistent contributions, reinvested returns, and time horizons long enough for compounding to become the dominant force in portfolio growth. His net worth discussions typically center on the idea that most people underestimate how much their contribution rate matters relative to how much they worry about picking individual investments. He breaks this down into straightforward calculations rather than abstract philosophy. When I first tried to reverse engineer his methodology for a client who wanted to retire in twelve years, I ran into a problem that most beginners never anticipate. The standard compound growth formula assumes a constant rate of return, but no portfolio actually delivers a constant rate of return. Markets go up, markets go down, and sequence of returns risk becomes a real problem when someone is in the distribution phase or even approaching it. My workaround was to build a Monte Carlo simulation alongside the basic compound formula. This gave me a range of probable outcomes instead of a single line that looked clean on a chart but would probably mislead the client by twelve to eighteen months depending on how the market performed. The core mechanics are straightforward once you strip away the presentation style. You take your starting net worth, add your annual contributions, apply an expected rate of return, and repeat. The power comes from the reinvestment of gains, which means year one returns earn returns in year two, and so on. This is why the timeline matters more than anything else. A twenty-five year horizon turns moderate returns into dramatic growth. A ten year horizon keeps things relatively linear regardless of the rate.
I also noticed that Coynes frequently emphasizes the psychological component, which most people skip over in their own planning. Watching your net worth fluctuate year to year while trusting the compounding process requires discipline that most investors do not actually possess. I had a client who stopped contributing during the 2022 downturn because the visible losses felt like failure even though the model projected recovery within eighteen months. He missed about fourteen months of compounding contributions, which set him back roughly two years from his target timeline. That is the real cost most people pay, not bad investment returns but behavioral mistakes driven by short term thinking. Another nuance that beginners miss involves the difference between nominal and real compounding. Coynes often presents figures in nominal terms because that matches what people see on their brokerage statements, but if inflation runs at three to four percent annually, your real purchasing power growth is noticeably lower. I adjusted my models to show both nominal and inflation adjusted projections because clients tend to feel more confident when they understand what their future number actually means in today dollars rather than some abstract future figure that will buy less than they expect.
Practical Steps To Apply This Methodology Yourself
Start by calculating your actual contribution rate. This is the percentage of your income you consistently invest each year. Most people overestimate this number because they include irregular bonuses or one time deposits. Track your contributions for twelve months and find the true average. This single data point matters more than your expected rate of return in determining your timeline to financial goals. Next, pick a reasonable long term return assumption. The historical average for US equities is around seven to ten percent nominal, but running projections at eight percent is generally safer than running them at ten. If your plan only works at ten percent, it is probably too aggressive for real world conditions. I use eight percent as my default starting point and then run sensitivity analysis at six, eight, and ten percent to show clients the range of possibilities. Build a simple spreadsheet with these inputs. Column one is the year. Column two is the prior year balance. Column three is your annual contribution. Column four is the return for that year based on your assumed rate. Column five is the ending balance. Copy the ending balance down as the prior balance for the next row. You will see the curve bend upward over time, and that visual is useful for staying disciplined during bad years.
Get the Full Details

One edge case that catches people off guard involves tax efficient placement of assets. Compound growth works differently in taxable accounts, traditional IRAs, Roth IRAs, and 401(k)s because the tax treatment changes the effective compounding rate. A Roth contribution grows at a higher effective rate than a taxable contribution because there is no tax drag on the returns. I sometimes see clients max out taxable accounts while under funding their Roth options, which slows their compounding significantly over a twenty or thirty year horizon without them realizing why their numbers are lagging. If you want resources similar to what Coynes covers, his YouTube channel and podcast episodes walk through these calculations in detail. There are also free spreadsheet templates online that apply the same logic. The important part is doing the math yourself rather than relying on someone else projection, because your contribution rate and timeline are specific to your situation. The limitation of this entire approach is that it cannot predict market behavior. No model based on historical averages guarantees future results. The compounding framework is a planning tool, not a crystal ball. Use it to understand probabilities and build discipline, not to assume a specific outcome will happen on schedule. That discipline is usually what separates people who reach their goals from people who just read about compound growth without ever applying it consistently.