Getting Paid Right Is Harder Than It Should Be
Royalty calculations are the kind of thing that seems straightforward until you actually try to do it and discover the spreadsheet has been lying to you for six months. I spent three weeks last year reconciling a licensing deal where the publisher's quarterly report showed a $47,000 discrepancy compared to our internal books. The problem wasn't fraud. It was a clause buried in section 14.b about bundled sales and whether a physical book included with a software box should count as a discounted unit or a full retail transaction. The fine print said discounted. Our accounting team interpreted it as full retail. Neither of us was technically wrong without reading the exact wording. Most people think royalty calculation is just multiplying units sold by a rate. It is not. It is a system of nested definitions, jurisdiction-dependent rules, and terms that shift depending on format, geography, and time period. Getting it right requires understanding the contract before you set up your tracking system, not after someone asks for an audit.
The Complex World Of Royalty Calculation Navigating The Fine Print
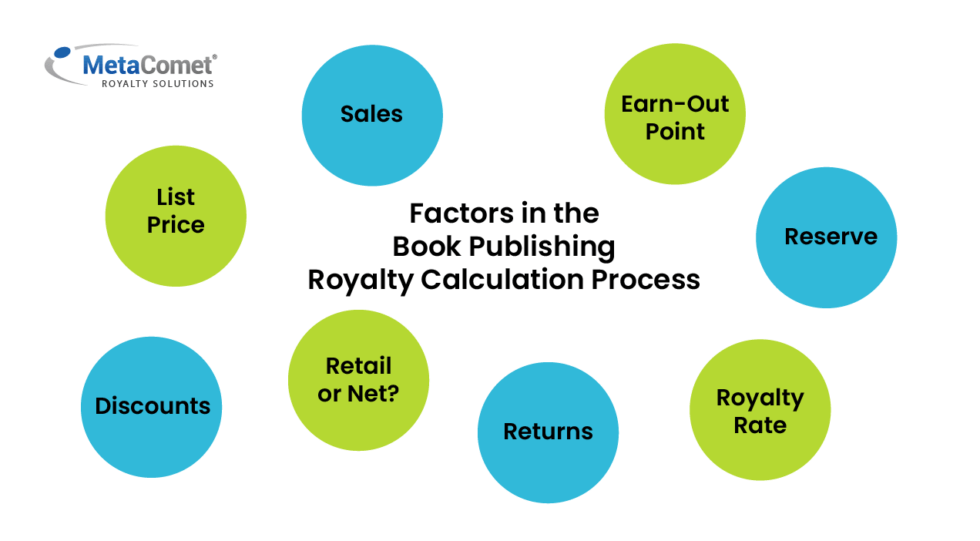
Here is how it actually works in practice. Start with the rate card. This is the section that lists percentages for different formats. E-book, print, audiobook, subsidiary rights, international translations. Each one has its own base calculation method. A standard e-book royalty might be 25% of net receipts, while a print royalty sits at 10% of list price. The difference between net receipts and list price matters enormously when you are dealing with bulk distribution channels that take steep cuts. Net receipts means what the publisher actually received after deducting returns, discounts, and distribution fees. List price means the printed price on the book. If you earn 25% of net receipts on an e-book sold through Amazon at a 40% discount, you are not earning 25% of the sticker price. You are earning 25% of whatever Amazon remitted after taking their cut. This is where most independent creators get tripped up. They see "25% royalty" and assume 25% of the cover price. It is never 25% of the cover price for digital channels. Payment terms introduce another layer. Standard terms are 60 days after quarter end. Some contracts specify 90 days. During that gap, books can be returned, which means reported sales might drop when returns come in. I have seen a report show 10,000 units sold in Q2 and then 6,000 units confirmed after the return window closed. The initial payment will be wrong if you are not accounting for return reserves. Set up a buffer in your forecasting model. Track the historical return rate for each title and channel, and build in a deduction from day one rather than reacting when the adjusted statement arrives.
Different formulas apply depending on the revenue model. For traditional publishing, the formula is usually straightforward: units multiplied by the royalty rate applied to the defined base. For subscription services like Kindle Unlimited or Scribd, the payment comes from a global fund divided by total pages read. Your per-read rate fluctuates based on how many books are in the pool and how many pages are consumed across all titles. There is no fixed per-download rate. The math is opaque and intentionally so. Publishers call it the NRP or National Royalty Pool model. Creators call it a black box because they cannot predict month to month what they will earn from it. Here is a specific example I ran into recently. A client had a contract with a foreign distributor that specified payment in euros, but the contract also contained a currency fluctuation clause. The clause stated that if the euro weakened more than 5% against the dollar between the reporting date and the payment date, the shortfall would be absorbed by the distributor. We tracked the exchange rate manually using OANDA's daily close rates, which took about 20 minutes per quarter. The clause triggered once in a 12-month period and saved us approximately $1,800. Without monitoring the rate, we would have accepted the lower converted amount and written off the difference. Tiered royalties are another area where the fine print does real damage. Many contracts use escalating percentages based on units sold. You might earn 10% on the first 5,000 units, 12.5% on units 5,001 to 10,000, and 15% on everything above 10,000. The trap here is whether the tier applies to the entire run or only to units within each bracket. Some contracts structure it so that once you cross 5,000 units, every unit retroactively gets the higher rate. Others keep it strictly marginal. I found this out the hard way when a contract used ambiguous language that let a publisher apply marginal tiering to a title that had clearly crossed 10,000 units. The correct interpretation, once we pointed to the standard industry definition of tiered royalty structures, cost us about $3,200 in delayed payment. Negotiating clear language about retroactive versus marginal tiering upfront would have prevented the entire dispute.
Get the Full Details

Minimum guarantees are frequently misunderstood. A $5,000 advance against royalties is not extra money. It is a prepayment that gets recouped before you see another check. If your royalties in the first year total $3,000, you do not receive an additional $2,000 from the minimum guarantee. You receive nothing until your cumulative royalties exceed the advance. This is basic recoupment accounting, but creators who come from flat-fee sponsorship deals often expect the advance to function differently. It does not. It functions as a loan against future earnings with no interest and no obligation to repay if earnings fall short. Audits are the nuclear option and they should be treated like one. Most contracts give you the right to audit the licensee's records once every 12 to 24 months with 30 days written notice. The cost of the audit is typically borne by the auditor unless the discrepancy exceeds 10%, in which case the licensee covers it. I have audited three statements in ten years. Two of those audits found underpayments totaling roughly $14,000. The third found nothing, which means I paid $4,500 out of pocket for an audit that returned zero. Factor this risk into your decision. Auditing makes sense when you have high-volume sales across multiple formats and channels. It makes less sense for a single-title author with straightforward print-only distribution. subsidiary rights complicate everything further. When you license translation rights, film rights, or audio production rights, each subsidiary agreement has its own royalty structure that may or may not flow through your primary publishing contract. Some contracts state that subsidiary income is shared 50/50 between you and the publisher after agency fees. Others assign a fixed percentage. The fine print in your main contract should explicitly define whether subsidiary income counts toward advance recoupment or sits outside it. This distinction alone can change your effective royalty rate by several percentage points over the life of a deal.
Here is a counter-intuitive point that most people miss. A lower stated royalty rate can sometimes be more valuable than a higher one depending on how the base is defined. A contract offering 15% of net receipts with a broad definition of net (after minimal deductions) can pay more than a contract offering 20% of list price with aggressive distributor deductions stacked on top. The headline number is almost never the whole story. Always model the effective rate by estimating actual deductions per channel before signing anything. Another common oversight involves reserving inventory for returns. Publishers are required to hold back a percentage of royalties to cover potential returns, usually between 15% and 25%. Some contracts cap this reserve after a certain period, like two years from publication. Others do not. If your contract does not specify a release date for the reserve, that money stays locked indefinitely. I worked with an author who had $8,000 in unclaimed reserve sitting on the publisher's books for three years because the contract never defined when it should be released. The clause was there, but it was conditional on the publisher sending a notification that they never sent. We had to reference the industry standard of reserving returns for 18 months post-publication and push back formally. The reserve was released after a letter from our accountant. Tracking systems deserve attention. Manual spreadsheets work for one or two titles with simple terms. Once you have five titles across four formats with varying rates, territories, and payment schedules, manual tracking becomes unreliable. I switched to a combination of a structured database and automated statement parsing about two years ago. The setup took roughly six hours initially. It now processes incoming statements in about 15 minutes per quarter and flags discrepancies automatically. The cost of not automating, measured in time spent chasing errors, is significant. You will spend at least 3 to 5 hours per royalty period reviewing statements manually, and you will miss something every time.
Language precision matters more than most people realize. Words like gross, net, list, and wholesale have specific meanings in publishing contracts that differ from their everyday usage. Gross revenue means total income before any deductions. Net revenue means gross minus agreed deductions. List price means the manufacturer's suggested retail price printed on the book. Wholesale price means the price at which the publisher sells to distributors. Each definition changes the numerator in your royalty calculation. If your contract says your royalty is 10% of gross receipts but does not define gross, the publisher will define it as they see fit. Always insist on explicit definitions in the contract itself, not in an addendum or external document. The biggest limitation of royalty calculation systems is that they cannot protect you from bad contract language. No tool catches ambiguity. No software fixes a clause that says "publisher's standard rate" without defining what that rate is. Automation only works when the input terms are clear and fixed. If your contract leaves room for interpretation, the best tracking system in the world will produce accurate numbers based on incorrect assumptions. If you are dealing with complex multi-format agreements, the practical workaround is to create a living document alongside each contract. This document translates every clause into a plain-language operational rule with the exact calculation path. It includes the defined base, the applicable rate, the payment schedule, the reserve policy, the audit clause, and the dispute resolution process. When a statement arrives, you compare it against this document line by line. The entire review takes about 20 minutes for a well-structured agreement. The alternative is opening a PDF and hunting for the relevant clause while trying to remember what it actually said.

What to Watch For Before You Sign
Check the definition of net receipts carefully. Look for exclusions that seem unusually broad. Verify whether subsidiary income recoups from the same advance or a separate one. Confirm the return reserve duration and release conditions. Make sure audit rights include access to underlying source data, not just summaries. Ensure currency fluctuation protection if international sales are involved. Define what happens if the publisher goes bankrupt or sells the title to another house. The people who do best with royalty calculation are the ones who treat the contract as a technical specification, not a legal formality. Every word in that document maps directly to money. Read it like an engineer reads a blueprint. The fine print is where the actual work happens, and the work is entirely in the definitions.