How NYC Property Tax Actually Works When You Own a Home Here
The system is not designed to be intuitive. I have dealt with enough of these cases over the years to know that the average homeowner will walk into a mistake the moment they receive their property tax bill and try to verify the numbers on their own. The NYC tax assessment process uses a classification and ratio framework that produces wildly different tax outcomes for nearly identical properties depending on how the building is classified. Most people who move into a house in Queens or the Bronx discover this the hard way. They compare their tax bill to what their neighbor pays and assume the assessor made an error. Sometimes the assessor did make an error. Sometimes the difference comes from the underlying classification system itself. Understanding which one you are dealing with saves you from filing appeals that will get rejected before the clerk even reads them.
The Complex World Of Property Tax In NYC Navigating The System For Homeowners
Understanding Property Classification
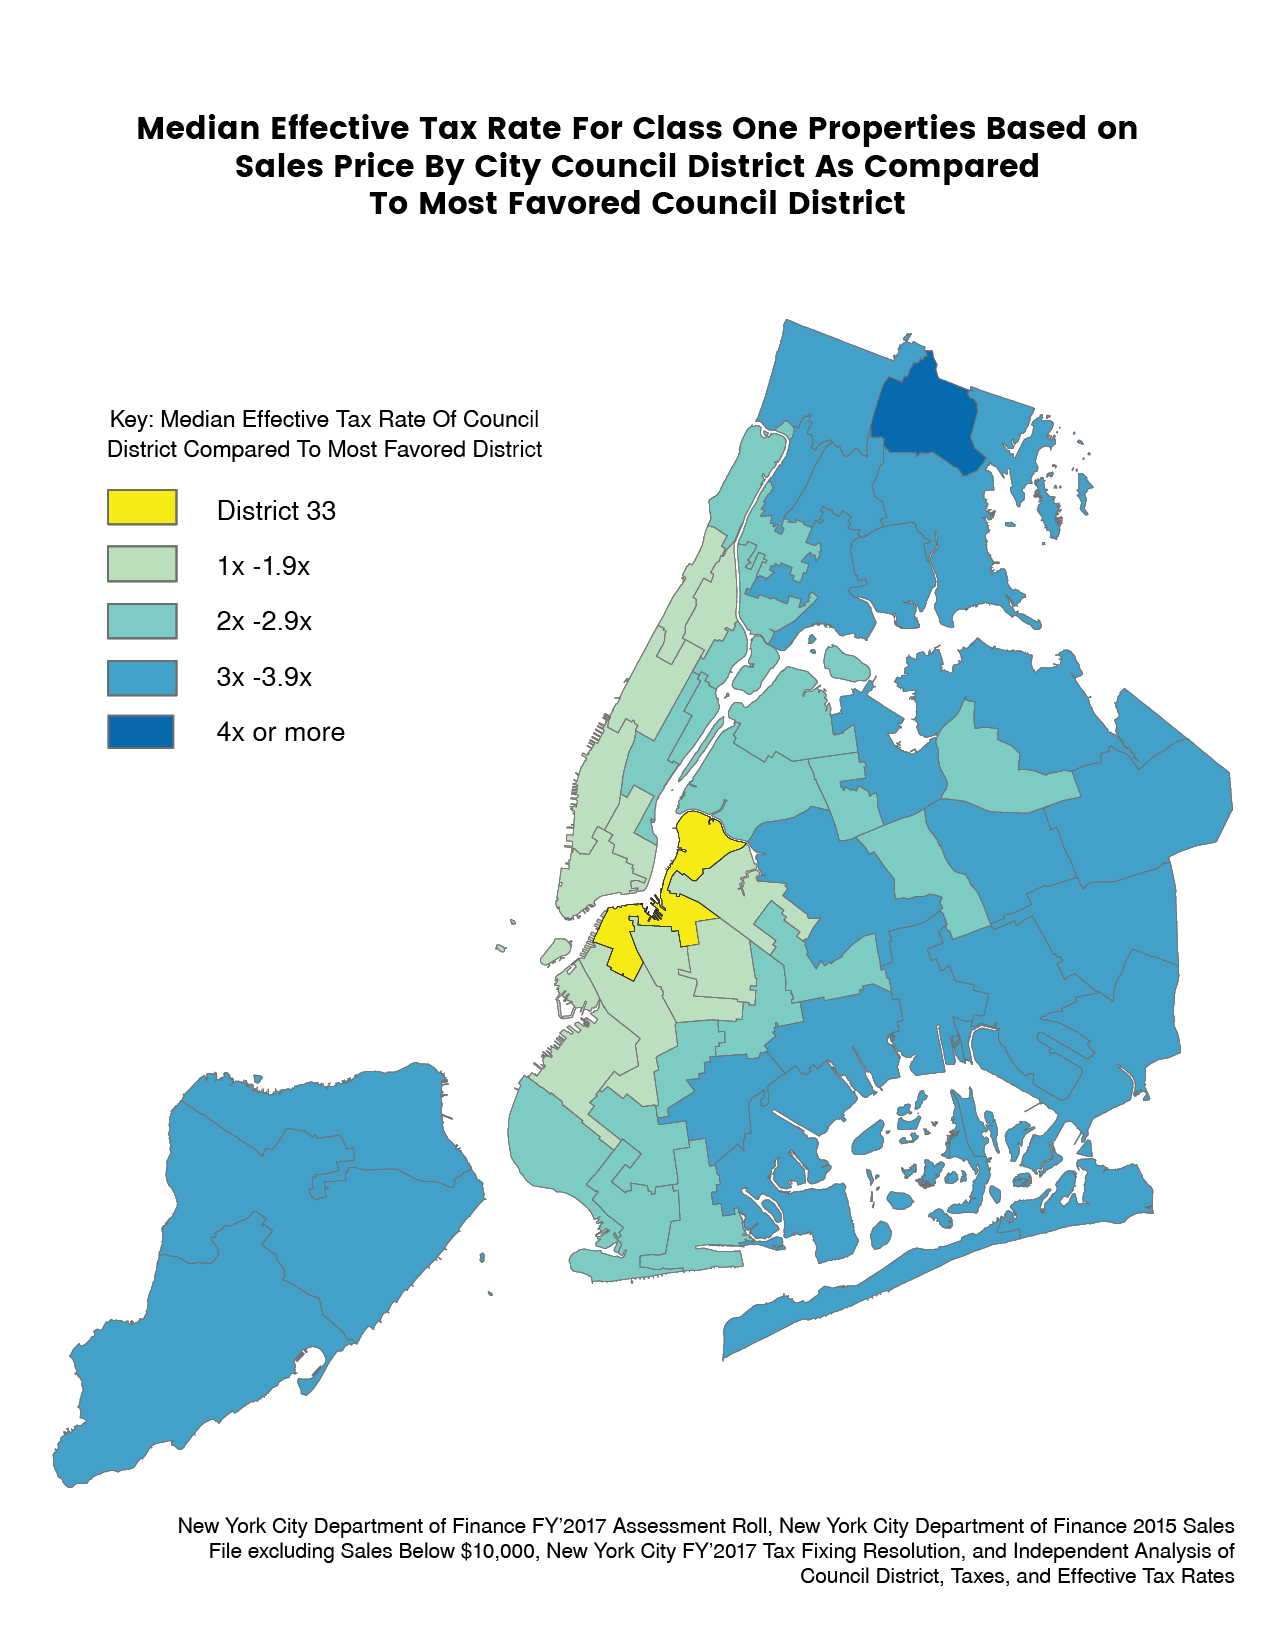
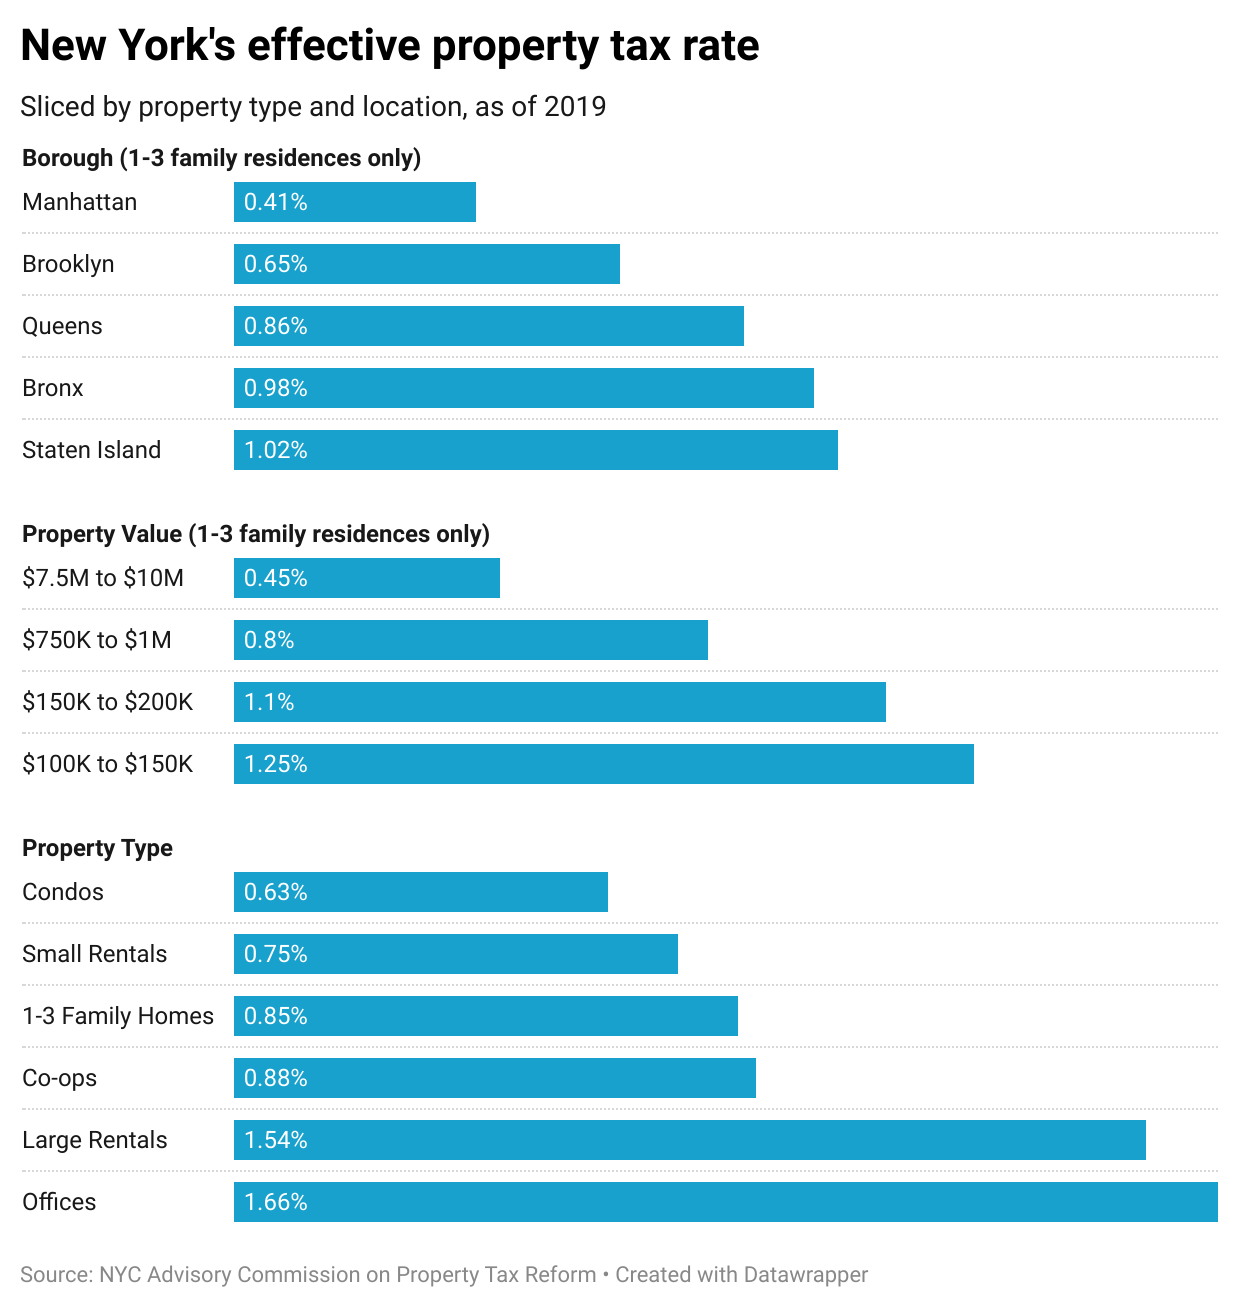
New York City divides real property into four main classes. For homeowners, the two classes that matter most are Class 1 and Class 2. Class 1 covers owner-occupied residential properties with one to three units. Class 2 covers condos, co-ops, and rental buildings with four or more units. The ratio of assessed value to market value differs between these classes, and that difference is where most confusion starts. Class 1 properties are assessed at 6 percent of market value. This cap was established under the property tax reform of 1981, and it is what keeps taxes on small owner-occupied homes comparatively lower than they would otherwise be. Class 2 properties are assessed at a much higher percentage of market value. A condo in Manhattan and a townhouse in Brooklyn with similar market values can end up with very different tax bills simply because of how they are classified. I once had a client who bought a two-unit house in Staten Island and received a bill that was nearly double what the previous owner was paying. The issue was not inflation or a reassessment. The previous owner had leased out the second unit for years, and the building had been improperly classified as Class 2 by the department. Correcting that required filing an HPD registration and then initiating an assessment change with the NYC Department of Finance. It took about fourteen months and roughly nine hundred dollars in administrative costs to resolve.
How Your Assessment Is Calculated
The assessed value on your bill is not simply the market value of your home. It is derived from the market value multiplied by the assessment ratio for your class. For Class 1, the formula is assessed value equal to market value times 0.06. The tax itself is then calculated by applying the residential tax rate to that assessed value. The residential rate for 2025 is approximately 10.927213 mils, which means you pay about ten dollars and ninety-three cents in tax for every thousand dollars of assessed value. Here is a practical example. Say your home has a market value of eight hundred thousand dollars and it is classified as Class 1. Your assessed value would be forty-eight thousand dollars. Multiply that by the residential rate and your annual property tax comes to roughly five thousand two hundred forty-six dollars. If that same property were assessed at market value without the Class 1 cap, your tax would be close to eighty-seven thousand dollars. The classification difference is everything. The catch is that the department does not update market values every year. Assessments for Class 1 properties are tied to a mass appraisal cycle that occurs every few years. Between cycles, your assessed value may stay flat even if your home appreciates significantly. That is why two adjacent houses can have dramatically different assessed values if they were last assessed in different years.
Get the Full Details
Common Exemptions and What They Actually Do
Homeowners in NYC have access to several exemptions, but the most impactful ones come with strict eligibility requirements and income caps that change annually. The Basic STAR exemption reduces the taxable assessed value for owner-occupied primary residences. For the 2025 tax year, theBasic STAR exemption amount is approximately one hundred thousand dollars, but you must meet income thresholds to qualify. If your modified adjusted gross income exceeds the limit, you do not receive the exemption regardless of how long you have owned the home. There is also the Enhanced STAR exemption for seniors age sixty-two and older. This provides a larger exemption amount than Basic STAR, and the income limits are higher as well. The application process is completely separate from your tax bill. You must file Form SC100 with the state Department of Taxation and Finance. Missing the April 1 deadline means you wait until the following year to receive any benefit. Homeowners should also know about the STAR Phase-in exemption. If your property value has increased since your last assessment, you may be able to freeze your taxable assessed value at the lower amount for a period of time. This is not automatic. You need to verify whether your assessor's office has applied the phase-in correctly when they issued your latest bill. I have seen several cases where the phase-in was miscalculated because the department used the wrong base year value.
When to Challenge Your Assessment
If your tax bill looks wrong, the first step is not to file an appeal. It is to pull your property record from the NYC Department of Finance website and compare it against what you know about your home. The online Property Information System contains your tax class, assessed value history, exemption status, and the last sale price. Cross-reference all of that before assuming anything is incorrect. Once you have reviewed the record, you can file an appeal using the annual Supplemental Assessment Review Committee or SARC process. The window is typically thirty days after your bill is issued. Documentation matters more than emotion. Bring recent comparable sales in your neighborhood, a current appraisal if you have one, and photos showing any condition issues that would lower value. Without supporting evidence, the committee will likely uphold the existing assessment. If SARC denies your appeal, you can take the case to the State Board of Real Property Services. This is a formal hearing process and it requires more preparation. You will need witness testimony or an expert appraisal, and the timeline extends several months. For most homeowners, the cost of pursuing this route outweighs the potential tax savings unless the assessment error is substantial.
Pitfalls That Cost People Money
The most common mistake I see is homeowners assuming their tax bill will decrease when property values rise. That is backwards. When your home's market value increases, your assessed value may increase as well, and your tax bill goes up. The Class 1 cap protects you somewhat, but it does not prevent increases during reassessment cycles. If you refinanced recently and your home appraised for a high value, do not expect a lower tax bill. Expect the opposite. Another frequent issue involves abatement programs that homeowners apply for without understanding the trade-offs. Some abatements reduce your current tax liability but create a recapture obligation if you sell the property within a certain period. The NYCHA and HUD-affiliated programs are examples. The reduction can look attractive on paper, but the clawback clause can wipe out the benefit if you sell within five to seven years depending on the specific program. I handled a case in Brooklyn where a homeowner accepted a tax abatement to stay current on payments. Three years later, the property was sold as part of a divorce settlement. The recapture amount came to over fourteen thousand dollars, and neither party had anticipated it. The transaction had to be renegotiated because the seller could not cover the unexpected liability from the escrow proceeds.
What the System Does Not Do Well
The NYC property tax system is transparent about its formulas but opaque about its internal valuation methods. The department publishes the assessment ratios and the tax rates, but it does not publish the comparable sales data it uses to determine market values. This means you cannot independently verify whether your assessment is accurate. You can only challenge it, and the burden of proof is on you. The department also processes a high volume of applications with limited staffing. SARC hearings are brief, often lasting only a few minutes per property. The committee members are volunteers who review cases inconsistently across the five boroughs. Manhattan appeals tend to move faster and receive more thorough review than those in the outer boroughs. This is not documented anywhere officially, but anyone who has filed multiple appeals will notice the pattern. The system also struggles with co-op and condo assessments. The tax is levied on the cooperative corporation or condominium association as a whole, and then each unit owner receives an individual tax bill based on their ownership percentage. Disputes about how the total assessment is allocated among units are extremely difficult to resolve. There is no formal mechanism for a unit owner to challenge the aggregate assessment, and the unit-level breakdown is usually taken as given during individual appeals.
Practical Steps to Stay Current
Set a calendar reminder for late April each year to check your exemption status and income thresholds. STAR applications have deadlines, and missing one delays your benefit by an entire fiscal year. Review your bill as soon as it arrives rather than waiting until the payment is due. The earlier you catch an error, the more time you have to file an appeal before the window closes. Maintain a file of your property records, including every assessment notice, exemption approval, and correspondence with the department. Paper trails matter when you are appealing. I have seen claims denied because the homeowner could not produce a previous assessment notice to demonstrate that the current value was inflated compared to the prior year. Digital copies on your phone are useful, but keep physical copies as well. Scanners fail, phones break, and the department sometimes requests original documents during the appeals process. If your tax bill exceeds ten thousand dollars annually, consider hiring a property tax consultant. They charge between five hundred and two thousand dollars depending on the complexity of your case, but they understand the filing procedures and the typical committee response patterns. For straightforward cases with bills under five thousand dollars, self-representation is usually adequate. The savings from a correct appeal often far exceed the cost of professional help, but the math only works if the error is significant enough to justify the expense.