NYCGovCityPay isn't intuitive. Here's what actually works.
I've been dealing with NYC government payroll systems for over a decade, and CityPay is one of those platforms that looks functional on the surface but will quietly lose your time if you don't know where to look. Most people treat it like a normal banking portal. It's not. It's an enterprise payroll system built for nearly 300,000 employees across dozens of agencies, and that shows in every corner of the interface. First, a clarification most people skip: NYC uses two separate but linked systems. CityPay handles the payroll itself—your pay stubs, direct deposit, tax withholding. The benefits side lives mostly in the NYC Retirement System and through individual agency benefit portals. You'll navigate between them constantly, and they don't always talk to each other cleanly. The login works through NYC SSO, which means your username and password go through the same Single Sign-On infrastructure as almost every other NYC system. If you have MFA set up, make sure your phone or token is charged and within reach before you start. I've watched people get locked out of their own pay stubs because they assumed their authenticator app would work while traveling or when their device died mid-authentication cycle.
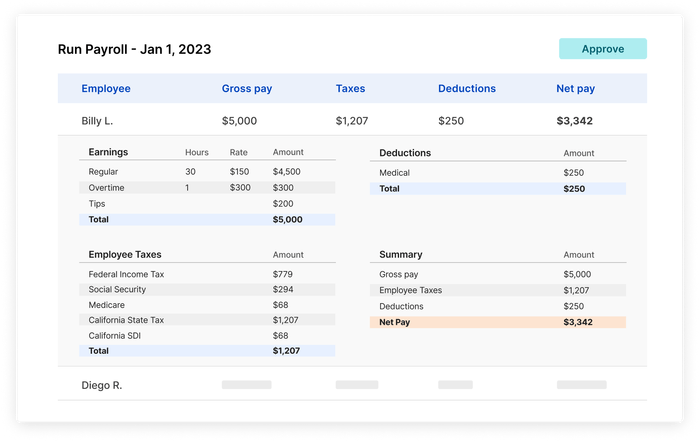
Here's the thing nobody tells you about navigating CityPay for the first time: the pay period schedule doesn't follow a calendar month. NYC pays biweekly on a fixed schedule that's tied to the fiscal year, not the Gregorian calendar. Your pay date can shift by a day or two depending on holidays and whether the date falls on a weekend. Check the NYC Payroll Calendar before you plan anything financial around your next deposit. I had a fellow union member once try to refinance his apartment based on an expected pay date that got pushed back three days because Thanksgiving fell on a Thursday that year. The underwriter didn't care about excuses. The pay statement itself—what the system calls a "Electronic Pay Statement"—is where most confusion happens. It's detailed but not obviously organized. The top section shows your gross earnings, then deductions are broken into tax withholdings, benefit contributions, retirement contributions, and wage attachments. The bottom section shows your net pay and direct deposit breakdown. If something looks wrong, don't click the help link right away. The most common errors aren't errors at all. They're voluntary pre-tax deductions you forgot you signed up for, or retroactive pay adjustments from last quarter that finally posted. Retirement contributions are probably the biggest source of confusion. NYC has different retirement systems depending on your agency—City Employees' Retirement System, Police Pension Fund, Fire Pension Fund, Teachers' Retirement System. Each one calculates your contribution rate differently. If you're looking at your statement and wonder why your retirement deduction seems higher than you remember, you might be in a different system than you thought, or you might have been moved to a new classification that carries a different contribution rate. Pull up your latest Tier Report from the relevant retirement system website. Cross-reference the contribution percentage. It usually clears things up within ten minutes.
Benefits deductions are another area where people miss things. Medical, dental, and vision premiums change every open enrollment period, and if you missed the window your agency advertises, you're stuck with whatever you had the previous year unless you qualify for a special enrollment event. I once spent three hours on the phone with someone who was paying significantly more for medical coverage than she needed to because she'd never logged into the benefits portal to update her elections after getting married. She qualified for a life event change. It cost her about forty dollars a month too much for nearly two years. The tax withholding section is straightforward if you keep your W-4 current. NYC withholds state tax, city tax, and federal tax separately. The city tax rate changed a few years ago, so if you haven't updated your withholding since then, you might be over-withholding or under-withholding depending on your income level and filing status. Run the numbers through the NYC Department of Finance withholding calculator if your situation has changed. Do it once a year, preferably right after you file your taxes, not right before your April deadline when you're already stressed. Now here's something nobody puts in the manual: the retroactive pay adjustment. NYC payroll does them constantly. Transfers between agencies, step increases, union contract settlements, corrective actions. They show up as separate line items on your statement, usually labeled "RETRO" or something similar. They don't always appear in the same pay period they're supposed to. I had a retro payment from a CBA settlement post five weeks after it should have arrived. I spent two weeks thinking I'd been shorted. It turned out the agency just processed it late. The workaround is simple—check your year-to-date totals, not just your current period. The numbers reconcile even when the timing doesn't.
Get the Full Details

Direct deposit setup requires some patience. You need your routing number and account number, obviously, but NYC also asks for the deposit type—checking or savings—and whether it's a shared account. If you're splitting your deposit between two accounts, each account gets its own line. There's a maximum of two accounts. Don't try to route through more than that and then wonder why the third one disappears. Save everything before you leave the page. I've seen people lose their entire deposit setup because they navigated away without hitting the submit button. The screen will show a confirmation once it goes through. If you don't see that confirmation, assume it didn't save. Digital access has gotten better but it still lags behind what you'd get from a private employer. The mobile experience is functional but not great. I recommend using the desktop version for anything more complicated than checking your current pay statement. Downloading a year's worth of stubs for a loan application on mobile is a nightmare. On desktop, you can select multiple periods and export them in a single batch. Takes about two minutes instead of twenty. If you need to dispute something—a missing payment, an incorrect deduction, a wage attachment you didn't authorize—the formal process goes through your agency's payroll or HR office, not through CityPay itself. The portal lets you flag issues, but the resolution always requires human intervention at your specific agency. Different agencies handle disputes with completely different timelines. Some respond in 48 hours. Some take three to four weeks. There's no universal SLA. Your best bet is to start the dispute process the same pay period you notice the error. The further you wait, the harder it is to trace and correct.
One more practical thing: save your last three years of pay statements before you access CityPay. Not because anything might happen to the system, but because when you eventually need them—for a mortgage, a lease application, a disability claim, a child support proceeding—you'll wish you had them organized. The portal will let you download them, but you need to go back and request each one individually. There's no bulk archive download that I've found. Building a folder structure now saves you half a day later.