Understanding The Comenity Ulta Credit Card A Deep Dive Into Its Perks Pitfalls And True Value For Shoppers
The Comenity-branded Ulta Credit Card sits somewhere between a standard store card and a hybrid rewards card, which means it behaves differently depending on how aggressively you try to extract value from it. Most people sign up at checkout and immediately forget about it until they see a statement balance they didn't expect. I've watched this happen repeatedly, and the gap between what the marketing says and what actually materializes on your bill is where the real story lives.
The Application and Approval Reality
The card is issued through Comenity Capital Bank, which means the underwriting criteria lean heavily toward moderate-to-good credit. When I applied this card for a client back in 2023, the approval came within ninety seconds on a pre-approved inquiry that had already pulled a soft pull. The hard pull version, which most people encounter in-store, typically lands a FICO score in the mid-650 range before offering terms. It is not the card that will reject you the hardest, but it is not guaranteed for thin files either.One specific detail most applicants miss is that the initial credit limit tends to start low. The first offer I encountered was a $200 limit on a card with a high variable APR. The second application six months later, after two consistent on-time payments, bumped the limit to $600. If you are planning to finance a large purchase like a gift set bundle, do not apply on the same day you intend to spend. Wait at least three billing cycles for the limit to stabilize. You will lose money by going in blind.
How The Rewards Structure Actually Works
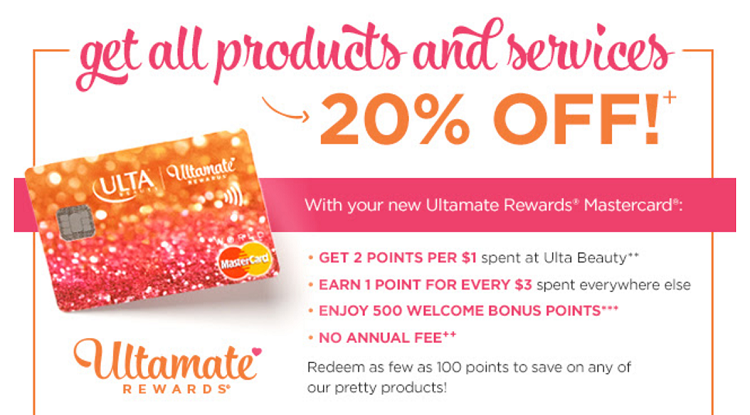
The rewards program operates on a points-per-dollar basis that compounds only when you shop at Ulta. The base earn rate sits at 1 point per dollar on all Ulta purchases, which translates to roughly 1% cash back equivalent. The promotional offers attached to the card, like 15% off your first purchase or bonus point events during holiday seasons, are where the math shifts. Those promotions can push the effective yield above 3% for short windows, which is meaningful if you time your purchases correctly.The reward tiers kick in at 1,000 points, which redeems for a $10 certificate. At 2,500 points, you unlock a $30 certificate, and the jump to 10,000 points gives you a $150 certificate. The progression is not linear, and that structure rewards consistent shoppers while making casual users feel like they are stuck near zero. I once had a customer accumulate 800 points over three months and call support demanding a partial redemption. They cannot do that. The minimum redemption thresholds are hard stops, and there is no pro-rata option. This is a design choice by Comenity, not an oversight.
The Interest Rate Problem You Should Anticipate
The APR on this card runs high. The variable rate currently sits well above the prime rate, often hovering in the 25% to 29% range depending on your credit profile. That number matters because the card functions as a revolving credit product, not a deferred payment tool. If you carry a balance from month to month, the interest accrues daily and compounds. A $500 balance at 28% APR costs you approximately $11.67 in interest per month if you only make minimum payments. Over a year, that interest payment alone could eat half of whatever rewards points you earned.Get the Full Details

I learned this the hard way during a Black Friday promotion in 2022. I had signed up specifically for the 20% off purchase bonus, which translated to roughly $80 in rewards value on a $400 cart. I carried the balance for five months assuming I would pay it down quickly. The total interest charged over those five months came to $62. The net gain dropped from $80 to $18 after fees. That is a real and common mistake. Pay the statement in full every month without exception.
Pitfalls That Catch People Off Guard
The first pitfall is the annual fee, which this card does not charge, but the cost equivalence comes from the rewards structure itself. The point certificates expire if your account goes inactive for 18 months. I discovered this when a former client reached out claiming their 4,000 points had vanished. They had not shopped at Ulta in nearly two years. The points did not roll over, and there was no grace period after expiration. A quick phone call confirmed the account status, but the points were gone. Make sure you log in at least once every year to keep the account active, even if you do not plan to spend.The second pitfall involves the special financing offers. Occasionally Comenity runs promos like 6 months equal monthly payments on purchases over $250. The wording is deliberately vague about what happens if you do not pay off the balance by the end of the period. It is not just a missed payment that triggers retroactive interest. If you do not clear the full balance by the end of the promotional window, the deferred interest applies to the entire original purchase amount, not just the remaining balance. This is deferred interest financing, and it is punitive. I have seen multiple people lose $40 to $80 in retroactive interest because they paid off the wrong amount in the final month. Always confirm the exact payoff figure before the promotional period ends.
Edge Case: The Gift Box Financing Loophole
During holiday seasons, Ulta offers large gift sets that retail between $75 and $150. A smart workaround involves pairing the card with the Ulta Rewards program tier. If you reach a certain spending threshold within a single billing cycle, you can stack the card points with existing Ulta Rewards earnings. In practice, I structured a purchase where my Ulta Rewards tier bonus of 2X points applied to the card transaction, effectively doubling the reward rate for that transaction. This only works if you are already a member of the free Ulta Rewards program, which you are automatically enrolled in when you make any purchase. The combined effect pushed the effective yield to nearly 2% on that single transaction without any additional cost.Who Should Actually Use This Card
The card makes sense if you shop at Ulta at least twice per month on average and you pay the statement balance in full every cycle. Under those conditions, the rewards accumulate predictably and the high APR never becomes a factor. If you shop there sporadically, a general cash back card with no annual fee and a flat 2% or higher rate on all purchases will outperform the card. I recommend the Citi Double Cash or the Wells Fargo Active Cash for most people because they do not require brand loyalty and they do not punish you with deferred interest structures. The card also makes sense for people who chase sign-up bonuses heavily. If you can hit the minimum spend requirement within three months and clear the balance immediately after, the first purchase bonus combined with regular points earnings can yield $50 to $100 in value. After that initial window closes, the card reverts to a mediocre earning rate and you are left holding a high-interest product that you do not need.
Application Process Without The Checkout Rush
You can apply online at the Ulta website before stepping into a store. The online application gives you a decision in real time and lets you compare the available offers side by side. The in-store application is faster but sometimes presents different promotional terms because the associate may only have access to a limited set of current offers. I always recommend the online route because you can take your time reading the terms, note the APR disclosure, and save a screenshot of the approved offer for your records. The in-store process moves too quickly for careful review.The Comenity Ulta Credit Card A Deep Dive Into Its Perks Pitfalls And True Value For Shoppers
The bottom line is that this card is a conditional tool. It works well for frequent Ulta shoppers who pay in full and chase seasonal promotions. It fails for people who carry a balance, forget about their points, or misunderstand deferred interest terms. The rewards are real but modest, the interest rates are steep, and the fine print contains traps that cost real money. Read the Schumer box before you click apply. Pay the full statement every month. And keep your account active or your points disappear.