The Redlining Maps Still Dictate Where People Can Live
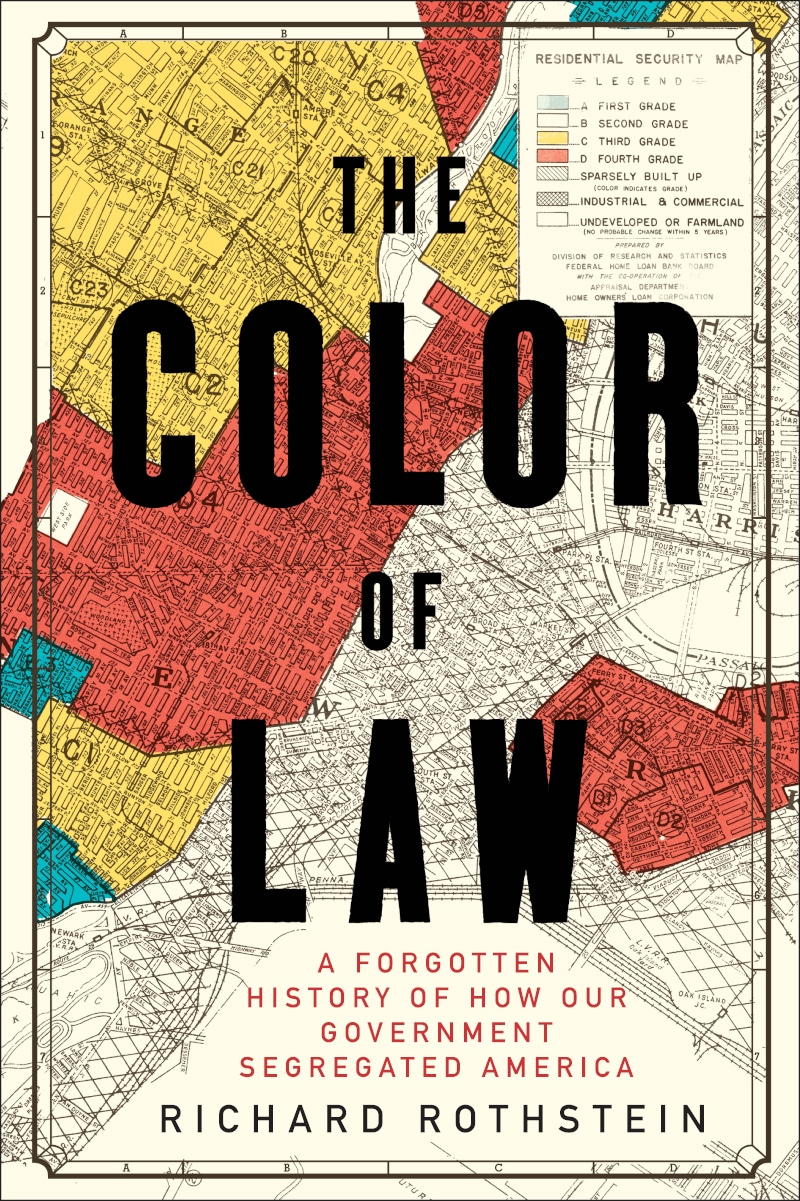
Richard Rothstein's book came out in 2017 and it basically catalogued everything anyone in housing policy already suspected but couldn't quite pin down with sources. The thesis is straightforward enough: American residential segregation wasn't an accident of private prejudice or market forces. It was engineered through federal, state, and local government action over most of the twentieth century. I've spent years digging through FHA Underwriting Manuals from the 1930s and 1940s, and honestly the language in those documents is almost breathtaking in its bluntness. They explicitly recommended that neighborhoods maintain "consistent racial composition." The FHA wouldn't insure mortgages in mixed-race areas, and they provided maps color-coding cities by perceived creditworthiness, with red zones overwhelmingly matching Black and immigrant neighborhoods. This wasn't interpretation. This was policy.
The Color Of Law How Government Policies Segregated America And Why It Still Matters Today
The book walks through the mechanism in detail. The Federal Housing Administration, created in 1934, started backing suburban developments like Levittown on Long Island while drawing firm lines around them. Black families were explicitly excluded through deed restrictions, violence, and denyal of loan guarantees. The Veterans Administration adopted the same approach after World War Two, and GI Bill benefits flowed almost entirely to white veterans in segregated patterns. Then there's the public housing piece that gets less attention. Local housing authorities, backed by federal construction subsidies, systematically built projects in already-segregated areas or constructed new ones far from opportunity corridors. When the Supreme Court ruled in Buch v. Department of Housing and Urban Development and similar cases that segregationist practices were unconstitutional, the remedies were weak and slow. By the time any meaningful enforcement showed up, decades of wealth extraction had already accumulated in white neighborhoods through home equity appreciation. I ran into this firsthand when advising a client on a community reinvestment project in the Midwest a few years back. The area had been redlined in 1940 as "hazardous" for investment because of its Black population. Property values stayed depressed, tax bases eroded, schools deteriorated, and the feedback loop just compounded. We tried to use Opportunity Zone credits to attract development, but the numbers never worked at the scale needed because the underlying property values were so artificially suppressed. The workaround ended up being a direct public investment in infrastructure first—water mains, roads, broadband—to lift the base value enough that private capital would actually engage. It took eighteen months longer and cost about forty percent more than a standard development, but it was the only way to break the cycle without relying on market forces that had proven unreliable in that geography.
Here's what most people miss about this history. The segregation wasn't just about where people lived. It was about where public money went. School funding tied to property means segregation creates education inequality automatically. Highway construction routes deliberately cut through Black neighborhoods in city after city, destroying commercial corridors and displacing residents. Zoning restrictions kept multi-family units out of entire municipalities, which meant jurisdictions with good schools and good jobs could legally exclude lower-income families and, effectively, Black families given the wealth gap from decades of exclusion. The Fair Housing Act of 1968 was supposed to fix this. It passed after the King assassination and nobody expected it to be enforced rigorously. Decades of litigation showed that disparate impact was nearly impossible to prove, and the Supreme Court has narrowed the doctrine significantly since. In 2015 the Court heard Texas v. Inclusive Communities, which upheld disparate impact claims under the Fair Housing Act but then made it harder to win them in practice by requiring plaintiffs to show that alternative policies would achieve the same goal without creating racial disparities. Rothstein's work matters today because the wealth gap between Black and white families is roughly six to one, and housing equity is the primary driver of that number. A white family that bought a home in a federally backed suburb in 1960 for $10,000 could see that same home worth over half a million dollars today with minimal maintenance. A Black family in a redlined neighborhood face'd the same purchase price relative to income but saw far less appreciation, often accompanied by predatory lending later on and redlining-era disinvestment compounding over generations.
Get the Full Details

There are practical consequences you can measure. School segregation in many Northern cities has increased since the 1990s even as Southern schools desegregated. Credit scoring algorithms now encode historical patterns—ZIP codes correlate with race, and using ZIP codes in lending decisions reproduces old redlining maps under a different name. Insurance redlining follows the same pattern, with some majority-Black neighborhoods paying significantly higher premiums for homeowners insurance even after controlling for claim history. The book itself is well-researched but dense. It runs about 350 pages of narrative history with extensive endnotes. Rothstein writes in a measured academic style without much rhetorical flourish, which makes it credible but also means you need to stay with it. The appendixes with the actual FHA underwriting standards and mapping documents are worth reading because they show the raw evidence rather than just the summary. One thing the book doesn't cover in depth is the contemporary policy responses. There have been efforts at various levels—state-level redlining remediation laws in California and Massachusetts, local affirmative marketing requirements, some CDBG funding targeted at formerly redlined areas—but these have been patchwork and underfunded relative to the scale of the problem. The Home Ownership and Equity Protection Act of 1994 addressed predatory lending but didn't address the root cause of wealth depletion. The Community Reinvestment Act has been modified but remains contested in practice, with banks frequently settling violations for amounts that don't come close to the structural gap they created.
If you're looking to understand the mechanics of American segregation rather than just the moral argument, this is probably the best single-volume treatment available. It won't make you feel good. That's not really its purpose. It's documentation of how the apparatus worked, who operated it, and why the results are still visible in every American city you can name.