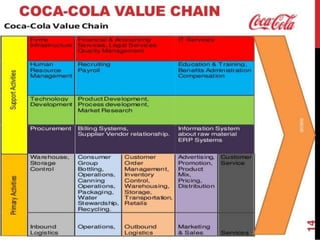
Understanding How Coca-Cola Moves From Syrup to Shelf
The Coca-Cola value chain is one of those business case studies you see everywhere, but the actual mechanics are worth understanding beyond the surface level. The company operates what's essentially two separate supply networks: the syrup production side and the bottled distribution side. At the core, Coca-Cola makes syrup at centralized facilities. They don't bottle most of their own drinks. Instead, they sell concentrate to bottling partners who mix it with water, carbonation, and packaging materials. That's the franchise model in a nutshell. The syrup goes to over 200 independent bottling operations across roughly 200 countries. Each bottler buys concentrate or syrup from Coca-Cola and handles the rest themselves. This arrangement shifts massive capital expenditure away from the parent company while keeping brand control tight. I spent time mapping out this chain for a supply chain consulting project a few years back. The complexity hits you fast. You're looking at cane sugar sourcing from Brazil, corn syrup from Midwest America, aluminum from suppliers in three continents, and glass from facilities that predate modern environmental regulations. Tracking COGS across that many tiers without accurate transfer pricing gets messy. I ended up building a custom spreadsheet model that tracked sugar and sweetener cost pass-throughs by region, which took about 40 hours of manual data entry but cut down the reporting cycle from a week to two days going forward.
Sourcing and Procurement
Coca-Cola sources ingredients at massive scale. The company procures billions of pounds of sugar annually. In 2022 alone, they used roughly 1.4 billion pounds of sugar in the United States. Corn high-fructose syrup is the other major sweetener, especially in products marketed in North America where sugar-sweetened beverages face heavier regulation and tax scrutiny. Some bottling markets have shifted heavily toward alternative sweeteners like stevia and monk fruit, driven by changing consumer preferences and public health policy. Water is the primary ingredient by volume. The company treats roughly 2.3 billion hectoliters of water annually across its global operations. Water sourcing strategy matters because bottling plants need consistent quality regardless of local municipal water supply. Many bottlers maintain on-site reverse osmosis and filtration systems. That adds operational cost but prevents flavor variation between regions. Other inputs include packaging materials, which represent a significant cost driver. Aluminum cans and PET bottles account for nearly 60 percent of total material costs in many markets. Scrap aluminum prices directly affect per-unit packaging expenses. The company has been pushing lightweighting initiatives, reducing can weight by nearly 20 percent since 2010. That translates to meaningful savings at scale but requires supplier renegotiation and retooling on the packaging line.
Operations and Production
Concentrate production happens at company-owned manufacturing facilities. These are highly automated environments. The blending process for syrup is precise because flavor consistency is critical. Any variance in syrup composition shows up immediately in taste tests and consumer complaints. Coca-Cola maintains tight quality control protocols with batch testing at multiple stages. Bottling is where the decentralized model becomes apparent. The company operates only a handful of its own bottling facilities directly. Most production occurs through contract bottlers. This means Coca-Cola manages brand standards and syrup recipes but doesn't own the capital equipment at most production points. The bottling partners absorb depreciation, maintenance, and labor costs. It's a capital-light strategy for the parent company but requires ongoing relationship management. I've seen what happens when a major bottler faces production downtime. During a 2019 equipment failure at a Southeast Asian bottling plant, Coca-Cola's regional supply team had to reroute finished goods from a neighboring country within 48 hours. The backup logistics cost them an estimated 8 percent above normal freight expenses that quarter, but the brand stockouts were contained to a single metropolitan area instead of spreading region-wide. That kind of contingency planning separates adequate supply chains from resilient ones.
Get the Full Details

Distribution and Logistics
The distribution network relies heavily on third-party logistics providers. Coca-Cola moves products through a mix of direct store delivery, wholesale distributors, and retail partnerships. The direct delivery model gives the company tighter control over shelf presence and inventory turnover. Retailers like Walmart and McDonald's receive shipments directly from Coca-Cola trucks rather than going through intermediate distributors. Route-to-market strategies vary significantly by region. In developed markets with strong retail infrastructure, the company maintains extensive direct delivery routes. In emerging markets with fragmented retail landscapes, wholesale distributors handle the last mile. The company uses route optimization software to manage delivery scheduling across thousands of stops daily. Average fleet utilization rates in mature markets hover around 85 to 90 percent. Below that threshold, per-delivery costs climb noticeably. Reverse logistics for packaging is another layer. The company collects aluminum cans for recycling through various programs. In markets with deposit-return schemes, the logistics work backward from consumer drop-off points. Empty container return rates in Germany, for example, exceed 90 percent. Those returned containers become feedstock for new packaging, reducing virgin material procurement costs. The system only works when collection infrastructure exists, which limits applicability in developing economies.
Marketing and Sales
Coca-Cola's marketing spend is enormous. The company invested approximately $4.6 billion in marketing and advertising during fiscal year 2023. That budget covers global campaigns, local market activations, sponsorships, and digital advertising. Brand equity is the primary asset being built, and the company tracks share of voice against competitors like PepsiCo closely. The sales force operates through a geographic structure. Regional sales teams manage retailer relationships and negotiate shelf space. Trade promotion spend represents another major cost category, often running 3 to 5 percent of net operating revenue. This includes volume discounts, cooperative advertising allowances, and temporary price reductions. The effectiveness of trade spending varies widely by market and retailer. Some accounts respond to simple price incentives. Others require promotional support, merchandising allowances, or exclusive product placement agreements. One thing people don't always consider is the relationship between marketing allocation and bottler economics. The parent company funds national advertising. Local bottlers often carry the cost of trade promotions and point-of-sale materials. That creates tension when a bottler feels marketing isn't pulling its weight at the local level. I've worked with partners who pushed back on promotional commitments because the brand-funded campaigns weren't generating sufficient lift in their specific territory. The resolution usually involves renegotiating co-op advertising splits or adjusting margin structures.
Customer Service and Post-Sales
Post-sale service at this scale focuses on account management rather than product repair or warranty support. Customer service teams handle order fulfillment issues, billing disputes, and quality complaints. The beverage industry has relatively low return rates compared to other consumer goods sectors. Product returns typically relate to damaged goods, near-expiry inventory, or recalled batches. Quality complaint handling is systematic. Reports of off-taste, foreign material, or packaging defects trigger root cause investigation protocols. The severity determines escalation path. Minor complaints get documented and trend-analyzed. Systemic issues like recurring seal failures on a particular bottling line shut down production until resolved. During a packaging defect issue in 2021 involving capping torque inconsistency, the affected bottler pulled roughly 4 million units from distribution. The recall cost was contained because the issue was caught within the first 72 hours of complaints coming in.

Margin Dynamics and Cost Structure
The parent company operates with gross margins typically in the 60 percent range on concentrate sales. That's extremely healthy. Bottling partners run lower margins, usually 15 to 25 percent depending on market conditions and operational efficiency. The split between concentrate margin and bottler margin explains why Coca-Cola's consolidated profitability looks so strong even when volume growth stalls. Petroleum prices affect the entire chain through multiple channels. Fuel costs influence freight expenses. Crude oil prices drive both petroleum-based packaging costs and agricultural input costs for sugar and corn production. A 20 percent spike in diesel prices can erode a bottler's operating margin by 2 to 3 percentage points if not offset through price adjustments. Coca-Cola has pricing power, but it's not unlimited. Consumer sensitivity to price changes limits how much cost can be passed through.
Common Weaknesses in This Model
The franchise bottling model creates coordination challenges. When bottlers operate semi-independently, implementing global sustainability initiatives or digital transformation projects requires consensus across dozens of separate management teams. A centralized rollout of new routing software might work well for one bottler but face resistance from another with legacy systems. The company handles this through mandatory standards and phased adoption timelines, but execution lag is real. Another structural vulnerability is overreliance on sugary beverage demand in mature markets. Consumption of regular Coca-Cola has been declining in the United States for over a decade. The company has diversified into water, tea, coffee, and energy drinks, but those segments carry different margin profiles and competitive dynamics. Revenue growth from non-cola products hasn't fully offset the cola decline. The value chain was built around high-volume, low-cost cola production. Adapting it for lower-volume specialty products requires different manufacturing and distribution approaches. Counterintuitively, vertical integration would likely hurt Coca-Cola's profitability more than help it. Owning bottling operations means absorbing massive fixed costs, labor relations exposure, and capital depreciation. The franchise model outsources those risks while maintaining control through concentrate sales and brand agreements. The real risk isn't lack of integration. It's losing the ability to enforce standards without owning the assets. That tension shows up periodically during market downturns when bottlers struggle to meet performance targets.