Understanding the new credit card charge flow
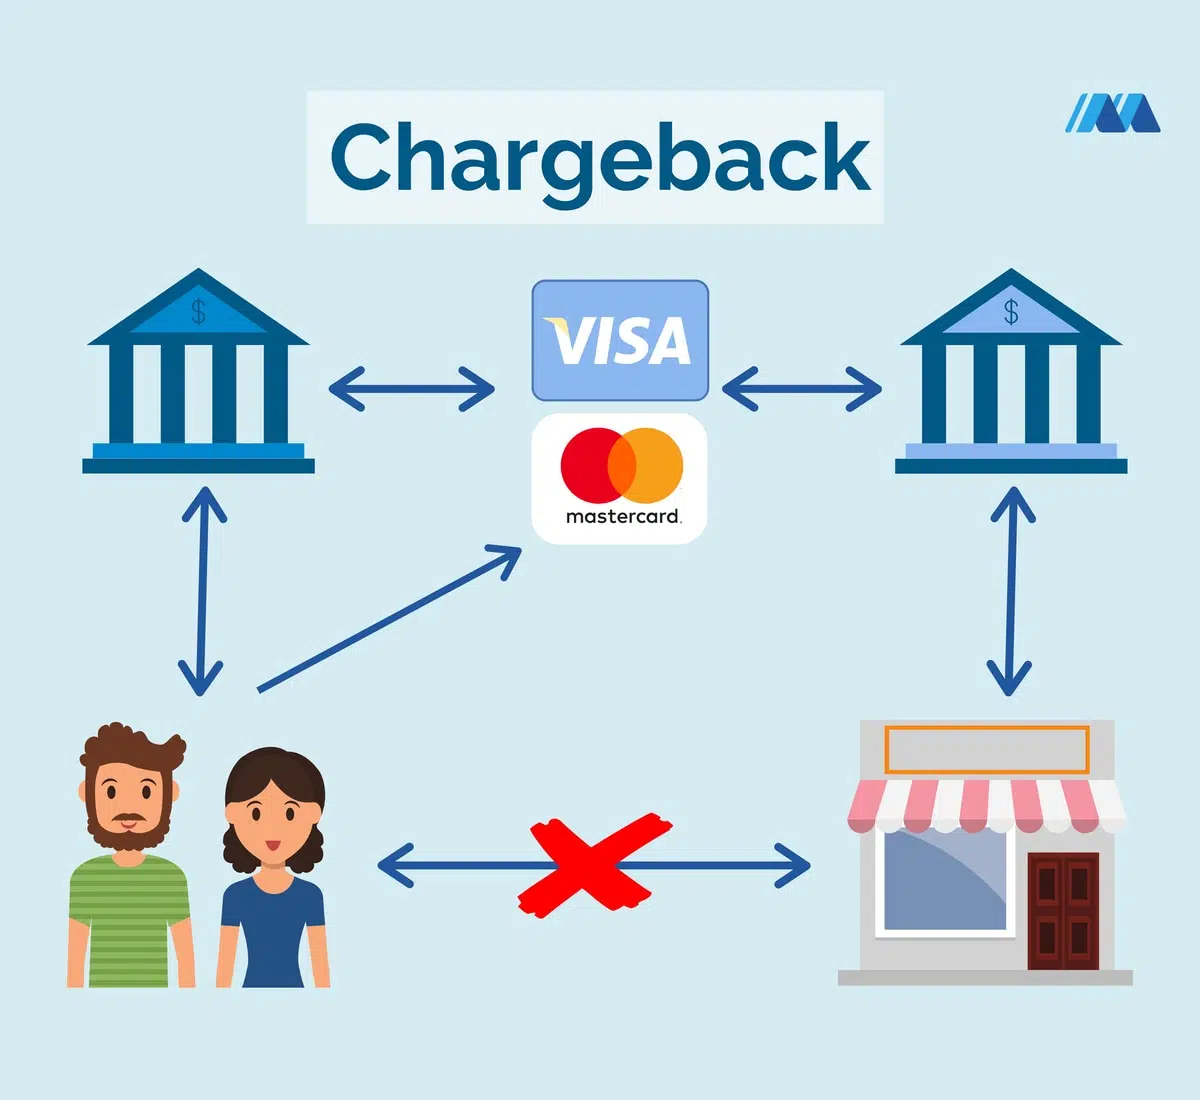
The payment processing industry has been pushing a shift in how merchant transactions get authorized and settled. It is called The Charge On Credit Card Initiative Revolutionizing The Way We Pay, and it matters because the old batch-based authorization model is being replaced by near-real-time charge capture on credit cards at the point of sale. At its core, this initiative moves the credit card authorization and capture steps closer together in time. In the traditional model, a merchant would place a hold on a card at checkout, then settle the batch hours later or at end of day. Under the new charge flow, the transaction gets fully authorized and captured nearly simultaneously through updated payment gateway parameters and issuer-side handling. I first ran into this when a restaurant client was complaining about chargeback rates jumping from 0.8% to 3.2% over a six-month period. The issue was that their payment terminal was still using delayed settlement. By the time batches settled, customers had already forgotten the purchase or disputed it under unfamiliar billing descriptors. Switching to real-time charging dropped their chargeback rate back to under 1% within two billing cycles.
How the process actually works in practice
When a customer taps or inserts their card, the terminal sends an authorization request to the acquiring bank. Under the old system, that auth request created a pending hold but did not finalize the transfer. The merchant had to wait, run a separate settle request, and hope the batch processed cleanly. Now, the terminal sends an authorization combined with a capture flag set to immediate. The funds move within minutes instead of hours. This requires several components to align properly. Your payment gateway needs to support instant capture parameters. Your merchant account must have the merchant category code properly configured so issuers do not block what they see as unusually fast settlement. Your terminal firmware should be current, and your acquiring bank needs to have enabled the new charge flow on their side. I have seen terminals that looked fully updated but were still operating on legacy batch settlement because the gateway merchant ID was misconfigured. The technical switch usually involves changing the transaction type from auth-only to auth-capture in your payment API calls. If you are using a hosted payment page, look for a parameter like capture_method or auto_capture. Set it to true. If you are working with a processor like Stripe, Square, or a traditional acquiring bank, the setting lives somewhere in the checkout configuration. Check with your provider because the exact label varies widely.
Where people mess this up
The biggest problem I see is merchants enabling real-time charging without adjusting their refund workflow. When charges hit instantly, refunds do not automatically reverse the same way. Some processors take up to five business days to return funds to the customer card. If you sell digital goods or services where refund velocity matters, you need to set up automated refund triggers through your dashboard rather than waiting for manual processing. Another trap is descriptor mismatch. Issuers now flag transactions where the authorization amount and the captured amount differ by more than a small threshold. If you add tips, taxes, or adjustment fees after the initial charge, make sure your system sends an amendment request before settlement closes. I had a client who lost $4,200 in disputes over one month because their tip-adjusted charges were being flagged as suspicious by issuer fraud systems. They fixed it by switching to open-loop authorization with tip adjustment, which lets the final amount be modified before capture. There is also the issue of prepaid and debit cards. Real-time charging does not play well with all card types. Prepaid cards often decline if the authorization amount does not match the exact capture amount. Gift cards have similar restrictions. If you accept these payment methods, you will need to keep a fallback to the older batch settlement flow for those specific transactions. Your processor should let you route different card types through different settlement methods, but you have to configure that explicitly.
Get the Full Details
Practical steps to migrate
Start by contacting your acquiring bank or payment processor and asking whether they support the instant auth-capture flow on your merchant account. Get the answer in writing. Then check your gateway documentation for the capture parameter. Update your checkout flow incrementally, starting with low-ticket items, and monitor your dispute rate and successful transaction rate closely. Give it two full billing cycles before declaring success. Make sure your accounting system is ready to handle the timing change. With batch settlement, you could reconcile at end of day. With real-time charging, individual transactions clear throughout the day, which means your reconciliation process needs to match transaction-level data rather than batch totals. Most merchants find that switching to a solution like a real-time ledger feed from their processor cuts reconciliation time from hours to about twenty minutes.
What this does not solve
Real-time charging is not a cure-all. It does not reduce fraud by itself. In fact, some issuers become more aggressive with fraud checks when they see instant capture, because the money moves immediately and cannot be reversed as easily. You still need strong fraud screening tools like AVS, CVV verification, and ideally a machine learning fraud engine. It also does not help if your customer base skews heavily toward regions or card networks with slow settlement infrastructure. Some international card networks and certain regional processors do not fully support instant capture yet. If more than ten percent of your sales come from those sources, the benefit shrinks considerably, and you may be better off keeping the hybrid model with batch settlement for cross-border transactions. The initiative is a real improvement for most domestic merchants, but it requires careful setup and ongoing monitoring. Do not just flip the switch and walk away. Watch your dispute metrics, your refund processing times, and your customer complaints for the first three months. That is where the actual problems show up.