Capital Adequacy Ratios Are a Moving Target That Nobody Actually Monitors in Real Time
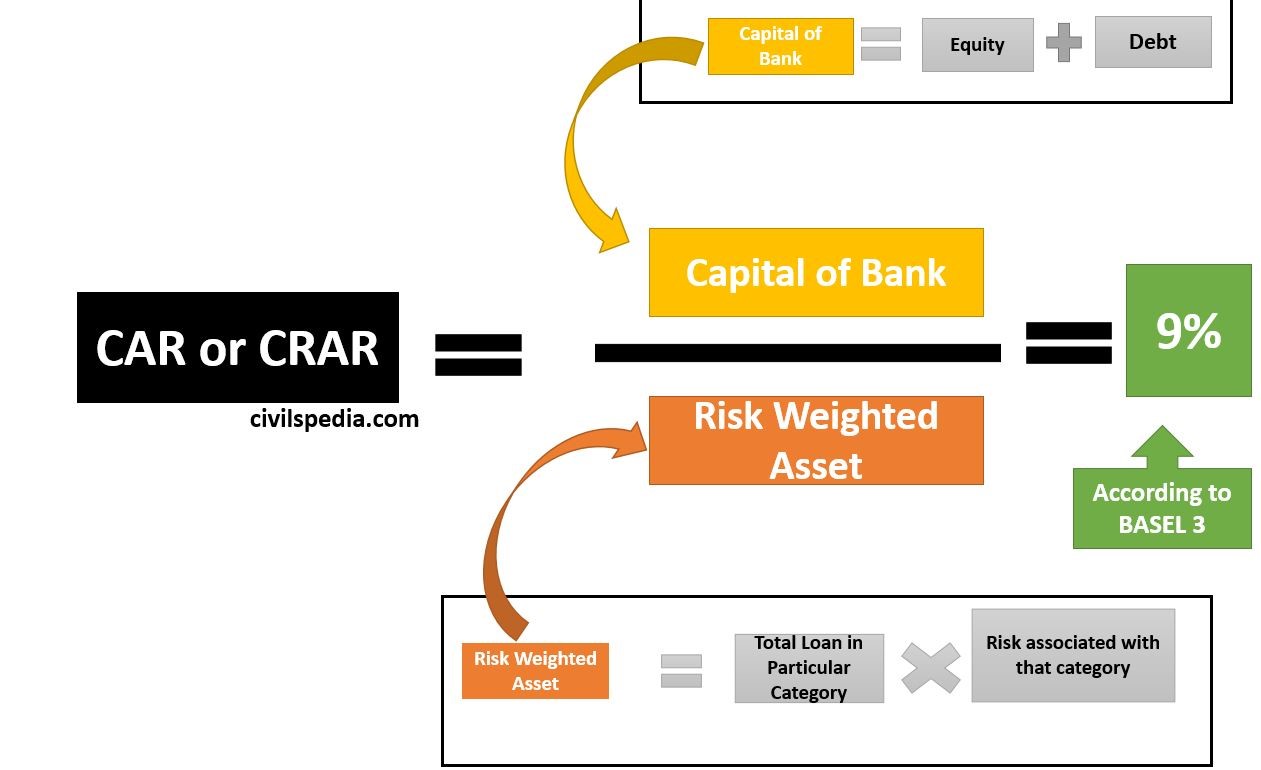
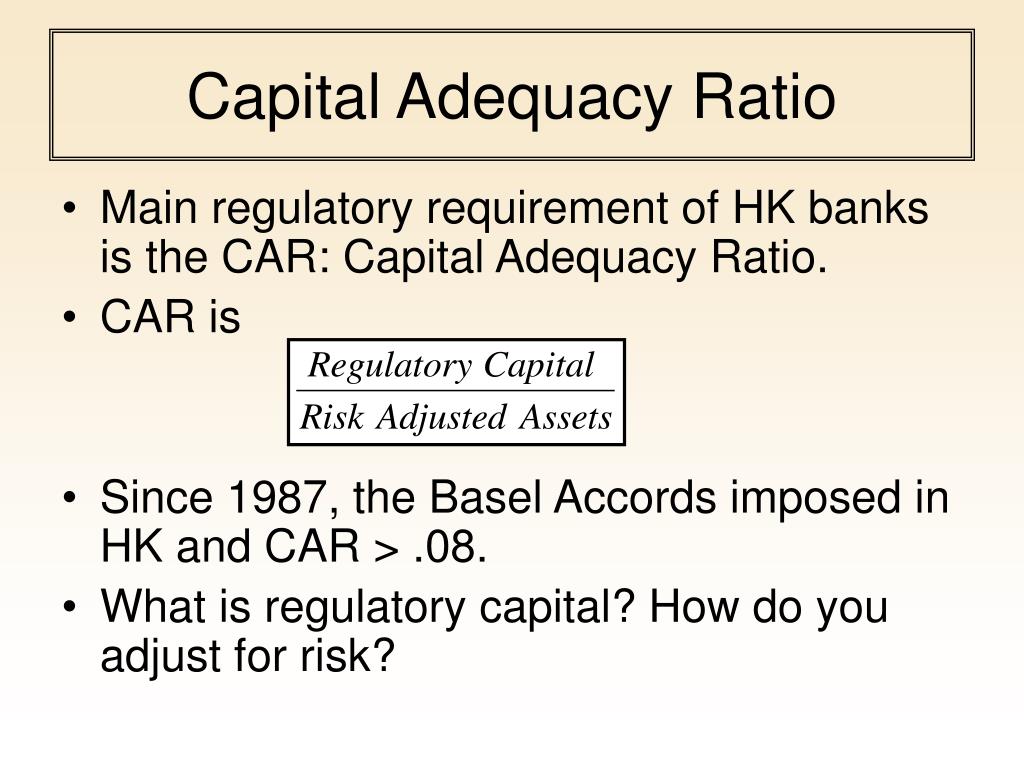
The Capital Adequacy Ratio Wiki A Deep Dive Into Banking Stability Metrics And Regulatory Frameworks isn't really a single thing. It's a collection of overlapping concepts that banks report quarterly, regulators stress-test annually, and nobody actually discusses until something goes wrong. I have spent enough years watching institutions try to keep their numbers above the floor to tell you that the gap between the textbook definition and the actual calculation is where everything falls apart. CAR measures how much capital a bank holds relative to its risk-weighted assets. The core formula divides capital by risk-weighted assets and multiplies by one hundred to get a percentage. Banks are required to hold a minimum amount of this capital to absorb losses. If the ratio drops below regulatory thresholds, regulators can step in and restrict operations. This is the basic shape of it. The details are where people get tripped up.
The Capital Adequacy Ratio Wiki A Deep Dive Into Banking Stability Metrics And Regulatory Frameworks
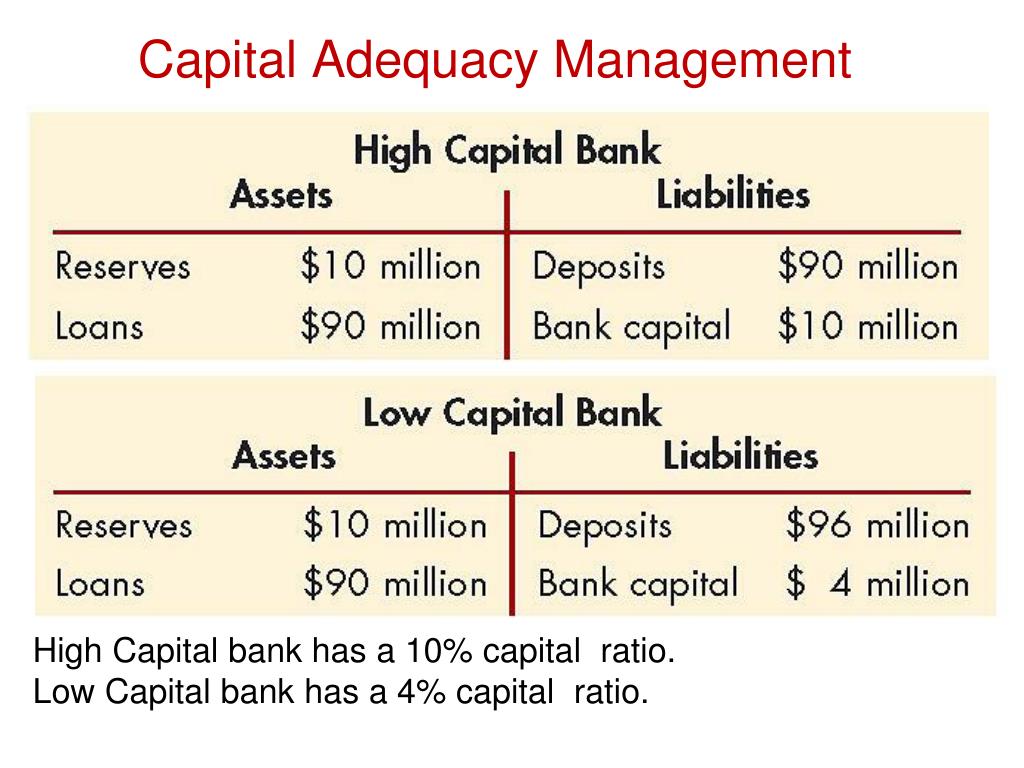
When I started dealing with CAR reporting, the biggest shock was how many line items can quietly shift your risk-weighted assets without anyone noticing until the quarter close. You think you are fine at mid-quarter. Then lease accounting changes, or a derivative valuation adjusts, or a loan gets reclassified into a different risk bucket, and your RWA jumps by a few hundred million overnight. Your CAR drops. Suddenly you are scrambling to figure out whether you need to raise capital or find a workaround before the next reporting cutoff. Capital itself is split into tiers. Common Equity Tier 1 is the highest quality capital. It includes common shares and retained earnings. These are the funds that can absorb losses while the bank continues operating. Tier 1 capital adds additional instruments like preferred shares and certain reserve accounts. Total capital includes Tier 2 as well, which covers things like subordinated debt and general loan loss reserves. Each tier has different absorption characteristics and regulatory constraints. Basel I introduced the concept in the early nineteen-nineties. It was crude. A hundred percent risk weight on residential mortgages, zero on government debt, fifty on corporate loans. It worked well enough for its time but treated every asset class with a sledgehammer. Basel II refined this with internal ratings-based approaches, letting banks calculate their own risk weights for certain exposures under strict conditions. Basel III came after the twenty-eight financial crisis and raised the quality bar significantly. It introduced the capital conservation buffer, the countercyclical buffer, and leverage ratio requirements that sit alongside CAR as a backstop.
Here is something most people miss when they first encounter CAR. The ratio can be gamed through securitization. If a bank bundles loans into a special purpose vehicle and sells tranches of them, those assets can come off the balance sheet entirely. The RWA drops dramatically and the CAR improves, even though the bank may still have exposure through credit enhancement or liquidity facilities. I watched a regional bank improve its reported CAR by roughly fourteen percentage points in a single quarter purely through a commercial mortgage securitization program. The underlying risk profile barely changed. Regulators tightened the securitization capital rules under Basel III precisely because of this kind of behavior. Another counter-intuitive reality is that more capital does not always mean a safer bank. There is an optimal range. Too little capital and the bank is vulnerable. Too much and the cost of equity capital depresses lending capacity, which can starve the local economy and indirectly hurt the bank's loan portfolio quality. I worked with a credit union that maintained a CAR above twenty-two percent for three consecutive years. They were technically impenetrable. Their problem was that they could not compete on loan pricing and lost market share to better-capitalized but more aggressive lenders. They eventually trimmed capital back to a more reasonable level and actually became healthier overall. The practical calculation involves mapping every asset to a risk weight. Cash and government bonds carry zero or low weights. Residential mortgages typically sit around fifty percent. Unsecured corporate loans are closer to one hundred percent. Credit card receivables can go as high as one hundred fifty percent under the standardized approach. Derivatives require a two-step process where you calculate the exposure equivalent and then apply a counterparty risk weight. The standardised approach for counterparty credit risk replaced the older current exposure method and is significantly more complex. Getting it wrong is easy because the formulas are long and the inputs are sensitive.
Get the Full Details
I ran into a specific edge case involving pension fund exposures. Under Basel III, defined benefit pension scheme obligations can create massive capital requirements if not handled carefully. A large corporation in our portfolio had a significant underfunded pension liability. Our standard model was flagging it with a risk weight that effectively doubled our capital charge for that relationship. The workaround was to apply the supervisory filtering adjustment available under the transitional rules, which allowed us to exclude a portion of the pension deficit from the risk-weighted asset calculation. It required documented justification and sign-off from our risk committee, but it brought the capital charge down to a manageable level. Without that adjustment, we would have had to either reduce the lending relationship or allocate additional capital that we did not want to tie up. Stress testing adds another layer on top of the basic CAR calculation. Institutions are required to run scenarios where GDP contracts, unemployment rises, and asset prices fall. The projected losses under these scenarios are measured against available capital to determine whether the institution would remain above its minimum requirements. The Dodd-Frank Act Stress Test and the Comprehensive Capital Analysis and Review in the United States are the primary frameworks for large banks. The European Banking Authority runs its ownEU-wide stress tests annually. These exercises frequently reveal that banks have been understating their capital needs because their internal models are too optimistic about correlation assumptions and recovery rates. One area where CAR reporting consistently breaks down is with illiquid assets and Level Three fair value measurements. When a bank has to mark certain securities to model rather than market, the risk weight and capital charge depend heavily on the valuation assumptions. I saw a situation where two banks held the same pool of mortgage-backed securities, but one used a more aggressive prepayment assumption and therefore carried a lower capital charge. The difference was not material to the individual security price, but aggregated across the portfolio it translated into tens of millions in capital. Regulators have tried to address this with the Output Floor under Basel III, which prevents internal model results from producing risk-weighted assets below eighty-five percent of what the standardized approach would generate. This has reduced the discretion but has not eliminated the variation.
Operational risk capital is another component that people tend to gloss over. It is calculated separately and added to the credit and market risk capital requirements. The Basic Indicator Approach multiplies average annual gross income by a fixed factor. The Standardized Approach breaks income into business lines and applies different factors. The Advanced Measurement Approach allows sophisticated banks to use their own internal loss data. Most mid-tier institutions use the standardised approach because the advanced method requires years of validated loss data and regulatory approval that is not easily obtained. What CAR does not capture is liquidity risk. A bank can meet its capital adequacy requirements and still fail if it cannot meet its short-term obligations. The Liquidity Coverage Ratio and the Net Stable Funding Ratio were introduced to address this gap. You need to look at both together. CAR tells you about long-term solvency. Liquidity ratios tell you about short-term survivability. The two are related but distinct, and treating them as interchangeable is a common mistake in boardroom discussions. Regulatory arbitrage remains the persistent problem. Banks find ways to structure products or reclassify exposures so that the risk weight falls without the actual risk declining. The leverage ratio serves as a non-risk-based backstop to limit this. It simply divides Tier 1 capital by total exposure without any risk weighting. This means that even if you game the risk-weighted asset calculation, your leverage ratio will still reflect the true size of your balance sheet. Since Basel III implementation, the leverage ratio has become increasingly important as a constraint on capital optimization strategies.
For anyone actually working with CAR calculations on a day-to-day basis, the single most useful practice is maintaining a clear audit trail between the GL and the regulatory reporting system. I have seen disputes where the finance team reported one number and the risk team reported another, and neither could explain the difference within the reporting window. The root cause was usually a timing mismatch or a reclassification that had not been communicated across departments. Building a reconciliation process that runs weekly rather than quarterly catches these issues before they become regulatory problems. The transition to Basel IV, also known as the Basel III finalisation package, is currently being implemented on a staggered basis across jurisdictions. Some countries are already enforcing the new output floor. Others are still in the transition period. This means that a bank operating in multiple jurisdictions will have different capital requirements depending on where each subsidiary is located. Managing this consistency is an ongoing operational headache that rarely gets discussed outside of capital planning meetings. If you are trying to understand a bank's true capital position from the outside, look beyond the headline CAR number. Check the leverage ratio, examine the composition of Tier 1 capital to see how much is common equity versus supplemental instruments, and review the disclosure on risk-weighted asset methodology. A bank with a strong CAR but a weak leverage ratio and heavy reliance on non-common equity Tier 1 is carrying more fragile capital than the headline figure suggests. The opposite can also be true. A bank with a moderate CAR but high quality common equity and conservative risk weighting is often in a stronger position than the number alone indicates.
There is no single wiki or reference that covers all of this because the framework changes constantly and varies by jurisdiction. The Basel Committee publications are the foundational source but they are technical and update frequently. National regulators add their own requirements on top. The practical knowledge comes from doing the work and dealing with the exceptions rather than reading a static document. That is why the topic keeps expanding and why no single source ever feels complete.


