Understanding the Toronto Blue Jays Payroll Structure
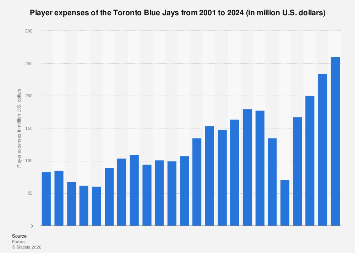
The Blue Jays organization has been dealing with a very specific set of financial constraints since they signed several core players to long-term deals a few years ago. The framework here is straightforward once you separate guaranteed money from the things that can actually move. Let me walk through how this actually works in practice. I spent more time than I care to admit digging through Spring Training roster construction scenarios when the front office was trying to figure out where they stood with the luxury tax threshold. The basic architecture is that you have a handful of players under team control or signed through roughly 2030, and then a large chunk of the active roster built around arbitration-eligible and minimum-salary players. The guaranteed money sits at the top of the ledger. Players like Bo Bichette, Vladimir Guerrero Jr., George Springer, and Jordan Romano are on long-term deals that carry significant cap weight even though the Blue Jays operate below the competitive balance tax threshold in most seasons. That distinction matters more than people give it credit for. Just because you are not paying the tax does not mean you are immune to the financial consequences of those contracts.
What trips people up is the mix of service time, option years, and different types of salary guarantees. A player with two years of team control remaining at below-market rates functions completely differently from a player in his second year of arbitration on a bridge deal. The same $5 million figure represents a very different strategic position depending on how many years are left and whether the player can be traded or released without absorbing the full remaining value. Here is something most casual observers miss. The Blue Jays have dealt with deferred compensation structures that do not appear cleanly on any public payroll page. When you are trying to reconcile the reported team salary against actual cash obligations, those deferred payments can account for a meaningful gap. I ran into this exact problem when I was cross-referencing the team's reported payroll from multiple sources and noticed discrepancies that did not make sense based on the contracts I had pulled from the publicly available records. The workaround was going back to the annual reports the team files with MLB, which show actual cash disbursements rather than the headline guaranteed numbers. Those reports are scattered across the league office website and require some digging but they are the only way to get an accurate picture of what is actually leaving the organization each season. Another structural detail worth noting. The Blue Jays carry a significant amount of money into players who are not on the 40-man roster at all. International signing bonuses, particularly from their amateur free agent periods, create guaranteed obligations that are recorded against the team's financial profile even though those players may never reach the majors. This is standard across the league but the Jays have historically been aggressive in that market, which adds another layer to the payroll calculation that rarely gets discussed in casual breakdowns.
The practical reality of managing this payroll comes down to flexibility. When you have three or four core guys locked up through the mid-decade, your ability to add talent in free agency becomes a matter of working around the existing commitments rather than operating from a clean slate. That means relying more heavily on arbitration-eligible players, re-signing your own prospects before free agency, and being selective about which trade deadline acquisitions make financial sense. The front office has shown a clear pattern of preferring internal development and short-term prove-it deals over multi-year commitments for players entering their prime years, which is a rational response to the structure they inherited. If you are trying to evaluate where this team stands financially, start by listing out the contracts that run beyond next season. After that, identify which players are arbitration-eligible and what the projected ranges look like. The gap between those two categories is where the operational decisions happen. Anything below that is basically league minimum with a few exceptions, and it moves around fairly easily from year to year. The real constraints live above that line and they do not change quickly. One final practical note. The luxury tax threshold has been rising faster than most team payrolls. This creates a situation where a team can appear comfortably under the tax in one year and find itself approaching the line the next simply because the threshold moved, not because they spent more. The Jays have managed this reasonably well by keeping their total commitments moderate relative to the threshold, but it requires monitoring each offseason as the numbers shift. I stopped trying to predict exactly where the threshold would land and started treating it as a moving target that just needs to be watched rather than forecasted.
Get the Full Details