Where To Actually Find The Real Inception Date Of The MSCI World Index
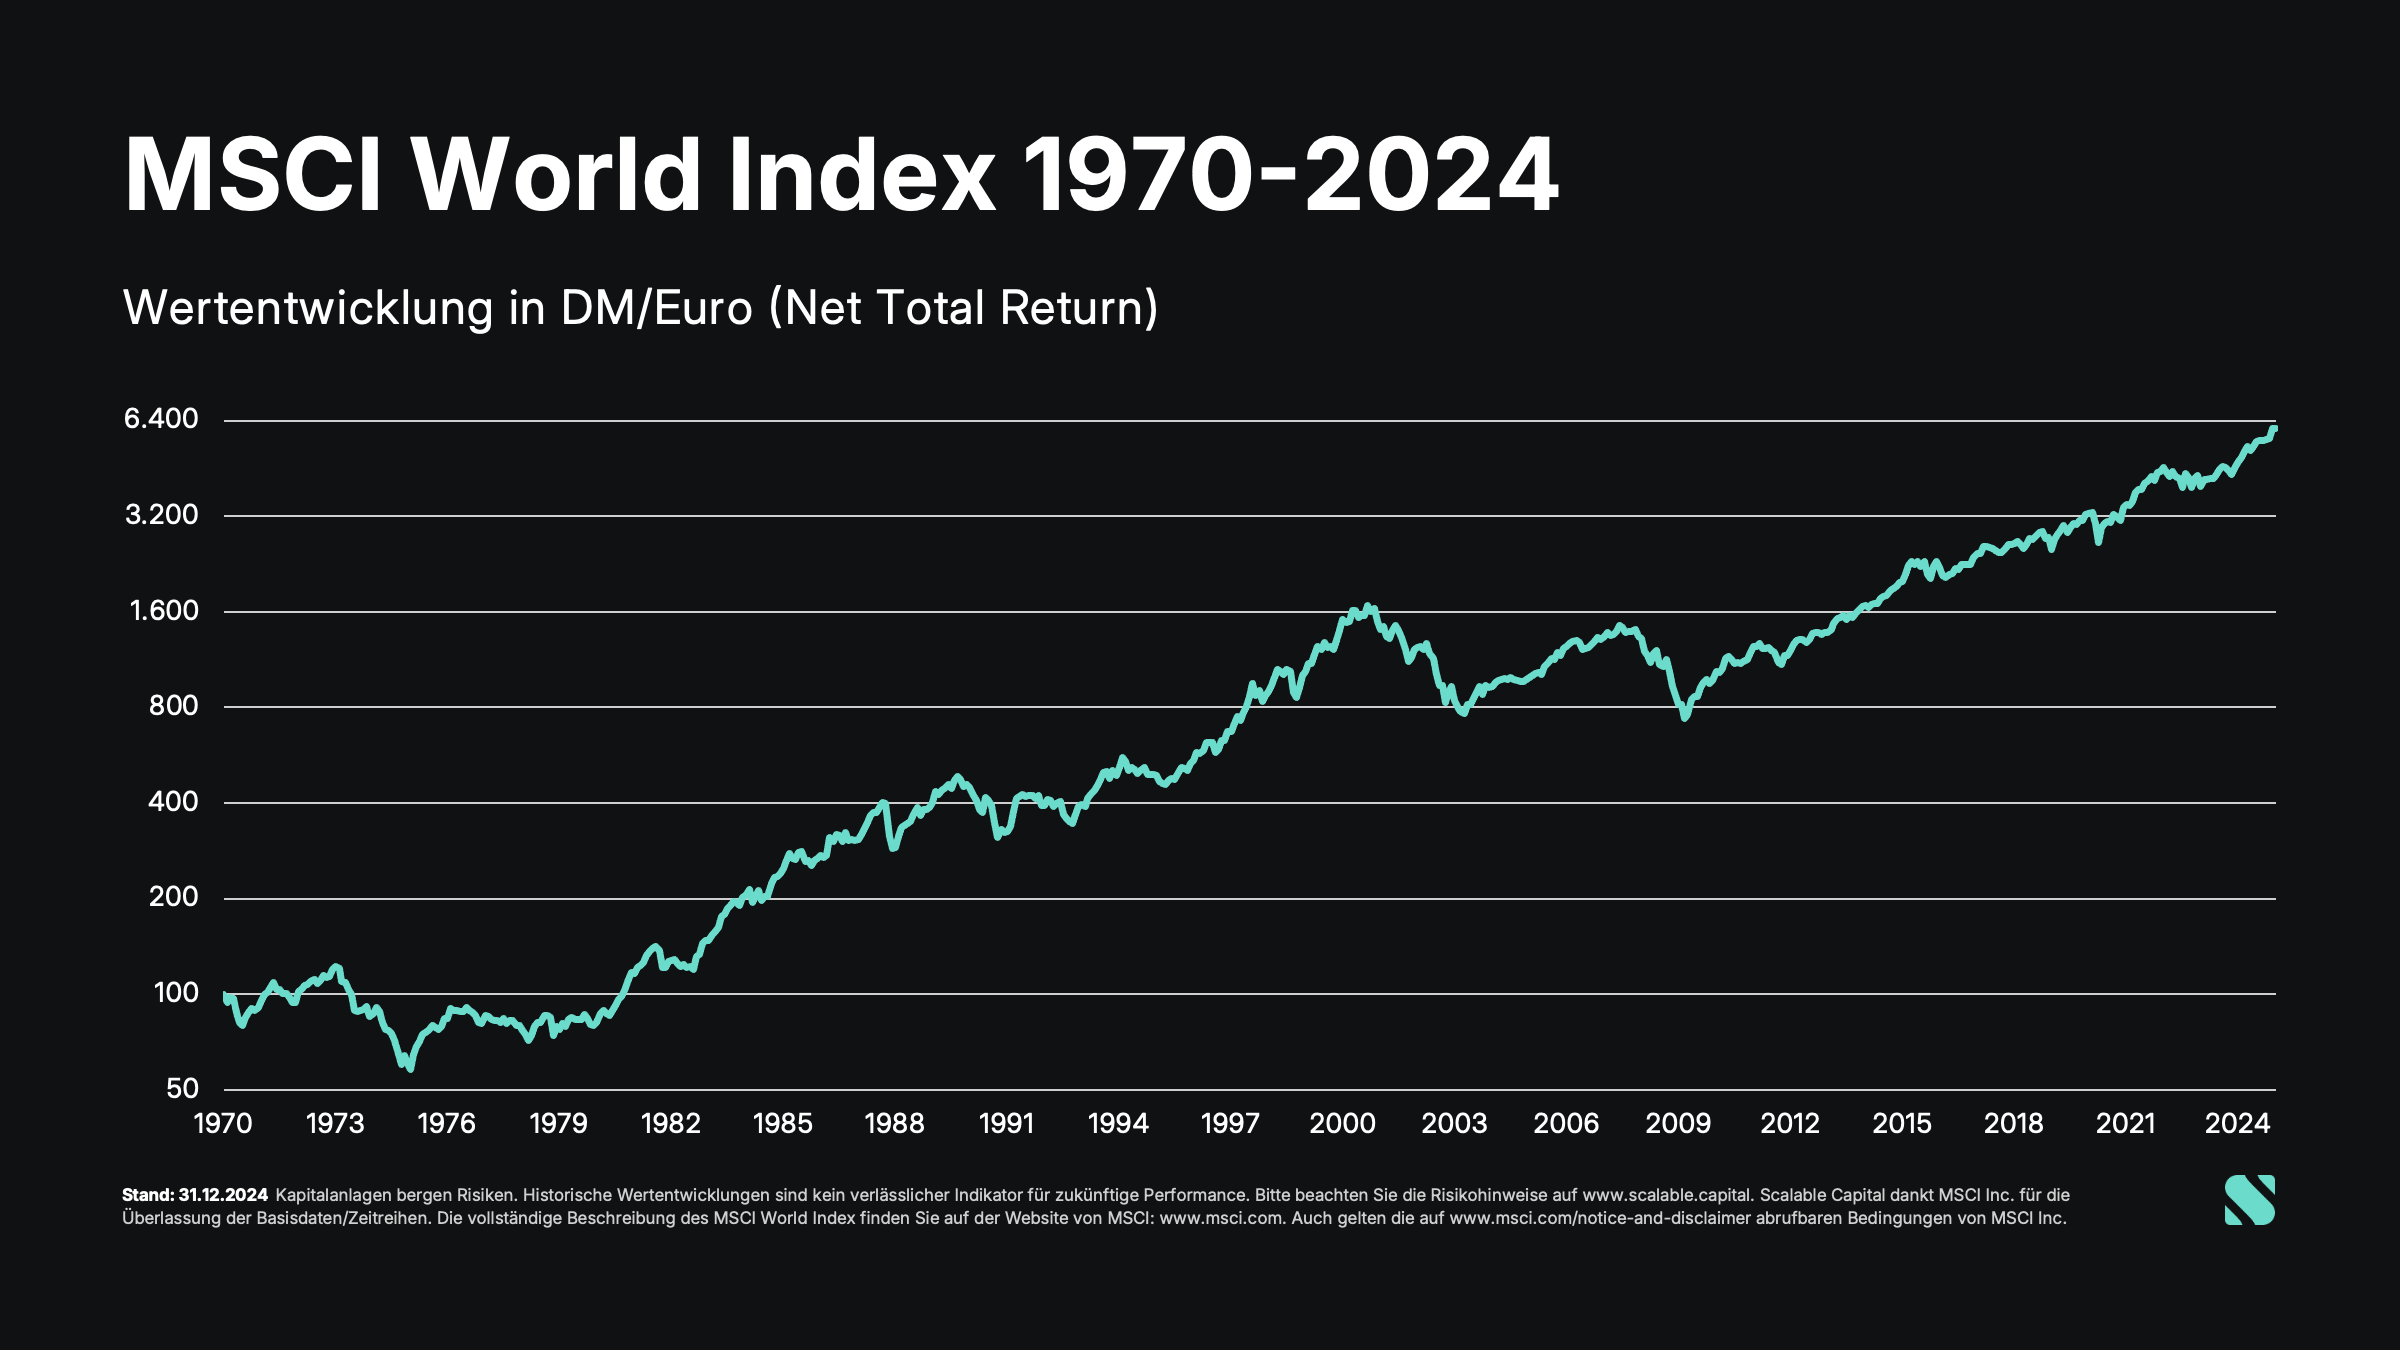
I spent about three hours last week tracing the exact birth date of the MSCI World Index because someone on our team needed to backtest a strategy against it. What I found was a maze of conflicting sources, MSCI methodology revisions, and data providers who copy-pasted each other's answers without checking the original documentation. Most websites will tell you the index started on January 1, 1969, and in a certain sense they're right, but that answer is incomplete and potentially misleading depending on what you're actually trying to do with it. The MSCI World Index officially has an inception date of January 1, 1969. This is the date MSCI itself lists as the index's starting point. It tracks large and mid-cap equities across 23 developed market countries, covering roughly 85% of the free float-adjusted market capitalization in those regions. The index was created by Morgan Stanley's investment research division before MSCI was spun out as a standalone company in 2005. Before that, it was known as the Morgan Stanley Capital International Index. Here's where it gets messy. If you pull the index from Bloomberg, the data might start appearing in your terminal around 1970 or later because data collection in the late 1960s was imperfect. Refinitiv data might have slightly different availability. FactSet might show the index from a different starting point depending on their historical reconstruction methodology. Yahoo Finance and other retail data sources typically won't have anything close to reliable pre-1970 data for this index. This discrepancy matters if you're doing academic work or building a quantitative model that requires consistent data back to the actual inception date.
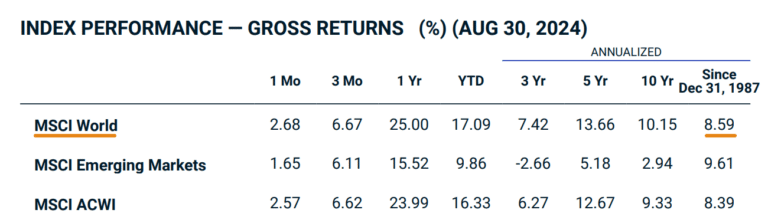
I encountered a specific problem when trying to match the index's inception with a backtesting framework. The strategy needed daily total return data going all the way back to 1969, but MSCI's publicly available price-only version and the total return version had a methodology change that wasn't documented clearly in the vendor data. The gross return series included reinvested dividends at the country level, while the net return series applied withholding taxes. My backtest was producing results that looked materially different from published performance figures, and the discrepancy traced back to which return variant the data provider was serving. The workaround was straightforward but not obvious: I switched to pulling the MSCI World Index Gross Return version directly from the MSCI license data feed instead of using a third-party aggregation layer. That eliminated the inconsistency, though it required an active institutional subscription to access the full historical series without gaps. There's another issue that most people running portfolio analytics overlook. The MSCI World Index underwent a major methodology revision in March 2012 when MSCI shifted from a price return to a total return basis for many of its flagship indices, including the World Index. Before that date, the index was calculated as a price return index without dividend reinvestment. After the change, the total return calculation was applied retroactively to the inception date. This means any performance comparison you make across that boundary is comparing two different calculation methodologies unless you account for the adjustment. Some data providers make this transition smooth. Some don't. You need to verify which handling your data source uses before you build any analysis on top of it.
Why The Inception Date Matters More Than You Think
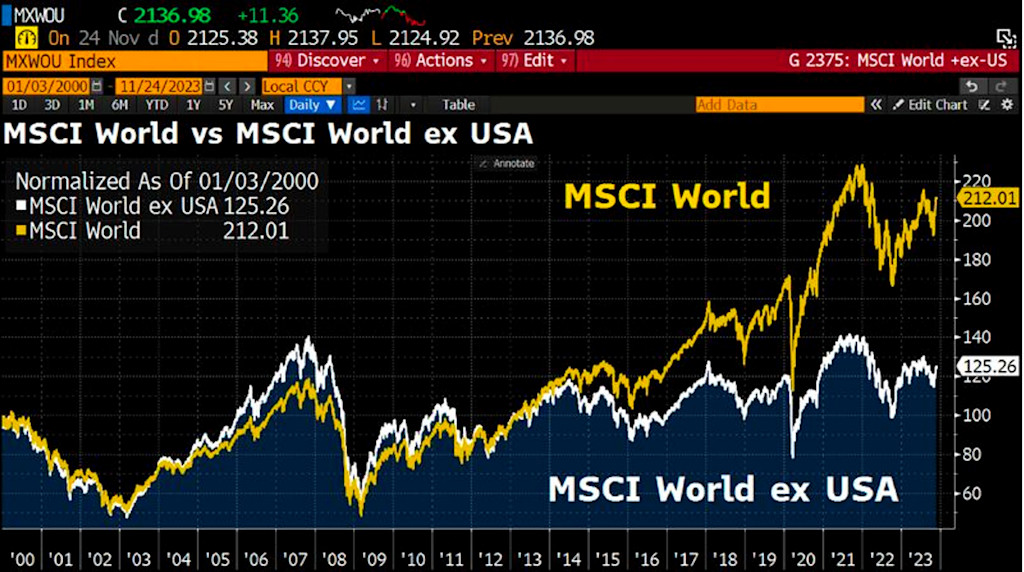
People treat the inception date as a checkbox item. They write it down and move on. But the inception date determines everything about how you should treat the data that follows it. Historical indices from the 1960s and 1970s had far fewer constituents than they do today. The number of countries represented in the MSCI World Index has changed substantially over time. Japan, for example, was excluded from certain periods and reincluded later, which creates a structural break in the index history that no amount of smoothing can hide. If your analysis window includes any of these composition changes without explicit adjustment, your results will be contaminated by reweighting effects that have nothing to do with market performance. Constituents matter too. The original MSCI World Index had fewer than 300 stocks. Today it holds well over 1,500. The index coverage of developed markets has expanded, and the free float adjustment methodology has been refined multiple times. When you're backtesting over the full history back to 1969, you're not just dealing with different stock counts. You're dealing with a fundamentally different universe of investable securities and changing liquidity conditions. A strategy that looks robust over the full inception period may be generating returns that simply reflect the expansion of the investable universe rather than any genuine alpha. I've seen this play out repeatedly in client portfolios where someone would construct a factor exposure model using the full MSCI World history and the results would look impressive until you stripped out the post-1990 period. The factor premiums in the earlier decades were structurally different because market microstructure, trading costs, and information availability were completely different environments. The inception date tells you the full extent of the data available, but it doesn't tell you whether that data is comparable across time periods. You need to segment the history and check for structural breaks manually rather than trusting the index provider to have normalized everything.
Get the Full Details
How To Work With The Data Once You Have It
If you're working with the MSCI World Index data yourself, start by confirming which series you're using. Price return, gross total return, and net total return will give you different numbers, sometimes significantly different over long horizons because of dividend yield variation. The gross return version is generally what you want for institutional benchmarking because it reflects the full dividend income before taxes. The net return version matters for actual investor outcomes in taxed accounts. Price return alone will overstate performance if you're evaluating a strategy against what an actual fund would earn. Frequency is another practical consideration. Daily data exists for the index going back to inception, but weekly or monthly data is more commonly used for portfolio-level analysis. If you're working with daily returns, you'll encounter some days with no index value because the underlying exchanges were closed or because MSCI made methodology changes on specific dates. You need a consistent rule for handling missing values. Forward filling is standard practice, but you should document exactly when and why a gap appears so future audits don't question your methodology. Rebalancing dates affect the data too. MSCI rebalances the World Index quarterly, with the adjustment dates typically falling on the last trading day of March, June, September, and December. Changes to the index methodology, country classifications, or constituent eligibility happen throughout the year as well. These adjustments create small discontinuities in the return series. For most applications, the impact is negligible. For high-frequency strategies or precise performance attribution, you need to overlay the rebalancing calendar and flag any returns that span an adjustment date.
There's no single download link that gives you a clean, complete, accurate dataset for the entire history of the MSCI World Index. The data is proprietary to MSCI. Institutional subscribers get access through licensed data feeds from vendors like Bloomberg, Refinitiv, FactSet, or MSCI's own direct platform. Retail investors typically encounter the index through ETFs like VWO or IXUS, but those funds track modified versions or subsets of the index, not the full inception-to-present benchmark. If you need the complete historical series for research purposes, you're looking at a licensing arrangement, which runs into the tens of thousands of dollars annually for full institutional access. Academic institutions sometimes get discounted rates through library subscriptions. The key takeaway is that January 1, 1969 is the official inception date, but working with that data requires more care than most people apply. Verify your return series, check for methodology breaks around 2012, segment your analysis by period to catch structural changes, and don't assume your data provider has handled all the edge cases cleanly. The index is useful. The data is powerful. Both require deliberate handling to be trustworthy.