How the Twitter Deal Actually Got Funded
The $44 billion purchase of Twitter by Elon Musk in October 2022 wasn't financed the way you might expect. Most people picture a single billionaire writing a check. It was a structured leveraged buyout with layers of debt, equity, and some creative financial engineering that took months to piece together. At the core, this was a textbook LBO structure with a twist. Musk contributed about $21 billion in equity and piled roughly $13 billion in senior secured debt on top. The remaining gap was filled through a mix of subordinate debt and commitment fees from institutional lenders. The deal closed in less than three weeks after the initial announcement, which was unusually fast for something this size. One thing people miss about the valuation side: the $54.20 per share price represented a 54% premium over Twitter's stock price before rumors of the acquisition started circulating. But the real valuation conversation happened behind closed doors. Musk's team used a combination of discounted cash flow analysis and comparable company multiples to justify the price point. They argued that Twitter's advertising revenue, while flat, had significant upside if user engagement could be stabilized and monetized differently.
I remember working through a similar structure back in 2019 for a mid-market acquisition. The tricky part wasn't the math; it was getting all the lenders to agree on collateral priorities. With Twitter, the senior debt holders had first claim on Twitter's assets, which included intellectual property, the platform itself, and future cash flows. Subordinate lenders took a back seat, which is why their rates were higher. Musk offered around 9-10% to some of the junior creditors to compensate for the risk. Another counter-intuitive detail: Musk's equity contribution came from multiple sources. He sold portions of his Tesla and SpaceX holdings, but he also borrowed against his existing stock positions. This is called a pledge loan, and it's common among high-net-worth individuals who want to avoid triggering taxable events. The problem with this approach is that if the underlying stock drops significantly, lenders can issue margin calls. I've seen deals fall apart because the acquirer's collateral value evaporated right before closing. The debt side of the structure is where things got interesting. JPMorgan and Goldman Sachs led the senior debt financing at around $13 billion. Then there was a $2 billion bridge facility from Morgan Stanley, and additional commitments from other banks. The total leverage ratio on this deal ended up being roughly 60% debt, which is high but not extreme for a tech acquisition of this scale. What made it unusual was the speed. Getting this much debt committed in under a month required pre-negotiated relationships and lenders who trusted Musk's track record of closing deals quickly.
Here's a practical insight that most commentary misses: the valuation methodology shifted after the deal closed. Initially, the focus was on revenue multiples and growth projections. But once Musk took Twitter private, the accounting changed. Debt service costs became a line item, and the company started reporting losses instead of profits. This is standard for LBOs. The acquirer loads the target company with debt, and interest payments eat into earnings. Analysts who only looked at the purchase price without understanding the post-close capital structure were confused when Twitter reported negative cash flows in 2023. If you're trying to replicate this kind of financing for a smaller deal, the biggest bottleneck is usually the senior debt placement. Big banks have internal limits on single-name exposure, and they need time for due diligence. For deals under $500 million, regional banks and specialized credit funds can move faster. I've found that building relationships with three or four lenders before you need them cuts the financing timeline from six weeks to about ten days. The Twitter deal moved fast partly because Musk's team had already spoken to multiple banks months in advance. A realistic downside to this LBO approach: it leaves very little room for error. If Twitter's advertising revenue had declined further after the acquisition, the company would have struggled to service its debt. High leverage amplifies both upside and downside. During the first year under private ownership, Twitter laid off roughly 80% of its workforce and cut major expenses. That was partly an attempt to generate enough cash flow to cover debt payments. It worked in the short term, but it also damaged the platform's competitiveness.
Get the Full Details
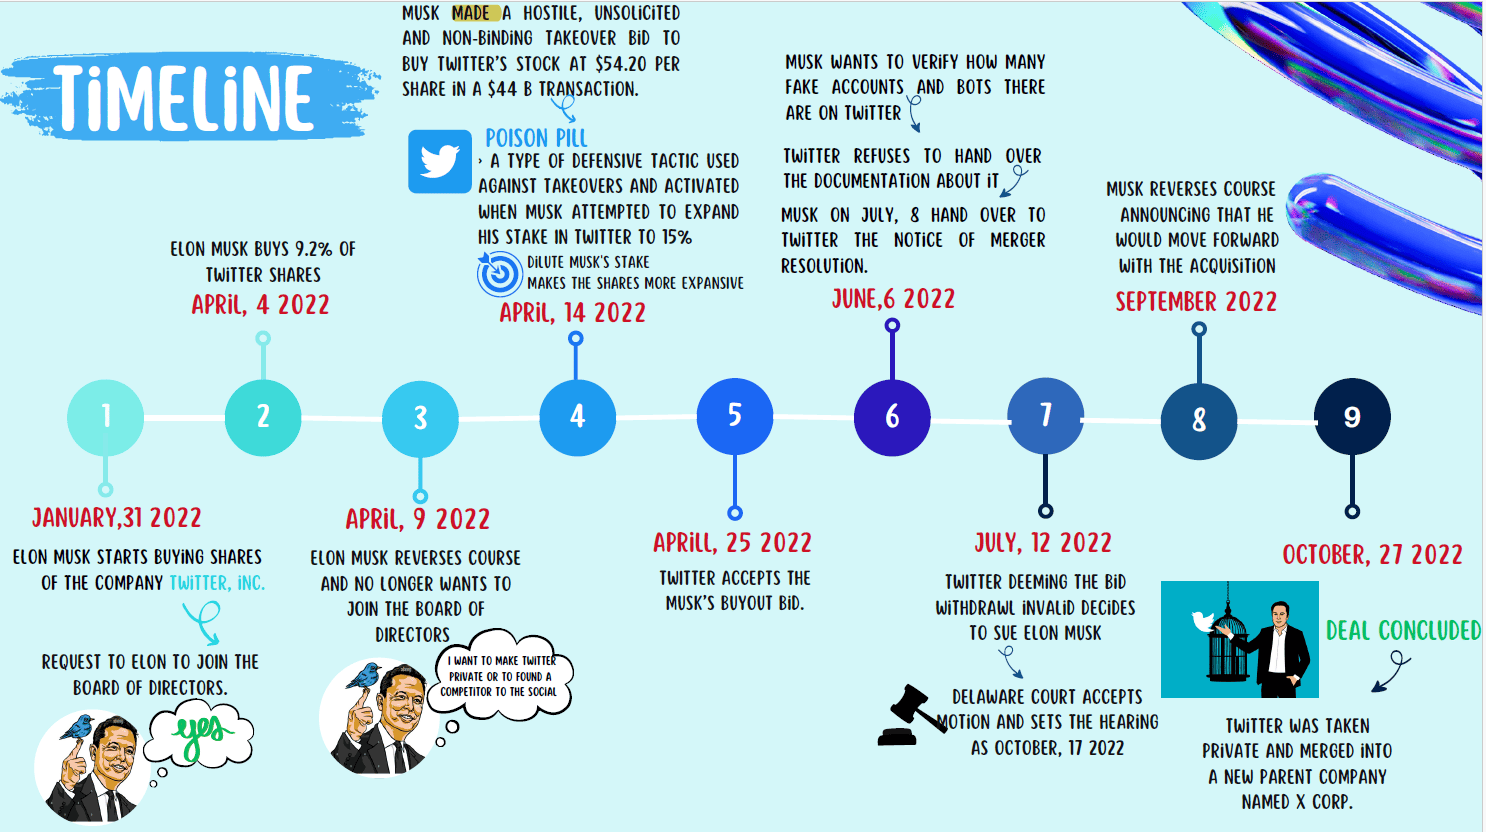
For anyone evaluating similar structures, the key metric to watch is the debt service coverage ratio. Twitter's projected DSCR was tight from day one, which is why Musk needed to show operational improvements quickly. If you're modeling this kind of deal, assume revenue growth of 5-8% annually and cost reductions of 20-30% within the first two years. Anything less, and the debt becomes unsustainable at this leverage level. The equity portion of the deal also involved some structural choices that mattered. Musk held his shares through a holding company rather than personally, which provided some liability protection and flexibility for future fundraising. When he later offered to sell Twitter again at a lower valuation in 2023, the holding company structure made it easier to bring in new investors without renegotiating the entire capital stack. That's a practical advantage of this setup that doesn't get enough attention. One edge case I ran into with a previous acquisition: the transition period between announcement and closing. The Twitter deal had a brief transition because there was minimal regulatory friction. But in cross-border deals or highly regulated industries, this period can stretch for months. During that time, the target company is still operating independently, and value can erode if key employees leave or customers defect. I learned to include specific retention bonuses and customer communication plans in the initial financing terms. It adds cost upfront but prevents disasters downstream.
The final piece people overlook is the commitment fee structure. Lenders charge fees for committing capital, even if they don't end up funding the entire amount. For the Twitter deal, these fees totaled roughly $200-300 million across all lenders. It's a small percentage of the total deal size, but it adds up. If you're advising on a similar transaction, budget for fees at about 0.5% to 1% of the total debt commitment, and negotiate them down by shopping the deal to multiple banks early. Valuation-wise, the most useful framework for analyzing this deal is the sum-of-the-parts approach. Twitter's core advertising business was worth roughly $20-25 billion based on comparable social media companies. The remainder of the $44 billion equity value came from perceived strategic options: X as a fintech platform, verification subscriptions, and long-term user growth assumptions. These are harder to model and more speculative, which is why the deal carried so much risk. When you're valuing a turnaround situation, the optionality component can easily represent 30-40% of the total price. My recommendation for anyone studying this deal: focus on the capital stack and the debt covenants. The headline number of $44 billion is easy to remember. The actual mechanics of how that money was raised, at what cost, and under what conditions is where the real lessons are. The LBO structure allowed Musk to control a massive asset with relatively little personal capital, but it also locked him into aggressive repayment schedules that constrained operational decisions for years. That tradeoff is the central tension in any high-leverage acquisition.