How The Ulta Co-Branded Card Actually Works (And Where People Lose Money)
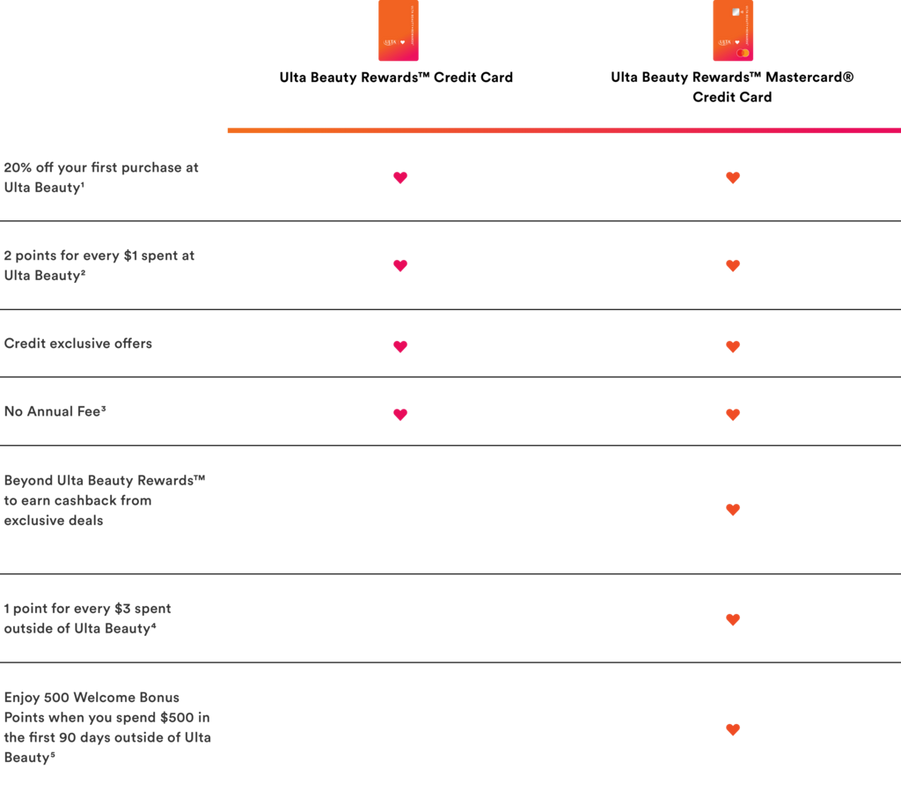
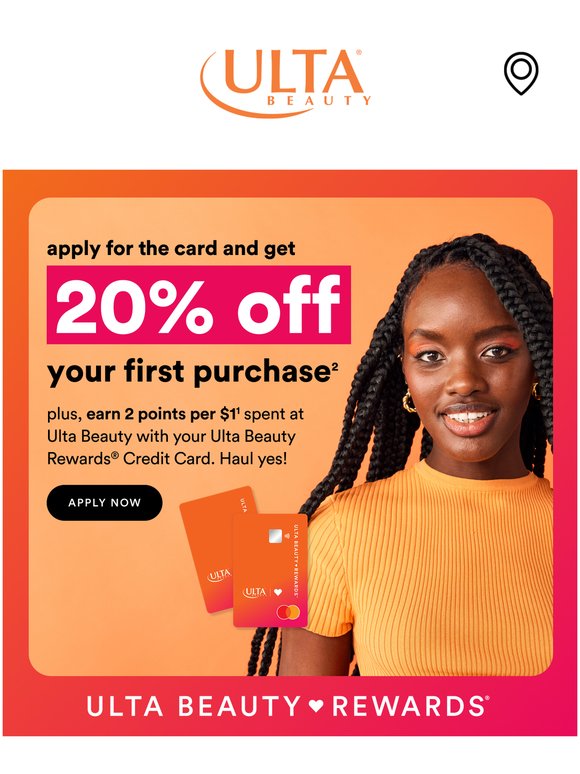
I've been rotating my beauty purchases around the Ulta credit card for about six years now. I applied for it on a lark in 2018 because they were offering 20% off your first purchase with the card. I calculated that I could front-load about $400 worth of my usual monthly haul, hit the discount, and basically get the card paid for in two weeks. That math still holds up today, but only if you play by certain rules that the marketing materials will never tell you. Most people treat this card like a regular rewards card. It isn't. It's a tier-gated promotional stacking instrument disguised as a loyalty program. The difference matters more than most shoppers realize.
The Biggest Ulta Beauty Secret How Comenity Mastercard Users Get Ahead Of The Game
The actual mechanism works through the Ultamate Rewards tier system. You start at Beauty, which gives you 1 point per dollar. Reach Salt (around $100 in a calendar year) and you get 2 points per dollar. Reach Gold (roughly $350 annually) and you get 3 points per dollar. Points convert to $1 rewards at a rate of 100 points = $1. So at Gold tier, every dollar you spend nets you 3 cents back in reward currency. Here's where it gets complicated. The card itself gives you an additional 2 points per dollar on all Ulta purchases. So at Beauty tier you're looking at 3 total points per dollar (1 from the program, 2 from the card). At Gold tier it jumps to 5 points per dollar. That's a 5% return before you even factor in sales or promotions. It's competitive with cashback cards but only if you're already shopping at Ulta regularly. The catch most people miss is that points do not carry over indefinitely. They expire after 12 months of inactivity on your rewards account. If you close your account or go a full year without earning or redeeming points, whatever you've accumulated gets nuked. I lost about $18 in points once because I stopped going to Ulta for a stretch and forgot to make a dummy purchase to reset the clock. A single eyeshadow primer at $9 was enough to reactivate everything.
Another thing nobody mentions: the sign-up bonus changes constantly and is almost never the headline number. When I first applied, it was 20% off the first purchase. A few months later it was 30%. Some months you might see "double points for 60 days after opening." The offer is dynamic based on when you apply, how many recent applications Comenity has on your credit file, and sometimes your geographic region. There is no consistent best time to apply. I've learned to check the current offer on the Ulta website before clicking through to the Comenity application page. If it looks underwhelming, close the tab, wait a few weeks, and check again. The offers rotate frequently enough that this strategy works.
Get the Full Details
Setting Up The Account Correctly
You apply directly through the Comenity portal, not Ulta's main site. The application does a hard credit pull, usually FICO-based. Expect a decision within seconds to a few minutes for most applicants. If you get declined, you won't know why immediately. The denials typically cite insufficient credit history or recent hard inquiries. I was denied twice before getting approved because I had applied for two other store cards in the same month. Waiting until my inquiry count dropped to one previous application in the last 90 days worked. Once approved, you need to link the card to your Ulta rewards account. This is not automatic. Go to your Ulta account settings, find the payment methods section, and manually add the new card. Then verify that your rewards profile shows the co-branded card icon next to your account. If it doesn't, you're still earning at the base rate and nobody will tell you.
The Stacking Strategy
This is where the real advantage lives. Ulta runs a near-constant schedule of events where you can layer the card's 2 extra points on top of promotional multipliers. The standard event calendar includes: Birthday Month: You get 2x points on everything during your birthday month. Stacked with Gold tier + card, that's 10 points per dollar. A $200 purchase becomes 2,000 points, or $20 in reward currency. That's effectively an extra 10% off on top of whatever sale is running. Semiannual Sale: Usually in May and November, Ulta runs a 21% off everything event. If you combine this with your birthday month multiplier, you're looking at roughly 31% effective discount on a single receipt. I've seen people claim you can push even higher with gift card promotions, but I haven't personally verified that working reliably. The math gets murky when you factor in whether gift card purchases earn points (they usually don't).
Event Days: Ulta posts event calendars periodically where specific categories earn bonus points. Skincare event, makeup event, fragrance event. These stack with the card. I track these in a simple spreadsheet and time my larger purchases accordingly. The key insight is that the card's 2 extra points per dollar apply to every transaction, including sale items. Most rewards cards exclude promotional purchases or cap bonus earnings. The Ulta card does not. This is genuinely unusual and worth exploiting aggressively during sale periods.

The Price Adjustment Loophole
Ulta's price adjustment policy allows you to request a refund of the difference if an item goes on sale within 14 days of purchase. Here's how I use it with the card: buy something at full price during your normal shopping trip. If it drops to a sale price within two weeks, go back and file a price adjustment. Your charge decreases, but here's the thing nobody warns you about — the points you earned on the original purchase are recalculated at the lower amount. So you lose points on the difference. I factor this into my planning. It's usually not worth the hassle unless the sale is significant enough that the net savings still exceed the point loss. For a $5 price drop on a $25 item, I let it go. For a $20 drop, I definitely file the adjustment. First, people sign up for the card and immediately max out their first-purchase discount on a single receipt. This is dumb because you're leaving future sign-up bonus points on the table. If you're at Gold tier with a strong sign-up offer, space your first purchases across two or three receipts over the first week. You still get the first-purchase discount on each one, and you compound your early-point earnings. Second, people buy gift cards with the card to load onto other accounts or resell. The card explicitly excludes gift card purchases from earning bonus points. You earn only the standard 1 point per dollar on gift cards, not the 2 extra. This is a rule that changes rarely but is enforced consistently. I learned this the hard way when I tried to buy $300 in gift cards during a sale thinking I'd lock in points. I earned almost nothing extra on that transaction.
Third, people forget to redeem before points expire. The 12-month inactivity rule is real. I set a calendar reminder every January and July to check my point balance and make a small purchase if needed. The cost of a $5 lip balm to keep points alive is negligible compared to losing hundreds in accumulated rewards.
When The Card Isn't Worth It
Let me be blunt about the downsides. The credit limit starts low, typically $200 to $500 for new applicants. If you're planning big fragrance or skincare hauls, you'll hit your limit quickly and miss out on the stacking strategy. The annual fee is zero, which is fine, but the APR is steep — around 29% variable. Carrying a balance completely destroys any mathematical advantage the rewards provide. Also, the card is a store card. It only works at Ulta. If you shop at Sephora, Target, or Amazon for beauty products, this card gives you nothing on those purchases. Compare that to a general cashback card like the Citi Double Cash or a travel card with flexible redemption, and the Ulta card loses for casual shoppers. It's only worthwhile if you spend at least $350 per year at Ulta to reach Gold tier and can time your purchases around the event calendar. I don't recommend it if you've ever had a late payment or carry balances month to month. The APR will eat any rewards benefit within two billing cycles. And don't expect this card to help your credit score significantly. It's a thin file addition — one account, moderate limit. You'll see a small bump from the hard inquiry initially, then a gradual improvement from positive payment history if you pay on time. But it's not a game-changer for your credit profile.

The bottom line is that the Ulta Comenity Mastercard is a niche tool. It works well for dedicated Ulta shoppers who understand the event calendar and can live within a low credit limit without carrying a balance. For everyone else, a standard cashback card probably serves them better. I keep mine open purely because the math works for my shopping habits. I wouldn't open another store card unless the numbers looked this favorable again.