Understanding How Berkshire Hathaway Actually Operates
Most people think of Warren Buffett and Berkshire Hathaway as just a big investment fund. That description is technically accurate but completely misses how the machine actually runs. The company generates operating income from dozens of wholly-owned businesses — insurance, railroads, energy, manufacturing, retail — while simultaneously maintaining a public equity portfolio worth over $300 billion. The synergy between these two engines is what creates the compounding effect most observers never notice. Here is how I approached learning about this structure a few years ago when I was evaluating whether to allocate capital toward Berkshire shares for a client portfolio. I started with the standard annual letter and quickly realized that reading Buffett's letters alone gives you roughly 40% of the picture. The real mechanics live in the Form 13F filings, the subsidiary financials buried in the annual report, and the difference between reported earnings and operating earnings — a distinction Buffett himself insists on making but most casual investors skip entirely. One problem I ran into specifically involved the insurance float calculation. Berkshire reports combined ratio figures quarterly, but the timing of catastrophic losses can distort the trailing twelve-month view dramatically. After Hurricane Ian hit in late 2022, I found that looking at a single quarter's surplus numbers gave a misleading impression of underwriting discipline. My workaround was to track the trailing four-quarter operating earnings excluding investment gains and losses, which smoothed out those distortions and gave a much clearer read on what the underlying business was actually producing. I still do this every quarter when reviewing the position.
The operating businesses are where the real durability lives. GEICO, BNSF Railway, Berkshire Hathaway Energy, and the long list of smaller manufacturers each contribute cash flow that gets reinvested. During periods when equity markets are flat or declining, those operating earnings become the primary source of share price appreciation. In 2022, while the S&P 500 fell roughly 19%, Berkshire's operating earnings grew about 12% year over year. That margin of safety is not dramatic but it compounds relentlessly across decades.
The Capital Allocation Mechanism
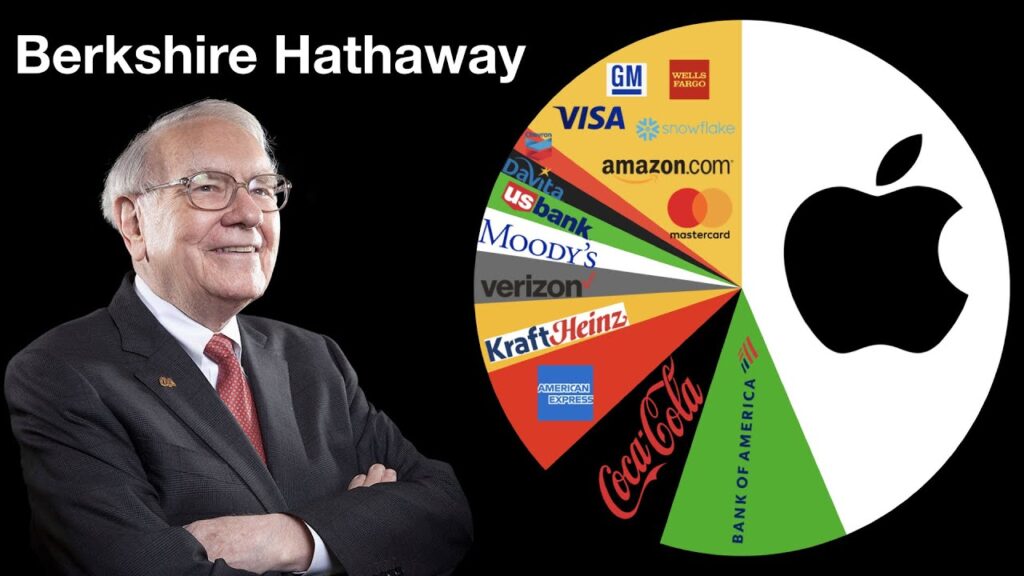
What separates Berkshire from every other large-cap holding company is the deployment hierarchy Buffett follows. Operating earnings first fund the subsidiaries' capital needs. Remaining cash goes into buying high-quality businesses at fair prices. Then it flows into publicly traded equities, mostly in companies where Buffett has been quietly accumulating positions for months or years before they appear in any 13F. Finally, any leftover capital gets used for share buybacks when the stock trades below intrinsic value. A counter-intuitive point most beginners miss is that Berkshire's largest equity positions are often the least exciting companies on paper. Apple, Bank of America, American Express, and Chevron don't look like classic Buffett holdings. They are large, mature, cash-generating businesses trading at reasonable valuations. The thesis is not rapid growth — it is capital return through dividends and buybacks combined with durable competitive advantages. When I first started analyzing Berkshire's portfolio construction, I kept looking for growth stories and nearly overlooked why the boring holdings dominate the allocation. Another nuance is the role of retained earnings versus distributed earnings. Berkshire retains virtually all earnings from its operating subsidiaries. This means earnings compound inside the company rather than flowing to shareholders as dividends. The tax efficiency of this structure is significant. A dividend from a company like Coca-Cola gets taxed again in your hands. A retained dollar at Berkshire compounds at the corporate level and only gets taxed when you sell the share, potentially decades later.
Get the Full Details
Practical Considerations for Investors
Buying Berkshire stock is straightforward — it trades under BRK.A and BRK.B on NYSE. The A-share class trades around $600,000 per share and the B-share class trades around $400. Both classes have identical voting rights and economic interests, so the B-share is the practical vehicle for most investors. There is no special application process or waiting period, unlike private equity commitments or hedge fund allocations. The main downside to this approach is succession risk. Buffett is in his late eighties and while Greg Abel is clearly positioned as the successor, no one can guarantee that the next decade of capital allocation will replicate the past six. I have noted this risk explicitly in client discussions and suggested that Berkshire should represent no more than 8-12% of a diversified equity allocation for that reason. It is not a full-position recommendation for most portfolios. Another limitation is valuation sensitivity. When Berkshire trades above 1.5 times book value, the expected returns from that entry point drop significantly. At 1.2x book or below, the risk-reward shifts in favor of accumulation. I track this metric quarterly and use it as my primary signal for adding or reducing the position rather than relying on sentiment indicators or market timing.
The company also does not pay a dividend. If you need income from your holdings, you either sell shares periodically or accept that you are investing for total return rather than cash flow. This frustrates some income-focused investors but aligns with the compounding philosophy. The alternative of buying individual dividend stocks introduces concentration risk and requires more ongoing management than most investors are willing to handle. I found that the annual shareholder meeting in Omaha each May provides useful signaling on direction without being predictive. The questions from shareholders about insurance pricing, energy regulation, and potential acquisitions reveal where management is focusing attention. I attend the meeting virtually each year and spend about two hours reviewing the commentary. It rarely changes my allocation decision but it keeps me informed about operational shifts before they show up in quarterly filings. The long-term data supports the strategy. Since 1965, Berkshire has compounded at roughly 19.8% annually versus 10.2% for the S&P 500. That differential sounds large but narrows considerably over shorter periods. The ten-year annualized return through 2024 comes in closer to 11-12%, which still beats the index but reflects the reality that size makes extreme outperformance mathematically unlikely. The company now manages trillions in assets and each incremental dollar is harder to deploy efficiently than it was in the 1980s.
For most investors evaluating whether to include Berkshire in their portfolio, the answer depends on what they are trying to achieve. If the goal is steady compounding with lower volatility than a pure equity portfolio and willingness to hold for ten years or more, it fits well. If you are looking for high growth or near-term income, there are better options available. The structure is designed for patience, not excitement.