The Sears Credit Card Reality Check
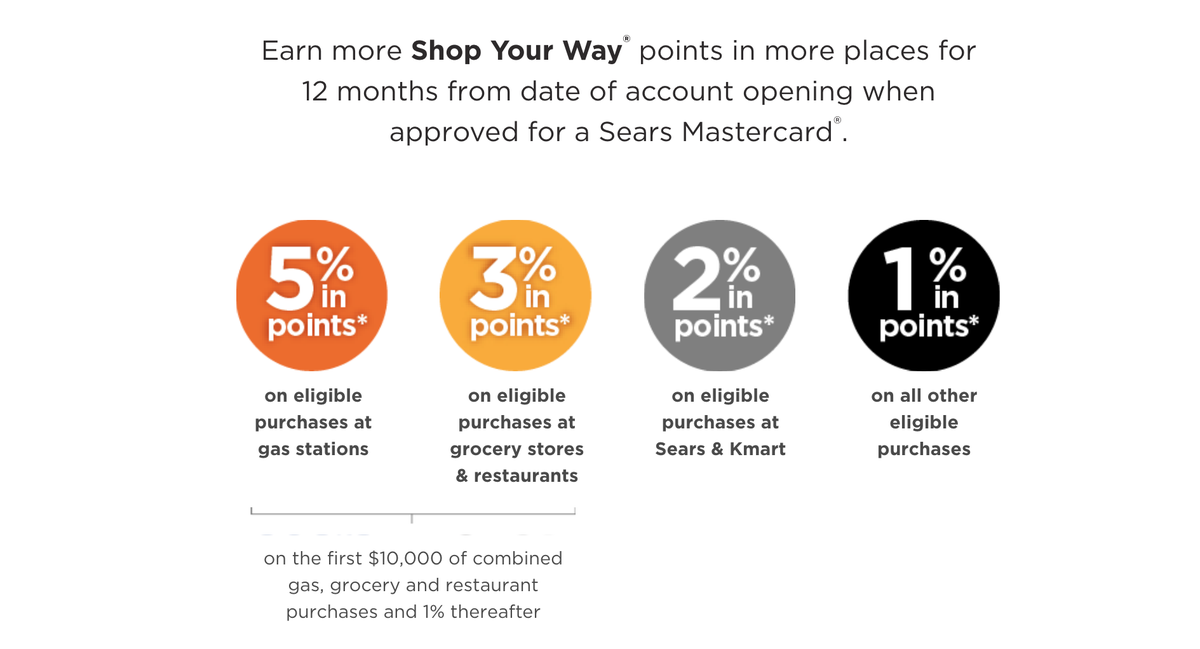
Sears closed most of its physical doors over the last decade, but the credit card situation lingers in ways people don't always understand. The Sears Credit Card used to be straightforward. You swiped it at a Sears store, you got financing on big appliances, you earned rewards. The mechanics behind that simple idea are more complicated now, and whether it is worth anything depends entirely on what store network you have access to and how you handle the debt side of things. The Sears Visa and the older Sears Card operated under different rules even before the closures. The Sears Card was a closed-loop store card. You could only use it at Sears, Kmart, and a handful of affiliated retailers. The Sears Visa, issued through JPMorgan Chase after the Citi transition, opened up slightly but still pushed hardest for Sears ecosystem spending. If you live anywhere near a functioning Sears or have regular access to a Kmart, the store card version still offers promotional financing that can be useful. 48-month deferred interest on appliances and tools is the main draw. It is not a great rate for normal purchases, but if you pay off a refrigerator purchase in full before the promo window ends, you effectively got an interest-free loan for four years. That is genuinely rare at retail. The rewards structure has shifted multiple times. At its peak, cardholders earned 5 percent back on Sears purchases and 1 percent elsewhere. Right now, the reward rates are much lower across the board, and the catalog redemption model feels outdated. You redeem points for gift cards or statement credits, but the value per point is poor compared to what most cash-back cards offer today. A typical Sears card might give you one point per dollar on general purchases. That translates to roughly 0.5 to 1 cent per point when redeemed, depending on the redemption method you choose. Most people do not track that closely and end up leaving value on the table.
Building credit was another reason people kept the card open. A Sears card with a modest limit and a history of on-time payments can nudge a thin file forward. But you can achieve the same result with a secured card or a basic retail card from a issuer that actually reports consistently to all three bureaus. Sears had periods where reporting was spotty. I noticed this myself when a cardholder called me because their score had dropped despite paying on time. Their account simply was not being reported to one of the major bureaus for several months. We tracked down the issue by pulling all three credit reports side by side, found the gap, and the account eventually started reporting again without any action from the cardholder. Sometimes these things self-correct. Sometimes they do not. The drawbacks are substantial and mostly financial. The standard APR on a Sears card runs high. I have seen quotes in the 25 to 30 percent range depending on the holder's credit tier and when the account opened. Deferred interest promos are where most people get burned. You see zero percent financing and assume it means zero percent total cost. It does not. If you miss a single payment or carry a balance past the promo deadline, the original purchase amount gets retroactively charged interest from the purchase date. I had a customer who financed a $1,200 mower through the Sears card. They missed one payment by four days. The deferred interest kicked in and they were on the hook for roughly $300 in back interest. That is the single most important detail people skip. Read the fine print on every promo offer before you rely on it. Acceptance is another real problem. Sears stores are gone or shrinking. The card only works where Sears and Kmart still operate, plus a few affiliated brands. If you shop online, the Visa version works anywhere Visa is accepted, but you are no longer getting any meaningful boost to rewards or perks for spending outside the Sears ecosystem. The card essentially becomes a high-interest general purpose card with very weak rewards, which is not a useful position to be in.
There is also the matter of customer service. The Sears card has been through multiple issuer transitions and ownership changes. Support lines are long. Dispute resolution takes time. Account management through the online portal is functional but dated. If you need help with a billing error, expect to spend more time on the phone than you would with most modern issuers. My recommendation comes down to usage patterns. If you buy large appliances or tools from Sears on a regular basis and you can guarantee you will pay off the promotional balance within the deferred interest window, the card has a narrow use case. Keep it open, use it selectively, and set a calendar reminder for the promo end date so you do not get hit with retroactive interest. If you do not shop at Sears or Kmart frequently, the card is not worth opening. The high standard APR and poor rewards make it a bad default card for everyday spending. For people trying to rebuild credit specifically, there are better options. A secured card from a bank with solid bureau reporting and no annual fee will do the same job without the trap of deferred interest terms. If you want retail financing, look at the Affirm or Klarna options at checkout instead. Those are transparent about total cost upfront. The Sears card hides its real cost behind promotional language that sounds like savings but often is not.
Get the Full Details
The bottom line is boring. The Sears Credit Card is not a great product for most people anymore. It has one useful niche around appliance financing, but the risks of deferred interest traps and weak rewards outweigh the benefits for the average holder. Use it carefully if you must, or skip it entirely and pick something simpler.