Setting Up Online Banking Without Losing Your Mind
Most people treat online banking like it is something complicated to learn. It is not. I have watched customers sit on hold for forty-five minutes because they wanted to set up a bill pay, when they could have done it in under five minutes on their phone. The actual platform matters less than understanding how to navigate it before you need to. I spent three years working with banking platforms across different institutions. One of the more common issues I dealt with was customers trying to link accounts across multiple banks. The verification process can fail silently if you do not have your account numbers ready, which usually means an hour on hold the next morning. Here is what you need to know upfront to avoid that.
The Bank That Works For You Mt Online Banking Tailored To Your Needs A Digital Banking Revolution
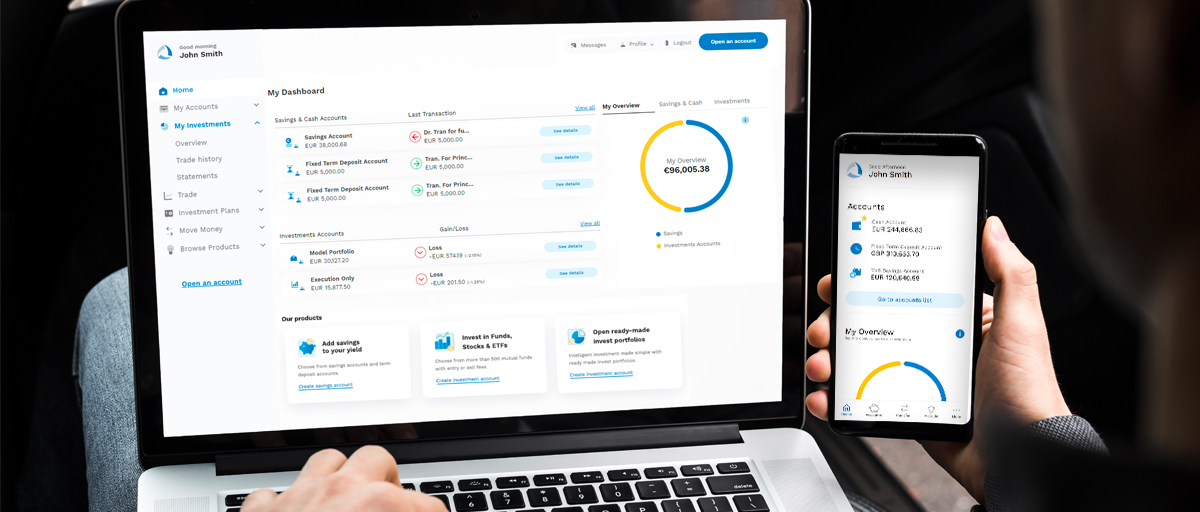
This is about finding a banking solution that actually matches how you handle your money rather than forcing you to adapt to their workflow. A lot of digital banking apps pride themselves on automation and personalization. In practice, the personalization is often based on spending categorization algorithms that miss the mark unless you manually correct them regularly. I encountered this myself last year when a platform I was reviewing categorized recurring payments for a contractor as dining expenses for three months straight. The fix was straightforward but not obvious to most users: you have to go into the settings and redefine the merchant codes. Otherwise, your financial overview is quietly wrong without any alert system telling you so. The core functionality comes down to a few things that most digital banking platforms claim to offer. Account aggregation pulls your balances from different institutions into one dashboard. Bill pay allows you to schedule payments without visiting a branch or mailing checks. Mobile check deposit uses your camera to capture and submit physical checks. Budgeting tools analyze your transaction history to flag patterns. These features exist across virtually every major bank now, so the real question is which execution actually works for daily use. I found that the platforms that feel smooth tend to share a few specific traits. They load account information within two seconds of opening the app. Transaction history does not require five clicks to view anything older than the current week. Notifications are configurable, not permanent surveillance. Most apps give you the option but bury it under layers of settings. Knowing where to find those settings before a problem arises saves considerable frustration later.
One thing nobody talks about is what happens during system outages. Banks routinely schedule maintenance on weekends between 2 AM and 6 AM local time. Transactions submitted after midnight may post to the next business day without explicit notice. I learned this the hard way when a client scheduled a vendor payment for a Saturday morning that did not process until Tuesday because it landed in the maintenance window. The workaround is to schedule all critical payments by Friday afternoon at the latest. The bank will not warn you about impending maintenance in most cases. Security is another area where the gap between marketing and reality is wide. Two-factor authentication should be enabled on every account. Biometric login using your phone's fingerprint or face scan is convenient but not inherently more secure than a strong password paired with 2FA. The real vulnerability is usually reused passwords across multiple financial accounts. If your email gets compromised and you share credentials, your banking becomes the first domino. I recommend using a password manager specifically for financial accounts. It sounds paranoid until it is necessary. Setting up the platform itself typically takes about ten to fifteen minutes. You will need your account number, routing number, and a recent statement to verify ownership during the onboarding process. Some institutions may require you to verify your identity through a separate portal before full access is granted. This is standard procedure and not something to panic about. The verification step exists because regulators require it, not because your account is in danger.
Get the Full Details
Once your accounts are linked, take twenty minutes to review the default settings. Turn off promotional offers if you find them annoying. Set up low balance alerts at a threshold that actually reflects your situation, not the generic suggestion. Configure notification preferences for specific transaction types rather than allowing every single purchase to ping your phone. I have seen people disable notifications entirely and then wonder why they missed a fraudulent charge three weeks later. Balance is a reasonable middle ground. There are limitations that no digital banking platform will advertise. You cannot deposit cash through an app. Large transfers between banks may hit daily limits that require a phone call to increase. Dispute resolution still often requires printing documents and mailing them or visiting a branch in person. If your bank is smaller and does not offer robust dispute processes, you may end up waiting forty-eight hours for provisional credit while they investigate, and recovery is not guaranteed. These are structural issues with how banking operates, not software bugs that a better app can fix. If you want to get the most out of your online banking, spend one afternoon setting it up properly instead of treating it as something to figure out piecemeal over several weeks. The initial investment of time pays off immediately. Most problems I see with customers stem from incomplete setup rather than actual platform failure. Get your security configured first. Then organize your accounts. Then set up alerts and budgeting tools. Follow that order and you will rarely have a reason to call support.