Understanding the S&P Merval and What It Actually Tells You
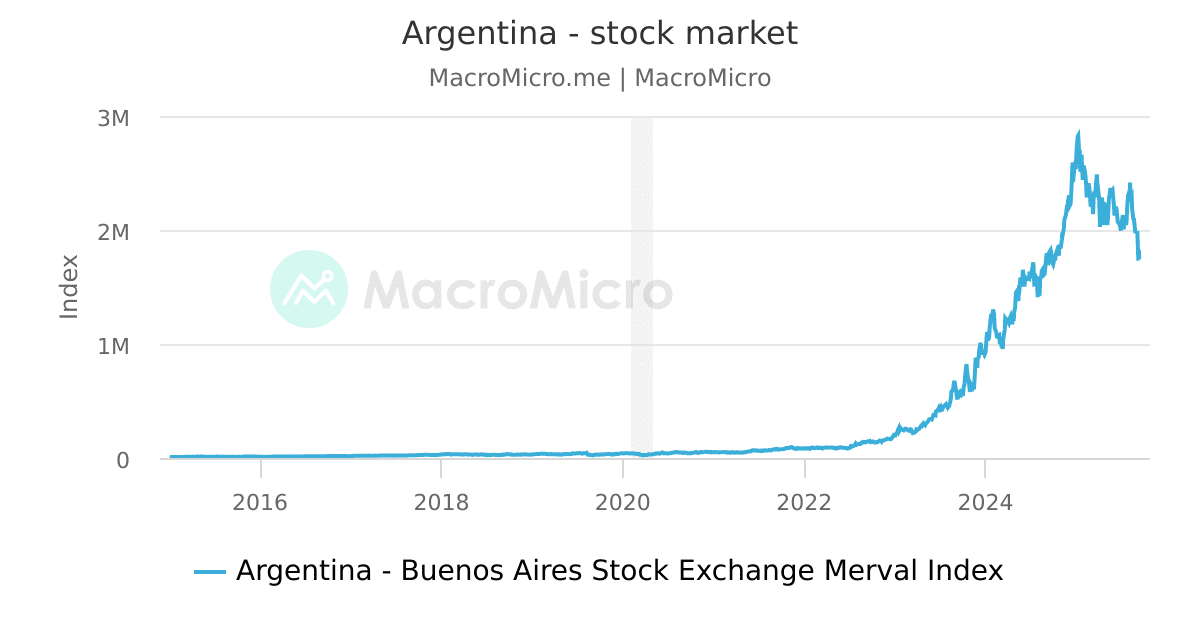
The S&P Merval is the flagship index of the Buenos Aires Stock Exchange, tracking around 30 large-cap stocks listed on the market. Most people look at it and see a single number. The number itself is almost useless without context. Argentina's economic reality makes reading this index fundamentally different from reading the S&P 500 or the FTSE 100. The index doesn't just reflect corporate performance. It reflects currency chaos, inflation expectations, and political risk all at once. When you strip away the noise, the Merval reveals several layers of the economy that official statistics often obscure or distort. The most important thing to understand first is how the index is calculated. It's a free-float adjusted market-cap index denominated in pesos, with a base date of January 1, 1960 at a level of 1,000. That design choice matters because the compounding effect of decades of inflation means the index level is now in the hundreds of millions. A nominal reading of 2,000,000 doesn't tell you whether the market went up or down unless you adjust for the peso's purchasing power. The biggest distortion comes from the gap between the official exchange rate and the parallel market rates. Companies in the index derive revenue from different sources. Some earn primarily in pesos from domestic consumers. Others, like YPF, Arcor, and the major banks, have significant dollar-linked revenue streams or natural hedges through exports and dollar-denominated debt. When the peso devalues, the Merval typically jumps. This isn't because companies are suddenly more productive. It's because the index is denominated in a weakening currency and the constituents include export-oriented firms that benefit from a cheaper peso.
I spent years monitoring the correlation between the MEPC (the parallel dollar rate) and the Merval's daily moves. The relationship is strong but not mechanical. During the 2018-2019 period, the peso collapsed from around 20 to nearly 60 per dollar, and the Merval surged over 300% in peso terms. Meanwhile, in dollar terms, investors lost roughly 40% of their capital. This disconnect is the core complexity anyone analyzing Argentina's economy through its stock index has to confront. The headline number hides the currency destruction underneath it. Another practical issue is the composition of the index itself. The Merval is heavily concentrated in financials, energy, and consumer goods. Banks like Galicia, Supervielle, and Macro make up a significant portion of the weight. When the central bank raises interest rates to combat inflation, bank stocks tend to rise on margin expansion expectations. But this also signals that the broader economy is under stress. The index can be climbing while industrial production contracts, unemployment rises, and real wages fall. That's the paradox of Argentina's equity market. The revaluation mechanism in Argentina adds another layer of complexity. Since the late 1990s, companies have used fiscal revaluation (revaluing fixed assets for tax purposes) to reduce their income tax burden. This creates accounting profits that don't reflect actual cash generation. The Merval includes companies that report strong earnings growth largely because of revaluation gains rather than operational improvement. Without digging into individual company financials, it's easy to misread the index's trajectory.
Here's a specific problem I ran into repeatedly when building models to predict Merval movements. The index has a quirk related to dividend payouts and tax treatment. Argentina imposes a 21% tax on dividend income for residents, but the tax is withheld at source and credited against annual income tax. For foreign investors, the withholding rate can be higher depending on tax treaties. When a major constituent announces a dividend, the stock price drops by approximately the dividend amount on the ex-date. But the Merval's calculation methodology treats dividends differently depending on whether they're classified as ordinary or special. I found that during high-inflation periods, special dividends triggered disproportionately large index adjustments that didn't reflect genuine market value changes. The workaround was to build a custom price return index that stripped out dividend effects and compared it against the official total return version. The divergence between the two became a useful leading indicator of institutional positioning. When the gap widened unusually, it often preceded major market reversals. The inflation adjustment is where most people trip up. Argentina's annual inflation has ranged from 200% to over 300% in recent years. If the Merval rises 50% in a year but inflation runs at 250%, the real return is deeply negative. Smart analysts track the Merval in real terms by deflating it with the IPC (the official consumer price index) or better yet, with the parallel dollar rate as a proxy for purchasing power erosion. The real Merval chart tells a completely different story than the nominal one and is far more useful for understanding whether Argentine equities are actually creating wealth. Political risk introduces another dimension that standard index analysis doesn't capture. Argentina's economic policy has swung dramatically between protectionist capital controls and aggressive liberalization. The Fernández administration maintained strict currency controls that limited dollar access for investors. The Milei administration removed many of those restrictions almost overnight in late 2023. Each policy shift caused violent index movements that had nothing to do with fundamentals. The Merval can gap up 10% in a single session on a presidential announcement and then reverse completely once the initial enthusiasm fades. Trading around policy events requires checking government bulletins and central bank communications directly rather than relying on technical analysis or historical patterns.
Get the Full Details

The liquidity profile of the index constituents is another practical concern. While the 30 stocks in the Merval are the most traded on the exchange, several of them have thin order books relative to their market capitalization. Large orders can move the price significantly. A fund trying to deploy or withdraw $50 million might move an individual stock by 5-8% simply through execution pressure. This means the index level can be somewhat manipulated by large participants during low-volume periods, particularly around month-end or quarter-end when portfolio rebalancing happens. For anyone trying to extract meaningful signals from the index, I recommend focusing on a few specific metrics rather than the headline level. Track the Merval's performance in dollars using the official and parallel exchange rates. Watch the internal breadth of the index — how many of the 30 constituents are making new highs versus new lows. Monitor the volume-weighted average price over 20-day windows to filter out intraday noise. Pay attention to the relationship between the banking sector weight and the overall index, since banks often lead market direction in Argentina. And never ignore the bond market. The Merval and Argentine sovereign bonds traded in dollars (GLBs) often move in opposite directions during crises. When bond yields spike, equities usually sell off regardless of what the index headline suggests. The index also has blind spots when it comes to representing the broader economy. Roughly 70% of Argentine economic activity occurs outside the formal equity market. Small and medium enterprises, the vast agricultural sector beyond the listed exporters, and the informal economy generate little to no representation in the Merval. The index can signal optimism from listed corporations while the manufacturing PMI, retail sales, and employment data paint a harsher picture. This divergence is normal in emerging markets with large informal sectors but it means the Merval should never be treated as a comprehensive barometer of economic health.
Finally, the data infrastructure around the index has improved but still has gaps. Historical data going back several decades exists but the methodology changed at various points, particularly during the 2001 default and the 2018 currency crisis. Pre-2001 data in peso terms is essentially meaningless without adjusting for the multiple currency redenominations Argentina has undergone. The peso was redenominated three times since 1992 — in 1992 (new peso), 2018 (peso argentino, though that never fully materialized), and effectively through inflation adjustments. Always verify the series continuity before running any long-term analysis. The Merval remains one of the most volatile equity indices in the world. Its volatility isn't just risk — it's information. Each swing encodes something about exchange rate expectations, inflation trajectories, and policy directions. The challenge is filtering out the currency noise to find the actual economic signals underneath. Most casual observers never get past the headline number. The ones who dig into the composition, the real returns, and the policy context find a much clearer picture of what's actually happening in Argentina's economy.