How to actually navigate the blue dollar market without losing money
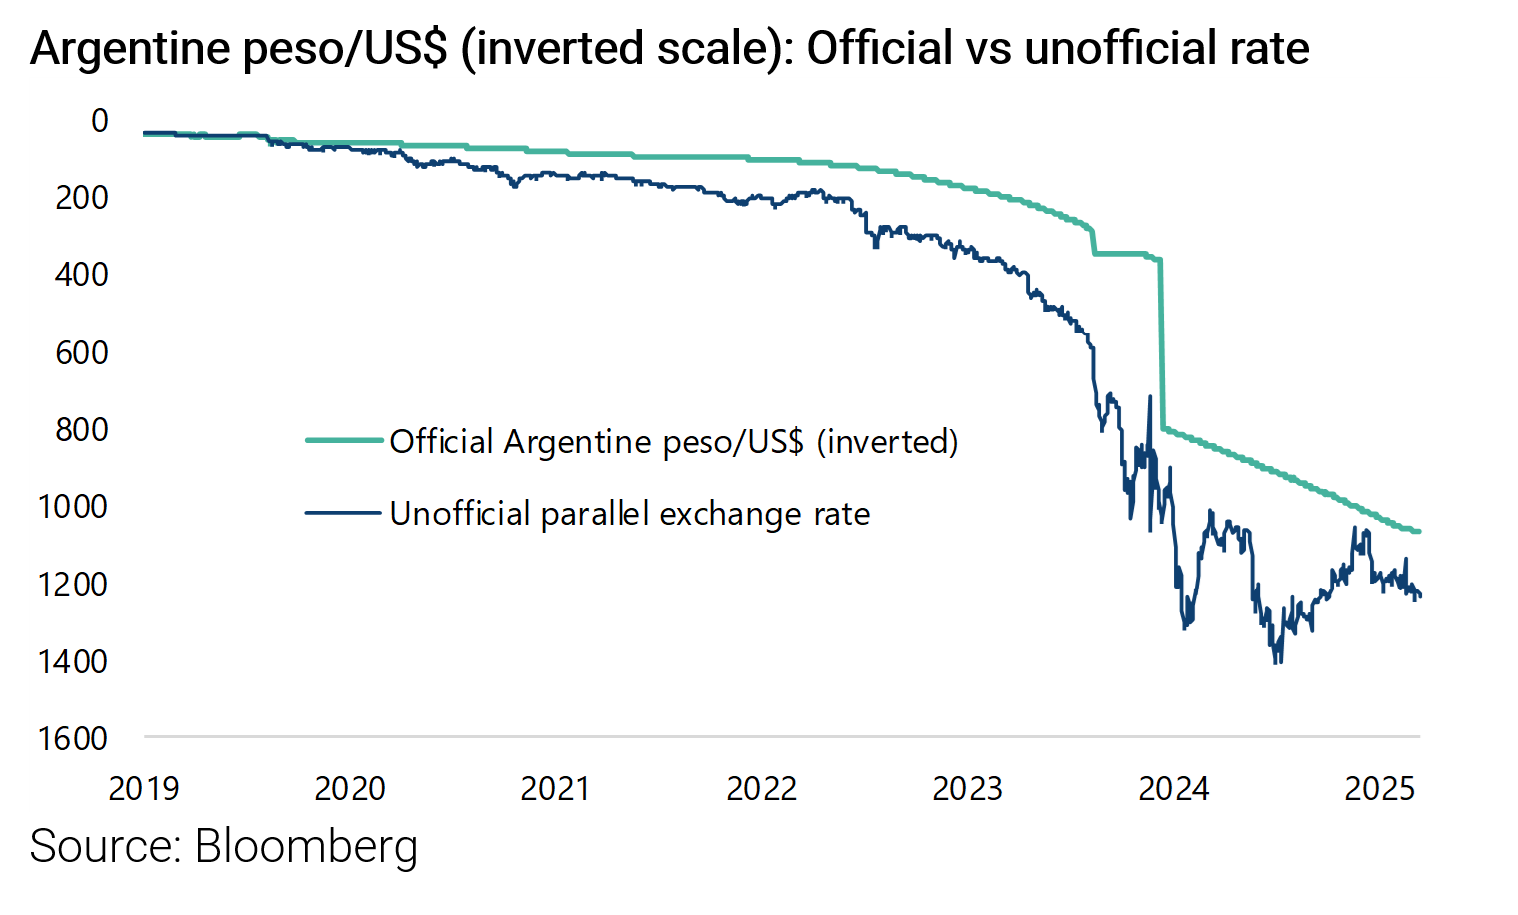
The Argentina dollar exchange rate conundrum understanding the volatile economy is less about understanding and more about surviving. I have been trading these rates since 2019. What works today might not work tomorrow. The system changes enough times per year that any guide claiming to be definitive is lying to you. Most people try to convert USD to ARS and immediately run into the official rate. That rate is essentially theoretical for anyone who needs actual purchasing power in Argentina. The gap between the official rate and the parallel rate has regularly exceeded 200% in recent years. The peso you receive at the official rate buys you roughly a third of what the same nominal amount gets you on the parallel market.
The Argentina Dollar Exchange Rate Conundrum Understanding The Volatile Economy
The blue dollar, known locally as "dólar blue," is an unregulated parallel market rate. It operates through cash transactions in neighborhoods like San Telmo and microfinance websites called "cambios." It is not legal in any formal sense. The Central Bank of Argentina actively suppresses it through regulatory pressure. Yet it persists because the official channel cannot meet demand. The real mechanism here is the MEP and CCL rates. These are legal financial instruments that produce a rate closer to the blue but trades through the stock exchange. A Mexican peso to dollar conversion through these channels follows the same logic of spread arbitrage. You buy pesos with dollars on the stock exchange, then sell those pesos in the local market. The rate lands somewhere between official and blue. I learned this the hard way in early 2023. A client needed to move approximately 40,000 USD into Argentina for a commercial transaction. I routed everything through a traditional bank expecting the CCL rate. The bank executed at a blended official rate with a 12% withholding tax and a secondary exchange fee. The effective rate was roughly 65% worse than the blue rate available that same morning at 9 AM. The difference cost us about 8,000 USD in lost value. We ended up splitting the difference and the client absorbed half the loss.
After that, I switched to using the MEP route exclusively for any transaction over 10,000 USD. The process takes about 48 hours instead of the instant settlement banks pretend to offer. You need a brokerage account with Argentine stock market access. Most international brokers do not support this. Local brokers like Balanz or Bultra work fine. The execution itself is mechanical: buy AL30 or GGAL bonds with USD, then sell the pesos generated from the settlement at the prevailing MEP rate. For smaller amounts below 5,000 USD, the blue physical market remains faster but carries counterparty risk. I usually work with a fixed contact who has been operating for over a decade. The transaction takes about 15 minutes in person. You hand over dollars, you receive pesos immediately. No paperwork. No trace. This is the problem with this approach. It leaves no audit trail. If you are audited, you have no documentation beyond a handwritten note that means nothing to any government agency. The Jota rate deserves a mention here. It is another legal alternative that emerges during periods of capital control tightening. The Jota allows you to purchase dollars through a specific bond instrument on the exchange. The rate is competitive but requires holding positions for at least 30 days in many cases. That lockup period eliminates it for most commercial use cases where speed matters.
Get the Full Details
There is a significant limitation nobody talks about. All these parallel rates move on the same day as major policy announcements. I have watched the blue rate shift by 8% between 8 AM and 10 AM on days when the government announced new exchange controls. If you are executing a large trade and the rate moves against you by even 3%, your entire margin disappears. This happens routinely. The market prices in speculation before any official statement lands. Another issue is the daily volume ceiling. Most casas de cambio impose informal limits ranging from 3,000 to 15,000 USD per transaction depending on the vendor. Splitting a larger amount across multiple vendors introduces its own complications. You need to coordinate timing carefully or the rate will diverge between the first and last transaction. A 2% drift between vendors is not unusual during volatile sessions. The workaround I use for amounts above 20,000 USD is layering. I split the total across three channels simultaneously. Two-thirds goes through the MEP route at the broker. One-third goes through a trusted blue contact in two separate visits to avoid ceiling limits. The MEP portion settles in 48 hours while the blue cash arrives same day. This exposes me to rate divergence between channels but guarantees liquidity when the total amount is large. The tradeoff is worth it when the alternative is losing the entire window.
Monitoring requires more than checking a single website. Blue rates vary by source. Some sites report optimistic rates that do not reflect actual executable prices. I track the rate through three independent sources and execute when the spread between them compresses below 1%. When spreads widen beyond 2%, the market is signaling uncertainty and I hold off until it settles. Payment methods matter as much as the rate itself. Cash in good condition is non-negotiable for blue transactions. Bills that are torn, stained, or from series older than 2015 get rejected or discounted at a rate of 10 to 15% below the posted price. I keep a stack of crisp recent-series dollars specifically for these transactions. The discount applies to individual bills too. A single bill can tank an entire transaction if the contact notices it during inspection. For digital transactions, the situation is worse. Cryptocurrency stablecoins like USDT offer speed but the OTC desks charging fees between 3% and 7% on conversion eat into the rate advantage. The final effective rate after fees usually lands between the official and CCL rates, never beating the MEP execution. The only scenario where crypto makes sense is when you need settlement within hours and cannot open a local brokerage account.
The biggest pitfall beginners fall into is focusing exclusively on the headline rate and ignoring taxes. The 30% tax on financial operations, the percepción de IVA for certain transactions, and the Ganancias withholding for residents can add 40% or more to your effective cost. A favorable blue rate of 800 ARS per USD becomes 1,120 ARS per USD after taxes. A less favorable MEP rate of 750 ARS per USD with lower tax exposure may actually deliver more pesos in hand. Calculate the after-tax delivered amount before committing to any channel. The math is simple but most people skip it because they are focused on the headline number. I do the calculation in a spreadsheet before every trade. It takes 90 seconds and has saved me from several bad executions. The system will keep changing. New controls appear, old ones lift, rates gap overnight. Any strategy that worked last quarter may be broken today. The only constant is the gap between official and parallel rates. As long as that gap exists, the arbitrage opportunities exist. Your job is to execute with enough speed and enough awareness of the full cost structure to capture a slice of it without losing everything to taxes, fees, or a surprise policy shift.