Apple's Valuation From The Inside
Most people talk about Apple's net worth like it's a static number you can look up and file away. It's not. It moves constantly. During my years working around equity analysis and startup funding rounds, I've watched people get tripped up by looking at a single snapshot instead of understanding the mechanics behind the number. The figure you see reported for Apple's net worth is typically a representation of its market capitalization, which is calculated by multiplying the current share price by the total number of outstanding shares. That's straightforward enough. The tricky part is that this number includes assumptions about future cash flows, consumer behavior, product cycles, and macroeconomic conditions that change on a regular basis. Apple's most recent reported market cap has fluctuated between roughly $2.5 trillion and $3.4 trillion over the past few years, depending on where the stock sits on any given trading day. The difference between $2.5 trillion and $3.4 trillion sounds like a small percentage move, but we're talking about nearly a trillion dollars in perceived value shifting back and forth. That kind of swing doesn't come from major changes to the underlying business. It comes from slight adjustments in earnings expectations, interest rate movements, and sector rotation flows from institutional investors.
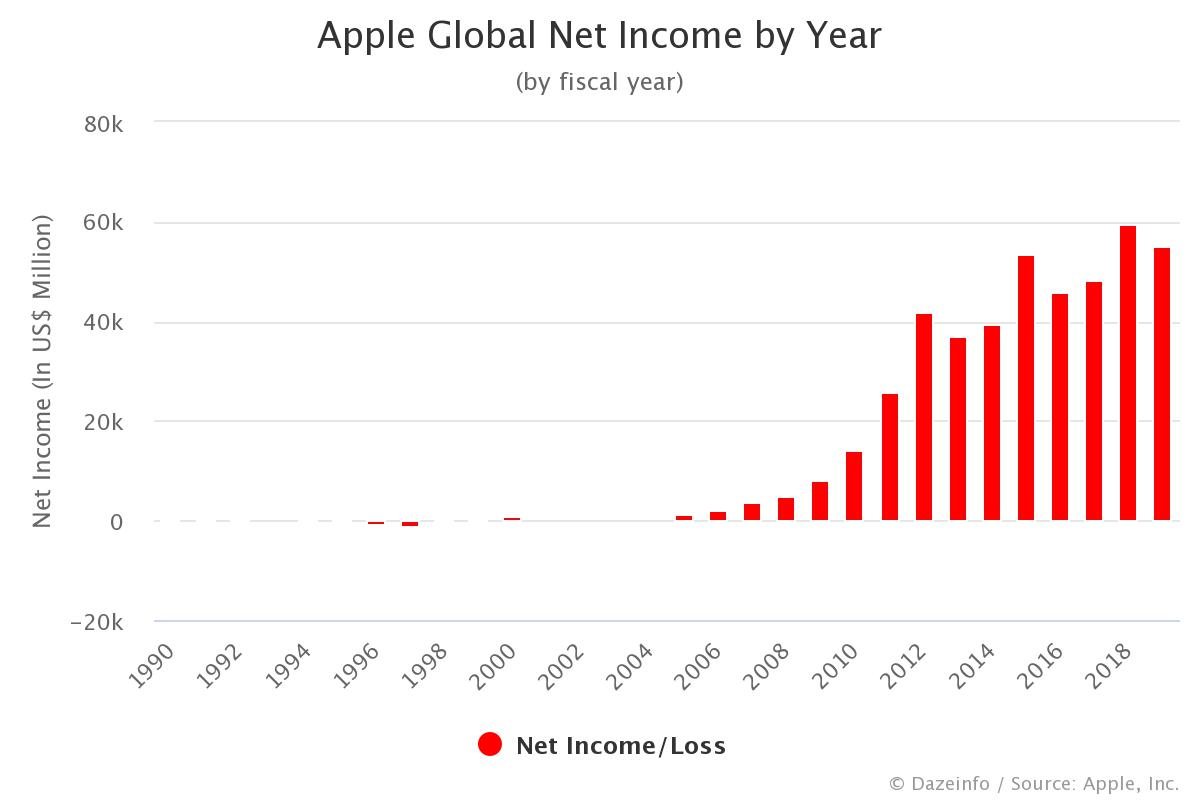
Here's something most beginner investors miss: market cap is not the same as net worth in the traditional accounting sense. If you go to Apple's balance sheet and subtract total liabilities from total assets, you get shareholders' equity, which is a fundamentally different number. Apple's shareholders' equity sits in the tens of billions, while its market cap is in the trillions. The gap between those two numbers represents the market's expectation of future earnings power, brand premium, ecosystem lock-in, and intangible value that never appears on a balance sheet. Another thing people overlook is the share buyback mechanism. Apple has been aggressively repurchasing its own stock for years. When a company buys back shares, the total number of outstanding shares decreases, which mechanically increases earnings per share even if total earnings stay flat. This means Apple's market cap can grow partly because of capital allocation decisions rather than purely operational growth. I've seen analysts miss this distinction and attribute stock price appreciation entirely to business fundamentals when a significant portion was actually driven by buybacks reducing the share count. During one particular quarter when I was modeling valuation scenarios for a client portfolio, I ran into a problem where the trailing twelve-month earnings figures were giving a misleading picture because of one-time charges and restructuring costs. The fix was straightforward once I knew where to look: I switched to using adjusted non-GAAP earnings and factored in the annualized impact of the buyback program on the diluted share count. The resulting valuation multiple was about 12% lower than the headline GAAP earnings suggested. That gap matters when you're deciding whether a stock is fairly valued or stretched.
There are also limitations to relying on market cap as a proxy for Apple's actual financial health. Market cap is driven by sentiment and liquidity flows, not just fundamentals. A sudden shift in Federal Reserve policy can compress or expand multiples across the entire technology sector regardless of what any individual company is actually doing operationally. I've watched Apple's valuation multiple expand purely because rates dropped, and contract when they rose, even during periods where iPhone sales and services revenue were performing reasonably well. If you want a more grounded sense of Apple's actual financial position, looking at the balance sheet metrics makes more sense. Free cash flow, debt-to-equity ratio, current ratio, and return on invested capital tell you something about the underlying business that market cap alone doesn't capture. Apple generates massive free cash flow, carries manageable debt, and maintains strong liquidity. Those are the metrics that matter if you're trying to understand the company beyond the headline number.
Get the Full Details