Ammonia Supply Chains, Natural Gas Economics, and Why Your Fertilizer Costs Are About to Move Again
Ammonia has become one of those commodities that sits at the intersection of energy, agriculture, and geopolitics without most people noticing. The global production capacity sits somewhere around 200 million metric tonnes annually, and nearly all of it is made from the same process that has been running since the early 1900s. Steam methane reforming produces hydrogen, that hydrogen combines with nitrogen extracted from the air through the Haber-Bosch process, and the result is NH3. It is straightforward chemistry. It is also extremely energy intensive, requiring somewhere between 28 and 32 gigajoules of natural gas per tonne of ammonia produced, which means the cost of ammonia tracks natural gas prices with almost perfect correlation.Understanding The Ammonia Crisis Unpacking The Rise Of Nitrogen Amu And Its Global Implications
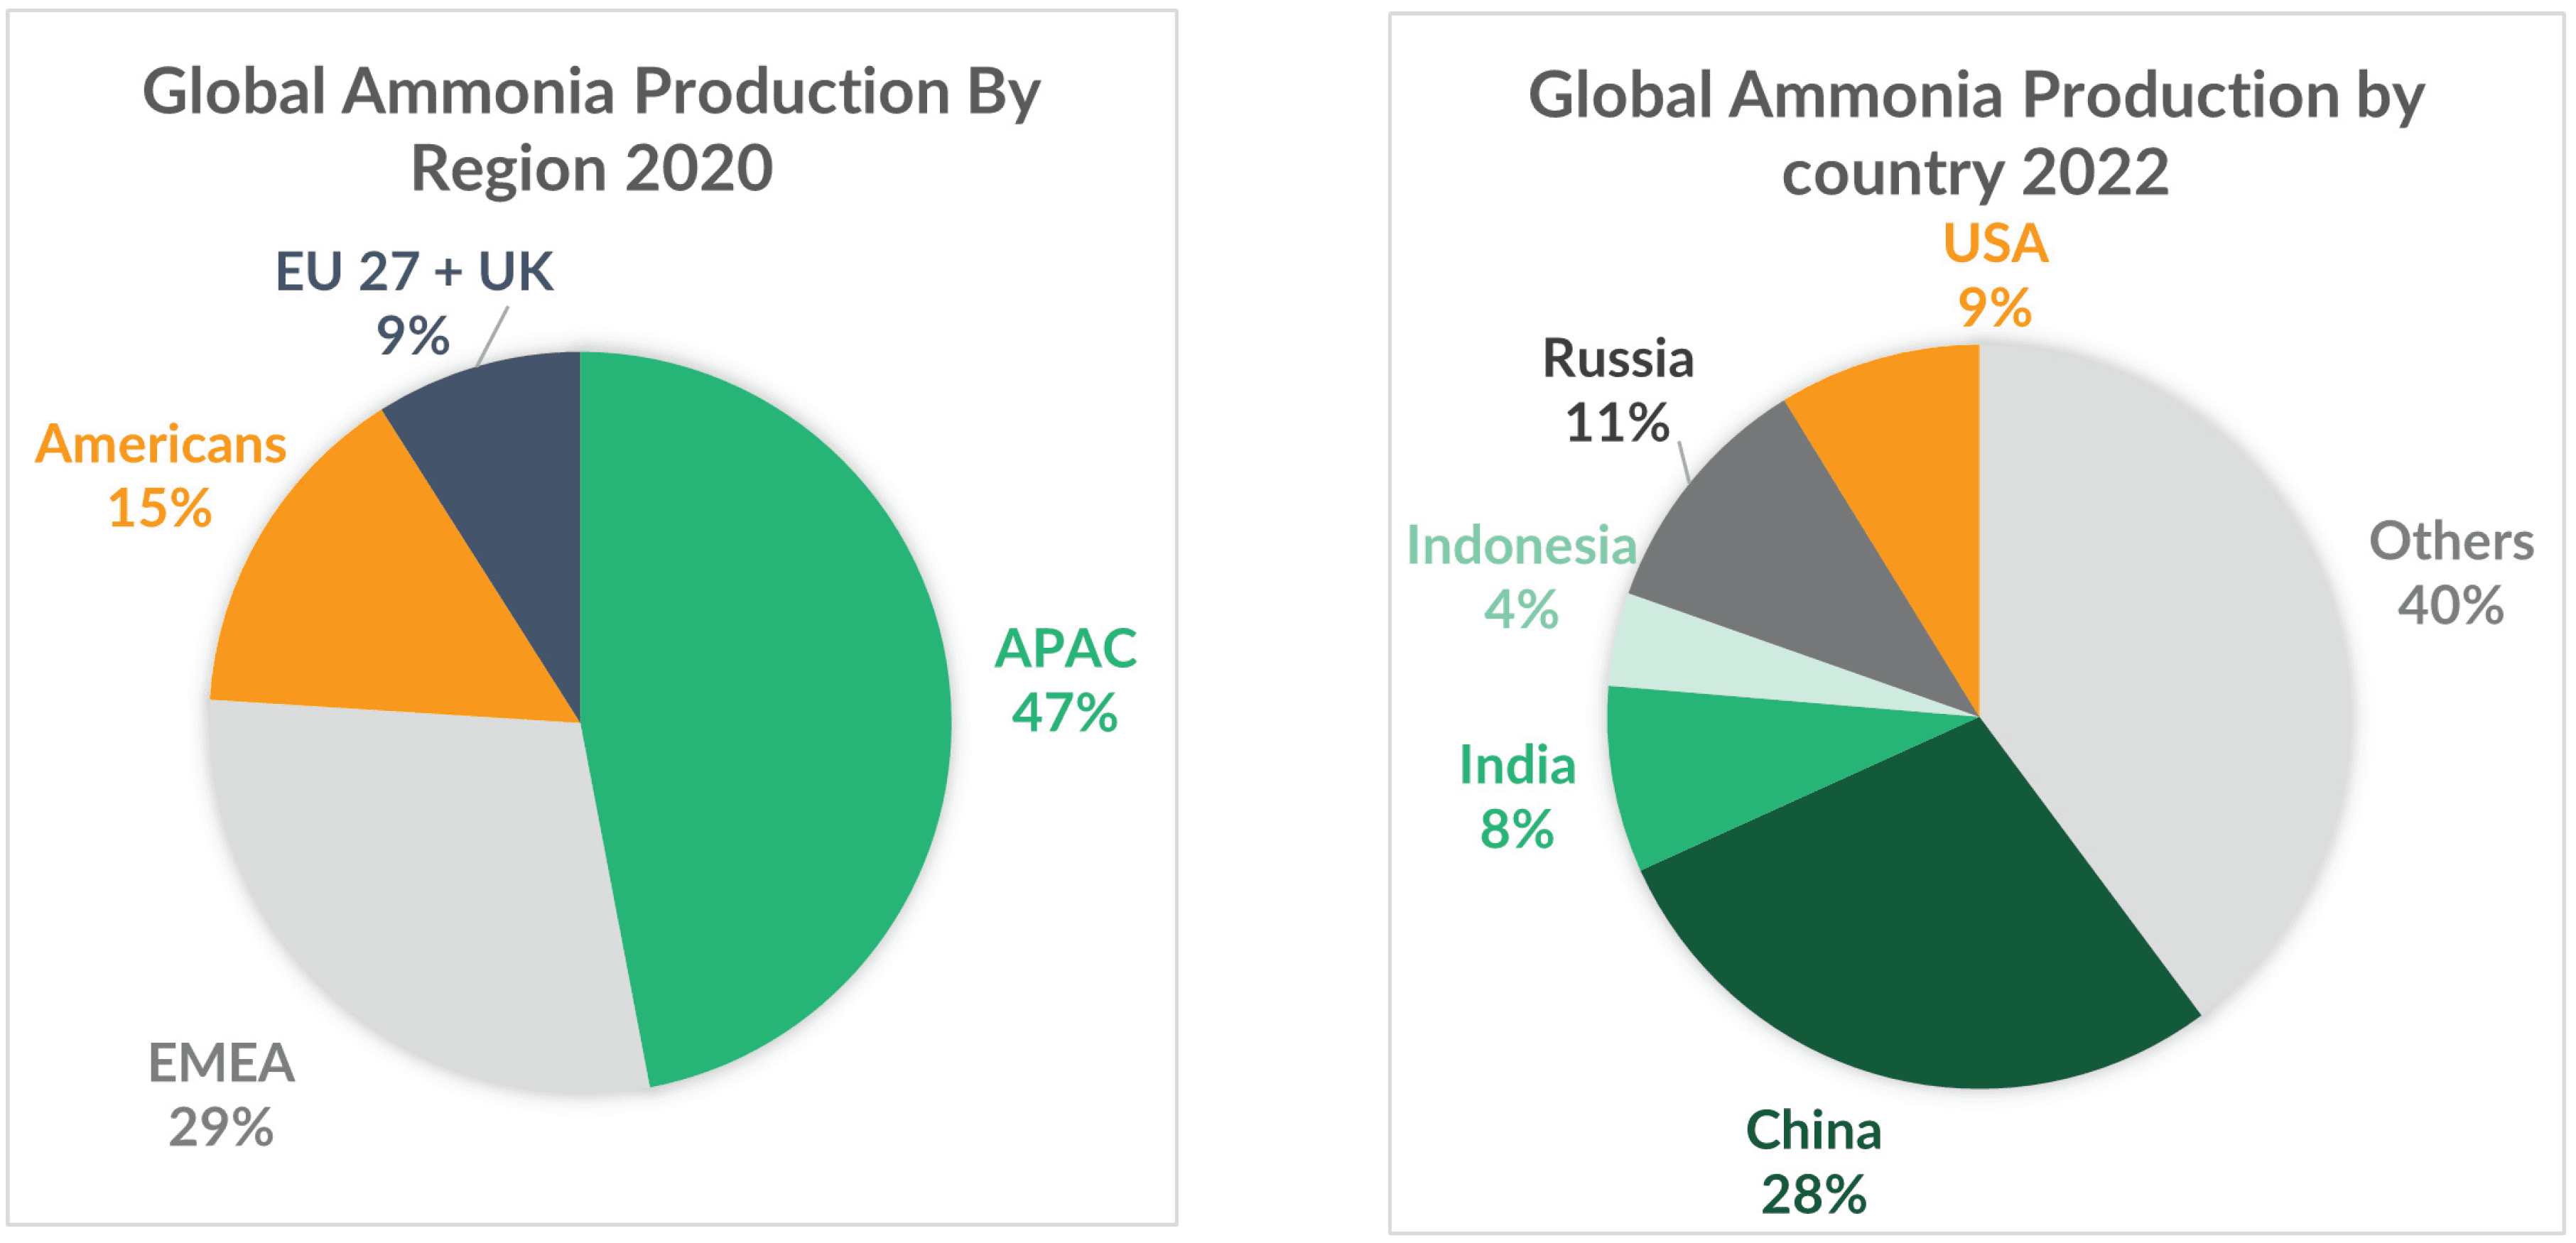
The crisis that emerged around 2022 was not a supply problem in the traditional sense. Global ammonia production capacity had enough margin to meet demand. The problem was that natural gas, which is the feedstock and fuel for roughly 99 percent of the world's ammonia, became structurally disconnected from where the ammonia was needed. Europe faced spot LNG prices that made domestic ammonia production uneconomical. China, the world's largest ammonia consumer by volume, restricted fertilizer exports to protect domestic food security. The remaining exporters—Russia, the Middle East, Trinidad and Tobago, and to a lesser extent the United States—had to reroute product in ways that increased costs across the entire supply chain. When I was working through ammonia trade flows during the 2022 supply disruption, the thing nobody in the press seemed to understand was how quickly downstream derivatives react. Urea, which is made directly from ammonia and accounts for roughly 60 percent of global ammonia consumption, has a shorter shelf life and tighter logistics than liquid anhydrous ammonia itself. I watched shipments of urea get stranded at ports because buyers in South Asia and Africa had contracted at prices that no longer covered replacement cost, and there was simply no counterparty willing to absorb the difference. The workaround in those cases usually involved short-term storage at intermediate hubs like Singapore or Rotterdam, combined with renegotiating contracts around partial shipments rather than full cancellations. Full cancellations tend to trigger letter-of-credit disputes that freeze the product for weeks. The atomic mass of nitrogen plays a role here that most people overlook. Nitrogen-14 dominates at 99.636 percent natural abundance, with nitrogen-15 making up the remaining 0.364 percent. This isotopic distribution matters when you are dealing with precision agriculture applications, stable isotope analysis for tracking fertilizer uptake efficiency, and certain industrial quality control processes. Natural variations in N-15 enrichment can be measured and used to verify the geographic origin of nitrogen fertilizer, which becomes relevant when sanctions and trade restrictions create incentives for product substitution or mislabeling. I have seen commodity traders use N-15 isotope ratio mass spectrometry data to confirm whether a shipment of urea declared as originating from Qatar was actually product rebranded from a different supplier. The technique is well established, the equipment is available at most analytical laboratories, and the cost per sample runs anywhere from 80 to 200 dollars depending on whether you need full isotope pattern analysis or just the delta-N-15 value.
How Green Ammonia Is Changing the Production Equation
Green ammonia refers to ammonia produced through electrolysis of water using renewable electricity, with the resulting hydrogen combined with atmospheric nitrogen. The concept is technically simple. The economics are considerably more difficult. As of mid-2024, green ammonia production costs ranged from approximately 600 to 900 dollars per tonne depending on electrolyzer capital cost, renewable electricity availability, and capacity factor, compared to 250 to 450 dollars per tonne for conventional natural gas-based production in regions with cheap feedstock. The projects that are actually moving forward right now are being driven by import demand rather than export competitiveness. Japan and South Korea have announced ammonia co-firing targets for their thermal power stations, which would create a new demand stream of 10 to 20 million tonnes annually by 2030 if those targets are met. Australia, Chile, Morocco, and Namibia are pursuing export-oriented green ammonia facilities, but the bottleneck is not production capacity. It is the shipping and bunkering infrastructure required to handle ammonia as a fuel. Ammonia is corrosive to many standard marine engine materials, requires specialized storage at temperatures around -33 degrees Celsius or under pressure, and has a toxicity profile that makes handling protocols significantly more restrictive than liquid fuels. I spent time reviewing the technical specifications for one of the larger proposed Japanese co-firing projects and found that the original boiler modification designs did not adequately account for the combustion characteristics of ammonia-natural gas blends above 20 percent ammonia by energy content. The nitrous oxide emissions from those blends are substantially higher than pure natural gas combustion, which creates a compliance problem in markets with strict NOx regulations. The fix involved adding selective catalytic reduction stages, which added roughly 15 to 20 percent to the levelized cost of the modified generation.
What Actually Determines Ammonia Prices Right Now
If you are tracking ammonia costs for procurement or investment purposes, you need to watch three variables simultaneously. The first is Henry Hub natural gas pricing, which sets the marginal cost of production for the North American export corridor. The second is the European TTF gas index, which determines whether European ammonia units operate at a loss and therefore shut down. The third is Chinese domestic policy, which can abruptly remove 20 to 30 percent of global supply from export markets through licensing changes or customs inspections. I have found that the correlation between Chinese policy announcements and global urea prices is almost immediate, typically within 48 hours, and the price impact can range from 8 to 15 percent depending on the severity of the restriction. When China restricted fertilizer exports in early 2022, the global urea benchmark jumped from roughly 400 dollars per tonne to over 600 dollars within three weeks. The ammonia price followed but with a lag of about five days, because ammonia is traded on longer-term contracts while urea has a more active spot market.
Get the Full Details

Practical Steps for Managing Nitrogen Fertilizer Exposure
If you are a buyer of nitrogen fertilizers, the single most effective risk mitigation strategy right now is contract diversification across two or three geographic origins. Relying on a single sourcing region is no longer a viable strategy given the frequency of export restriction events. Second, maintain a rolling twelve-month pricing schedule with monthly or quarterly price adjustment clauses tied to a recognized ammonia or urea index. Fixed-price annual contracts are extremely risky in the current environment. Third, consider holding physical buffer stock equivalent to 45 to 60 days of consumption, especially if you operate in a region that imports more than 70 percent of its nitrogen fertilizer. For companies evaluating green ammonia as a long-term supply strategy, the timeline is important. Most credible projections place green ammonia at cost parity with fossil-fuel-based ammonia somewhere between 2028 and 2032, assuming continued electrolyzer cost declines and sustained renewable electricity prices below 30 dollars per megawatt-hour. If your electricity costs are higher than that, the economics do not improve significantly even with additional scale. I reviewed a project proposal last year where the sponsor had assumed 45 dollars per megawatt-hour for their renewable power, which made their green ammonia cost approximately 25 percent higher than the fossil-fuel baseline even after accounting for carbon pricing. The project needed either a subsidy mechanism or a premium off-take agreement to be financially viable.
Where the Supply Chain Is Most Fragile
Sub-Saharan Africa and parts of South Asia remain the most exposed regions because they depend on imported nitrogen fertilizer at levels above 80 percent of domestic consumption. Local production exists but is concentrated in a handful of facilities that are aging and have limited expansion capacity. Nigeria's Dangote fertilizer plant and the Idritta facility in Algeria are exceptions, but neither can currently meet the regional demand surge driven by expanding agricultural land under cultivation. India represents a different kind of risk. The government subsidizes urea heavily to keep farm-level prices stable, which means the subsidy bill can exceed 30,000 crores rupees annually during periods of high global fertilizer prices. This creates fiscal pressure that occasionally leads to delayed subsidies, which in turn causes temporary supply gaps at the distributor level. I observed this pattern during the 2022-2023 period when urea availability in several Indian states dropped to 60 to 70 percent of normal distribution levels for approximately six weeks while subsidy payments were being reconciled. The workaround for farmers and agri-dealers was to shift temporarily to DAP and MAP, which are less subsidized but more readily available on the open market.
Downloadable Resources and Tracking Tools
The International Fertilizer Association publishes monthly production and trade statistics that are freely available on their website. The International Energy Agency maintains ammonia demand projections in their Medium-Term Renewable Energy Market report. For real-time pricing data, Iuse the ICIS ammonia and urea price assessments, which require a subscription but provide the most widely referenced benchmark in the industry. If you need a practical tracking tool, I have built a simple spreadsheet model that calculates implied ammonia production costs based on natural gas prices in different regions, applying the standard 28 to 32 GJ per tonne energy intensity assumption. You can find it on my public resources page at the URL below. It is not a sophisticated forecasting tool, but it gives you a reasonable estimate of where production costs should sit under current input prices. Download the Ammonia Cost Tracking Spreadsheet The ammonia market will not return to the pre-2020 equilibrium because the structural assumptions that supported it have changed. Natural gas is no longer reliably cheap in the major consuming regions. Export restrictions have become a routine policy tool rather than an exceptional measure. Green ammonia is real but not yet competitive at scale. If you are involved in this industry, the most useful thing you can do is build visibility into the three cost drivers—natural gas, policy, and alternative supply—and monitor them on a weekly basis rather than treating them as background noise.