How the Amazon Rewards Credit Card Actually Functions in Practice
The Amazon Rewards Visa Signature Card from Chase works differently than most people expect. You earn points, not cashback, and those points have a narrow ecosystem they live in. If you understand that constraint upfront, the card makes more sense. Otherwise you will end up frustrated by limitations that nobody warns you about.The Amazon Chase Card Payment Revolution How Does The Amazon Credit Card Actually Work In 2024
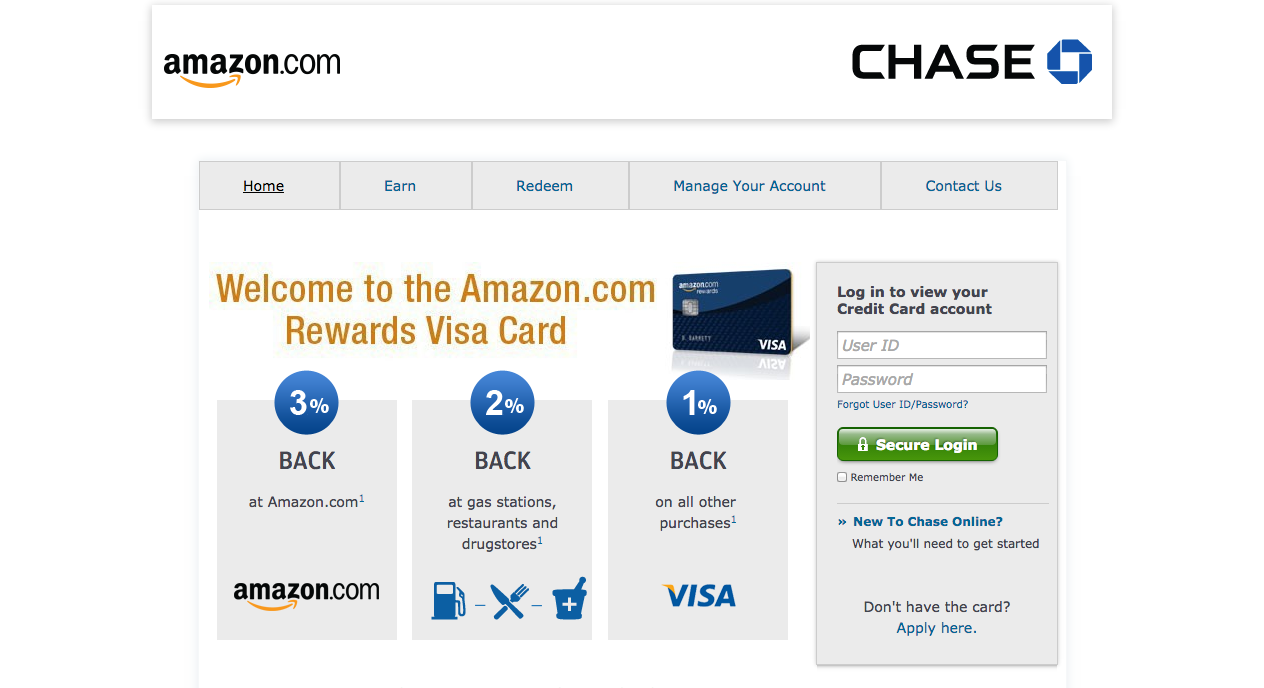
Earning structure: You get 5% back on Amazon purchases when you use the card, 2% at Whole Foods and restaurants, and 1% everywhere else. That is the headline. What people miss is that 5% only applies if you have an active Amazon Prime membership attached to your account. Without Prime, it drops to 1%. I learned this the hard way in 2023 when my Prime membership lapsed for two months during a billing mix-up. My Amazon purchases during that window earned zero extra points. Chase does not send alerts about this linkage breaking. You just lose the 5% category silently. The rewards are called Amazon Coins, not Chase Ultimate Rewards. That distinction matters because these points cannot transfer to hotel or airline partners. They also cannot be redeemed for statement credits toward non-Amazon purchases. The redemption path is almost entirely locked to Amazon.com, Amazon Music, or physical gift cards that you can use broadly. Gift card redemption essentially converts your points into cash-equivalent store credit at a rate of roughly 1 cent per point.
The Application and Approval Process
Chase uses their standard 5/24 rule for eligibility. If you have opened five or more personal credit cards across any issuer in the past 24 months, you will be automatically declined. This is not negotiable. Chase does not waive this rule for anyone, including people with existing Chase products. I know because I was declined once and spent about forty minutes on the phone trying to find an exception. There is none. The representative just read from a script and apologized twice. The credit limit on this card typically ranges from $500 to $5,000 for new applicants, depending on credit profile. The APR is variable, currently sitting around 20.99% to 29.99%. There is no annual fee, which is the main selling point. The card also offers 10% back on eligible Amazon store cards on first purchases for qualifying cardholders. That promotional window usually lasts ninety days from account opening.
Redemption Mechanics
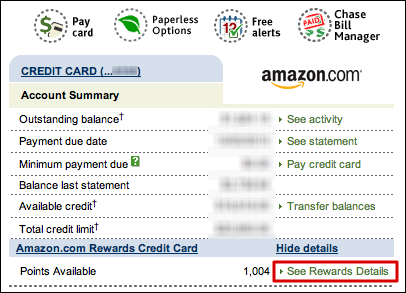
Here is where things get specific. To redeem points at checkout, you need to link your Amazon account to your Chase rewards profile. Navigate to chase.com/rewards, sign in, and connect your Amazon account. Once linked, your points balance appears as a payment option during Amazon checkout. You can apply partial or full redemption. The minimum redemption amount is 25 points, which equals $0.25 toward eligible purchases. I encountered a specific issue last year where my points showed as available in my Chase dashboard but did not appear as a redemption option at Amazon checkout. The problem was that my Amazon account email did not exactly match the email on my Chase account. Even a single character difference, like a period or plus sign, breaks the linkage. The workaround was deleting the existing connection and recreating it with the exact same email address I used for both accounts. Points appeared within twenty minutes of re-linking.
Get the Full Details
The Point Valuation Reality
When you redeem directly for Amazon purchases, each point is worth approximately 1 cent. That is your baseline value. Redeeming for gift cards to other retailers keeps the same 1-cent value. There is no bonus redemption category that boosts value beyond that floor. Some people attempt to maximize by purchasing high-volume items like electronics, but the math does not change. You still get 1 cent per point regardless of what you buy. A common mistake is assuming the 5% back equals 5 cents per point. It does not. The 5% is calculated on spending, and then those earnings convert to points at the standard rate. So spending $100 at Amazon earns you 500 points, which you then redeem as $5 off a future purchase. The effective return remains 5% of the original spend, not a higher point value.
Downsides You Should Know About
The biggest limitation is the redemption lock-in. If you earn points on this card but regularly spend elsewhere, you are essentially forced to route some of your daily spending through Amazon to make the card worthwhile. That is not always practical. For example, I found myself buying items I did not need from Amazon just to utilize earned points, which negated any benefit. The points expired after ten years of account inactivity, but earning them and never using them is far more common than expiration. Another practical issue: Chase does not offer mobile wallet bonuses or rotating category activation for this card. Many competing cards from Capital One and Citi let you activate quarterly categories or earn bonus points through their apps. The Amazon card is what it is. No optimizations possible. If you do not shop at Amazon regularly or do not maintain a Prime membership, this card loses most of its value proposition. In that case, a no-annual-fee card like the Chase Freedom Flex or Citi Double Cash would likely serve you better. The Amazon card is a tool, not a general-purpose solution. Use it where it applies and move on.
Practical Tips That Actually Matter
Keep your Prime membership active and verify the linkage between Chase and Amazon quarterly. Log into your Chase rewards account and confirm the connected Amazon status shows as linked. If it does not, reconnect immediately before making a large purchase. Pay your balance in full every month. The APR on this card is high, and carrying a balance eliminates any reward benefit within weeks. I ran the numbers once: a $1,500 balance at 25% APR costs approximately $31.25 per month in interest. That wipes out about six months of 5% rewards on $1,000 in Amazon spending. Do not apply for this card if you are close to hitting the 5/24 threshold. The hard inquiry alone can be wasted if you already have other Chase products you are considering. The card is straightforward, but the approval criteria are rigid. Plan accordingly.

The system works as advertised. It is just narrower than most people assume when they first apply. If your spending aligns with Amazon and Prime, it is a solid no-fee option. If it does not, the rewards structure stops being attractive very quickly.