What You Actually Pay Each Month For A Car Right Now
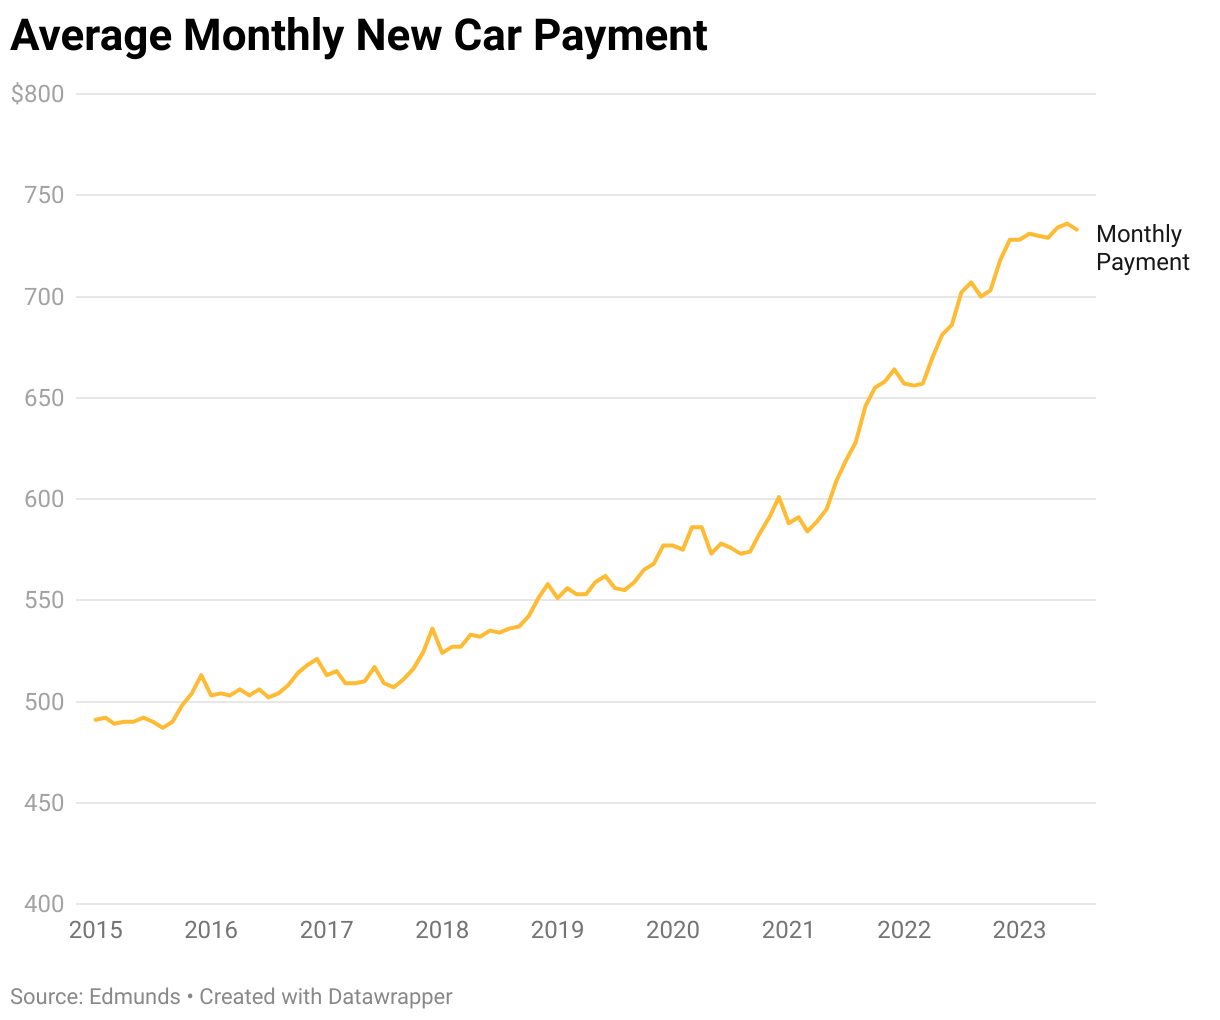
The data doesn't lie, and it isn't pretty. Average new car payments have climbed well past the $700 mark for most borrowers, with many landing in the $800 to $900 range once you factor in the interest rates banks are charging today. Used car payments aren't exactly a relief either. The median used vehicle loan runs around $530 a month, which sounds manageable until you look at what that payment actually buys you. A lot of people are taking out loans for cars that are ten years old or newer, paying rates that often exceed 8 percent while getting barely any vehicle for their money. I ran the numbers for a client last spring. He wanted a reliable daily driver with under 60,000 miles on it, budget capped at $450 a month including insurance. What he actually found were mostly high-mileage trade-ins with unknown service histories, or brand-new entry-level models that pushed his payment north of $650 once the loan terms stretched to 72 or 84 months. The gap between what people think they can afford and what the market actually offers has been widening for a while now.
The Alarming Reality Of Average Car Payments In 2025 A Financial Burden For Millions
This isn't just a numbers problem. It's a structural one. The average loan term hit 68 months in late 2024 and has barely budged since. That means you're locked into a payment for nearly six years. Most people roll their old auto loan balance into a new one without thinking twice about it. I see this constantly in my work. Someone trades in a car that still has $12,000 left to pay off, adds a $25,000 new vehicle, and ends up owing $37,000 on a car that will depreciate to half that value within four years. The negative equity stacks up fast. Interest rates are the other piece nobody wants to talk about comfortably. Even borrowers with excellent credit are seeing rates between 6 and 9 percent on new cars and 9 to 14 percent on used vehicles. A few years ago, 3 percent was normal. The math changes completely when you're paying double the interest on the same loan amount. Take a $30,000 loan at 3 percent over 60 months versus 8 percent over 72 months. The first one costs $537 a month with about $1,090 in total interest. The second one costs $471 a month but balloons to $8,734 in interest over the life of the loan. Your monthly payment drops, but you pay nearly eight times more in interest. I had a case recently where a customer came in desperate. She was bleeding $200 a month from a loan roll. Her previous car payment was $520, but after trading it in with negative equity and financing the difference into a new loan at a higher rate, her payment jumped to $720. She didn't realize what had happened until her third missed payment. We restructured it by having her pay down the principal on the older loan before trading, which cost her an extra $400 out of pocket upfront but saved her about $1,200 over the remaining life of the loan and kept her payment closer to what she could actually sustain.
Why Payments Keep Climbing When Incomes Don't
Car prices rose sharply during the supply chain disruptions of 2021 through 2023. Dealerships realized they could move inventory at higher margins and they kept those margins even after supply normalized. The transaction price of a new car averaged over $48,000 last year, up from roughly $38,000 in 2019. That average doesn't include taxes, fees, or the add-ons dealers love to slip in. If you leave the lot with $3,000 in documented extras like extended warranties and protection packages, your loan amount jumps and your payment jumps with it. Loan products themselves have changed. The 72-month and 84-month loans used to be considered risky by many lenders. Now they're standard. Some credit unions and online lenders won't touch loans over 60 months anymore, but most big banks and subprime lenders are fine with terms up to 84 months. The problem is simple. Extending the term lowers your monthly payment, which makes a car look affordable that otherwise wouldn't be. But it also means you owe more for longer, pay more in total interest, and sit in negative equity for years instead of months. Insurance costs have added another layer. Comprehensive and collision coverage premiums rose significantly across the board. A lot of that ties back to repair costs. Modern vehicles carry more electronics, sensors, and specialized materials. A minor fender bender that would have cost $800 to fix five years ago now runs $2,500 or more. Insurance companies pass those costs to drivers. If you're financing a car, you're required to carry full coverage, which means you're absorbing those premium increases directly into your monthly budget alongside your loan payment.
Get the Full Details

What You Can Actually Do About It
Buy a car that already has a loan paid off or close to it. The best cars financially are the ones you own outright or the ones you can pay cash for. That's not always realistic, but it's worth being honest about. If your monthly transportation budget including insurance, fuel, maintenance, and loan payment can't handle a car payment above $400, then you need to adjust either your budget or your expectations about what kind of car you're shopping for. Shorten the loan term if you can. A 60-month loan is almost always cheaper in total dollars than a 72 or 84-month loan, even if your monthly payment is slightly higher. Try to keep it under five years. Also, put money down if you possibly can. Even a thousand dollars in down payment reduces your principal and can shift you into a better interest rate tier with some lenders. Avoid rolling negative equity into a new loan. It's the single worst financial move most people make when trading in a car, and most of them don't even realize they're doing it. Check your credit score before you shop. A difference of 50 points can mean a full percentage point or more in your interest rate. I had someone recently who thought he was locked into a terrible rate because he had bad luck with a previous lender. He wasn't. His credit score was mid-60s, not terrible. Once he got a quote from a credit union and compared it to what the dealer was offering, he saved about $40 a month on the same loan amount. That sounds small until you multiply it across the life of a 72-month loan.
Consider certified pre-owned if you're set on going newer. CPO vehicles usually come with warranties that reduce your immediate maintenance risk, which matters because repair bills on cars out of warranty hit the people making car payments the hardest. A $1,200 transmission repair in month 30 of a loan is the kind of thing that turns a manageable payment into a missed payment. Budget for maintenance proactively. Set aside $100 to $150 a month into a separate account for car repairs. Most people don't do this. They treat their car as if it runs itself, then get blindsided.
Where This System Actually Fails People
The auto lending system is designed to make cars feel affordable when they often aren't. Salespeople are incentivized to extend terms and add products. Lenders are incentivized to approve more borrowers at higher rates. Everyone in the chain makes more money when your loan is larger and longer. That doesn't mean every car purchase is a bad decision. It means you need to go in knowing where the incentives are and not letting them dictate your choices. There are also demographic realities worth acknowledging. Black and Hispanic borrowers consistently receive less favorable loan terms than white borrowers with identical credit profiles, according to multiple Federal Reserve studies. Minority communities face higher denial rates and higher interest rates on auto loans even when controlling for income and credit score. If you fall into one of these categories, you may need to look harder for credit unions or community lenders that don't rely on credit scoring algorithms alone, because the conventional path often works against you regardless of your actual financial behavior. Gas prices fluctuate. Maintenance costs rise. Insurance premiums adjust annually. A payment that seemed fine in January might strain you by October if everything moves upward at once. The people most vulnerable to car payment stress are the ones who budgeted for stable prices and didn't plan for volatility. Build in a buffer. If your payment is $600 a month, make sure you can still pay it if your other expenses creep up by $100 or $150 across the board.

The bottom line is that car payments in 2025 absorb a significant chunk of disposable income for a large number of households. That's a fact, not an opinion. The question is whether you're approaching your next purchase with enough awareness to not become another statistic. Know your numbers before you walk into a dealership. Shop multiple lenders. Don't let sales pressure rush you into a decision that looks reasonable on paper but strains your actual monthly cash flow. And if your current payment is already too high, don't just refinance and extend it further. Address the root cause first.