Understanding Affirm's Position in the BNPL Space
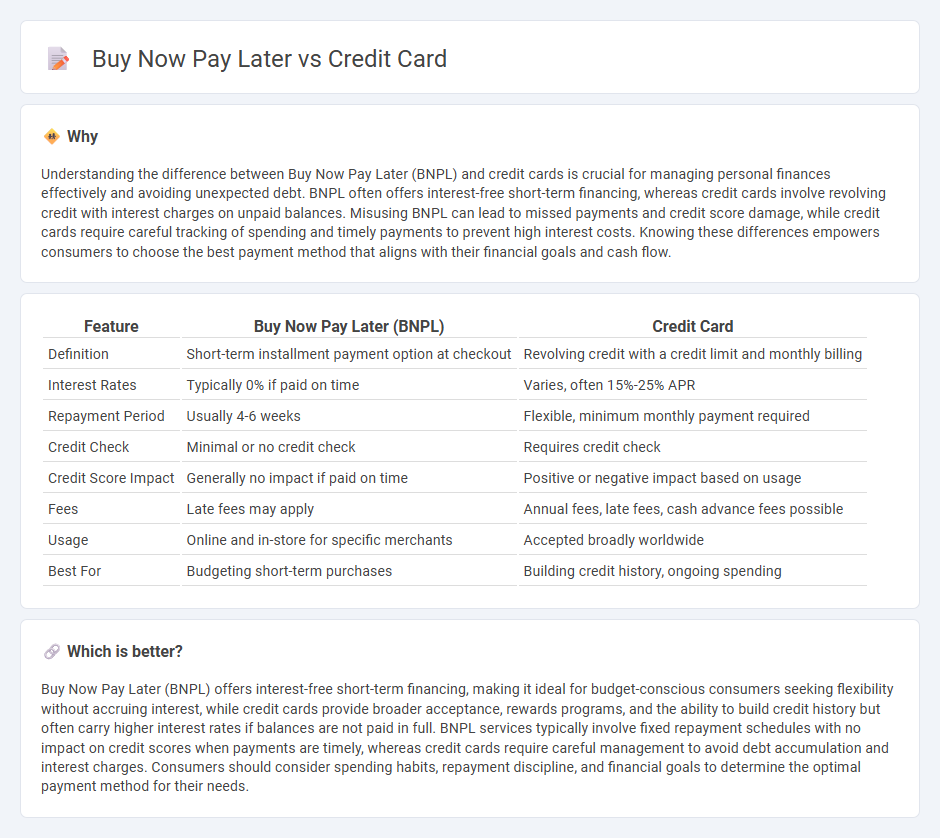
Affirm started as a point-of-sale installment loan provider. They partnered with merchants like Shopify stores, Amazon, and big retail chains. The model is straightforward: at checkout, you pick a payment plan instead of paying upfront. Now they've launched a credit card product that pulls that same logic into a reusable line of credit. The distinction matters more than most people realize.The Affirm Financial Credit Card A Detailed Look At A Buy Now Pay Later Option In The Credit Card Market
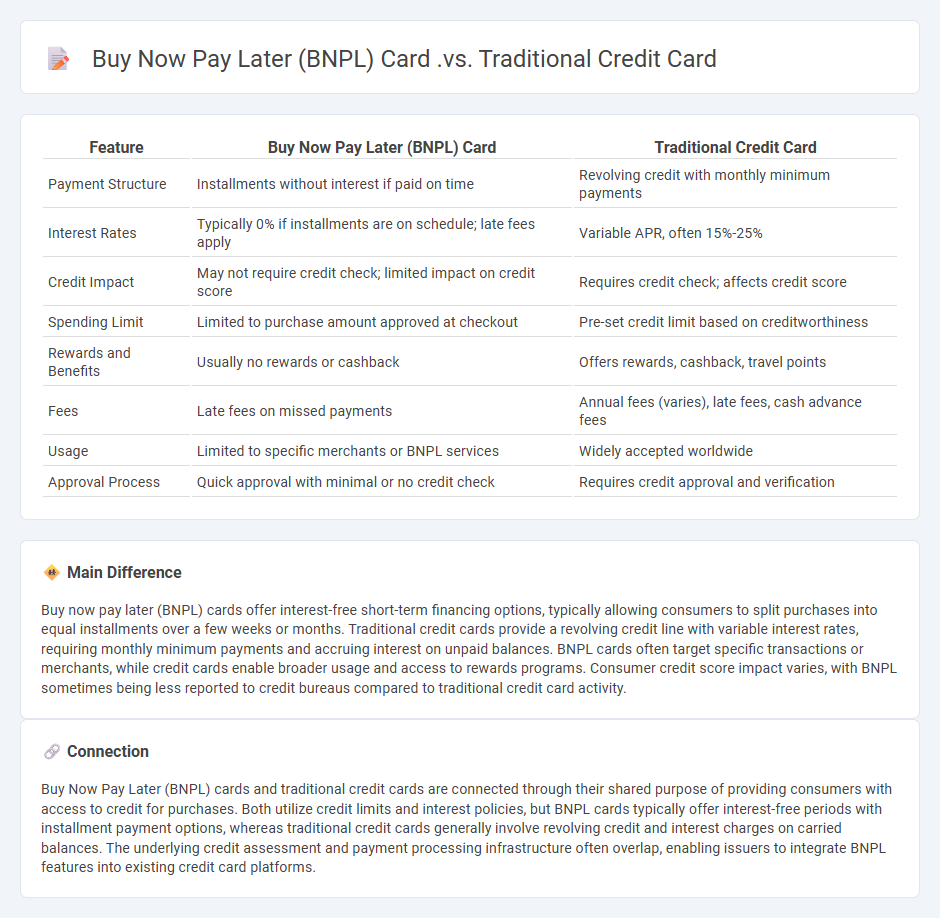
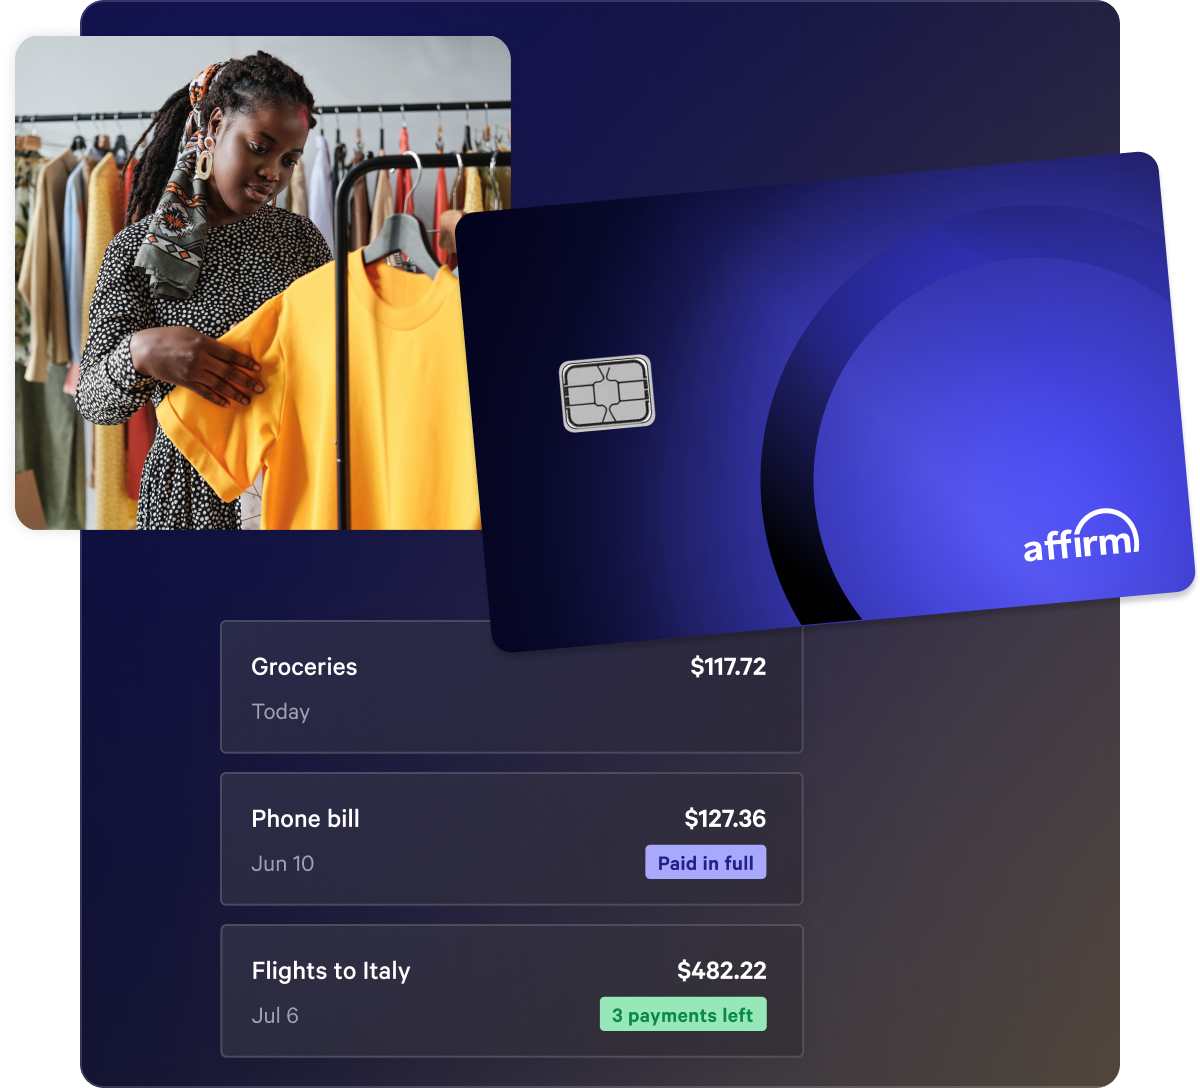
The Affirm Financial Credit Card A Detailed Look At A Buy Now Pay Later Option In The Credit Card Market is essentially a revolving credit product that applies their fixed-installment framework to everyday purchases. Unlike traditional credit cards where you carry a balance and get charged interest compounding monthly, Affirm structures most plans as fixed-term loans with set monthly payments. You see the total cost upfront. No surprise interest calculations. That transparency is their main selling point, and it's also where things get complicated. I ran into a specific issue when trying to use the card for a recurring subscription. The system doesn't handle auto-renewals cleanly on installment plans. When I tried to set up a gym membership that charged monthly, the transaction kept getting declined after the first payment. The workaround was calling Affirm support and asking them to flag the merchant category code for recurring billing approval. Took about twenty minutes on hold, but once they processed it, subsequent charges went through without issue. Not something you'd figure out from the FAQ page. Here's what most reviews don't mention clearly enough. The credit limit you see at approval isn't always the limit that applies to every transaction. Affirm uses dynamic limits based on your current open loan balances. If you have three active installment plans running simultaneously, your available credit drops proportionally. This is different from how traditional credit cards work, where your limit stays fixed regardless of outstanding balances. The math is actually simpler, but the mental model requires adjustment if you're coming from conventional credit cards.
Another counter-intuitive detail: paying off a loan early doesn't necessarily improve your approval chances for a higher limit. Affirm's underwriting weights recent payment behavior heavily, but they also factor in your debt-to-income ratio at the time of each new application. If you pay down one loan quickly and immediately apply for another purchase, the system may not reflect the improved financial position fast enough. I learned this the hard way after paying off a $400 electronics loan in three weeks, then getting declined on a $600 appliance purchase the following week. Waiting until the paid-off loan reported to the bureaus before applying made the difference.
How to Actually Use This Card Day to Day
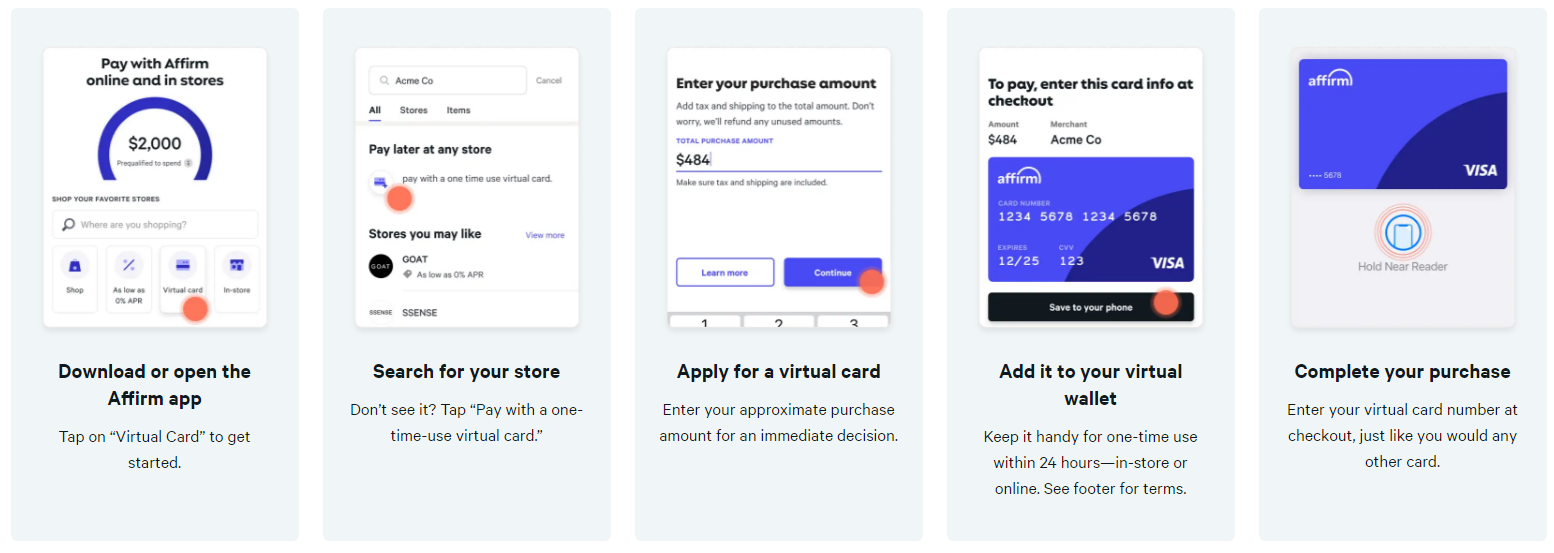
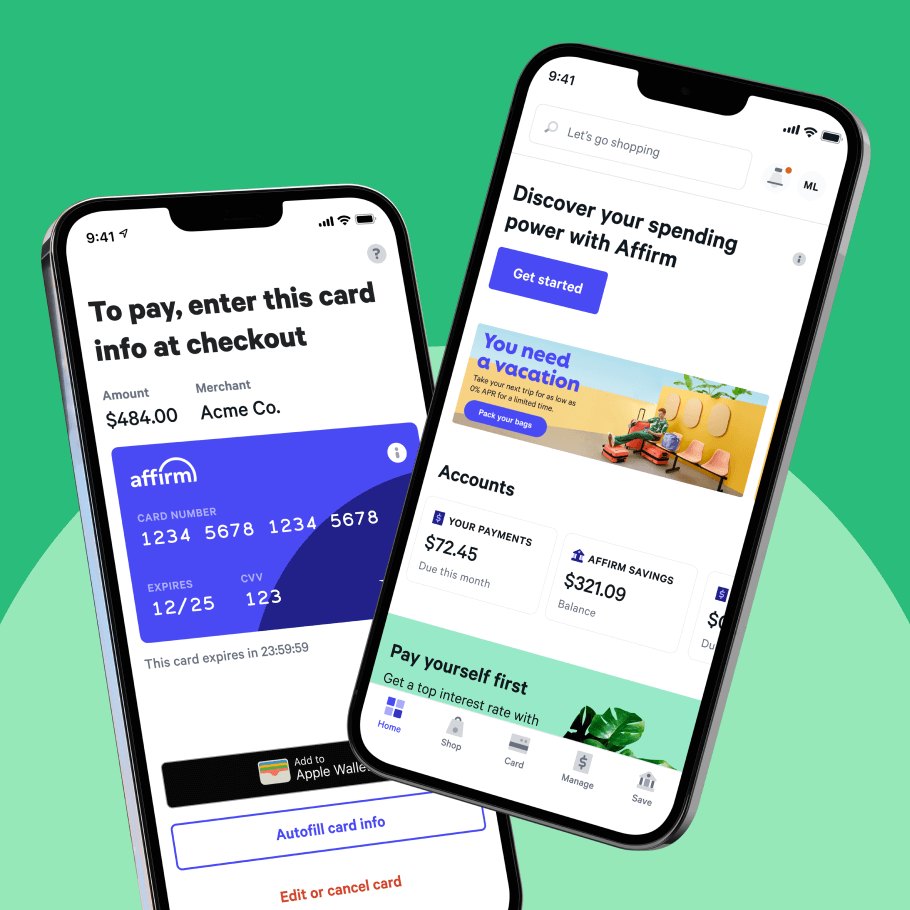
The application process takes about five minutes. Soft credit pull initially, which doesn't affect your score. Once approved, you get a virtual card number immediately in the app. Physical cards ship within seven to ten business days. The app interface is clean. Transaction history shows up the same day. Payment scheduling lets you pick your pay date relative to your direct deposit cycle, which is genuinely useful for cash flow management. Where people trip up is the merchant acceptance question. Affirm works at over a thousand checkout partners, but the in-store card usage is more limited than Visa or Mastercard. If you're trying to use it at a grocery store or gas station, it often won't go through. The card only processes where Affirm has an active merchant agreement. Online it's wider, but even then, some retailers block BNPL cards at checkout. Check the merchant's payment options page before you get to the register. I also discovered that the annual fee structure varies by plan tier. Some promotional rates come with no annual fee for the first year, then jump to a standard rate. The fine print buries this information. I noticed my rate change after exactly twelve months and had to call to confirm whether I was on a promotional or standard plan. The rep confirmed I was automatically rolled to the standard terms. Nothing illegal about it, but it's worth tracking your own account timeline so you're not blindsided.
Get the Full Details
The Hidden Costs Nobody Talks About
Late fees are where this product gets ugly. Affirm charges a late fee after a twelve-day grace period. The fee amount scales with your payment size, but it can add up quickly if you miss multiple cycles. More importantly, a single late payment doesn't just trigger a fee. It gets reported to credit bureaus. That's the same reporting standard as traditional credit cards. Your credit score takes a hit the way it would with any other revolving or installment product. The fixed-payment structure sounds safe, but it creates rigidity. If your income fluctuates month to month, you can't adjust your payment amount like you might with a minimum payment on a traditional card. You either pay the full scheduled amount or you're late. I worked with a client who had irregular commission income and got stuck twice because her paycheck didn't align with the payment date. She ended up paying both late fees and taking a hit on her credit report. Setting up automatic payments is not optional advice here. It's essential. Another edge case: what happens when you return an item purchased on an installment plan. The refund goes back to Affirm first, and they adjust your remaining balance. But if you've already made several payments, those payments aren't refunded to you. They're applied to the loan payoff. So if you bought a $300 item on a six-month plan, made three payments of $50 each, then returned the item, your remaining balance would be $150, not $0. You still owe the principal for the months you used the credit. This catches a lot of people off guard because the refund feels like it should wipe everything clean.
When This Product Makes Sense and When It Doesn't
This card works well for planned, large purchases where you want payment predictability. Medical expenses, home repairs, major appliances. The fixed schedule means you know exactly what you owe each month. No interest rate surprises. Good for people who struggle with carrying revolving debt and making minimum payments that barely cover interest. It does not work for impulse spending. The ease of approval combined with the installment framing makes small purchases feel manageable when they're not. I see it constantly: someone buying a $200 pair of shoes on a three-month plan, then another $150 gadget on a four-month plan, then a $400 watch on six months. Each one looks small. Together they create a debt service obligation that eats into monthly cash flow significantly. The transparent pricing doesn't protect you from your own spending habits. If you're already carrying high-interest credit card debt, this is not a solution. The rates on Affirm plans, while fixed and transparent, are not necessarily lower than what you're paying on existing revolving balances. Run the actual APR comparison before switching. Sometimes traditional credit card balance transfers with zero percent promotional rates beat Affirm's fixed installment costs over the same time horizon.
The product fills a real gap in the market. People who want transparency over traditional credit card complexity get it here. But the gaps in merchant acceptance, the rigidity of fixed payments, and the reporting consequences of missed payments mean it's not a blanket replacement for a traditional credit card. It's a tool for specific situations. Use it accordingly.