What Lenders Actually Look At When You Walk Into A Bank
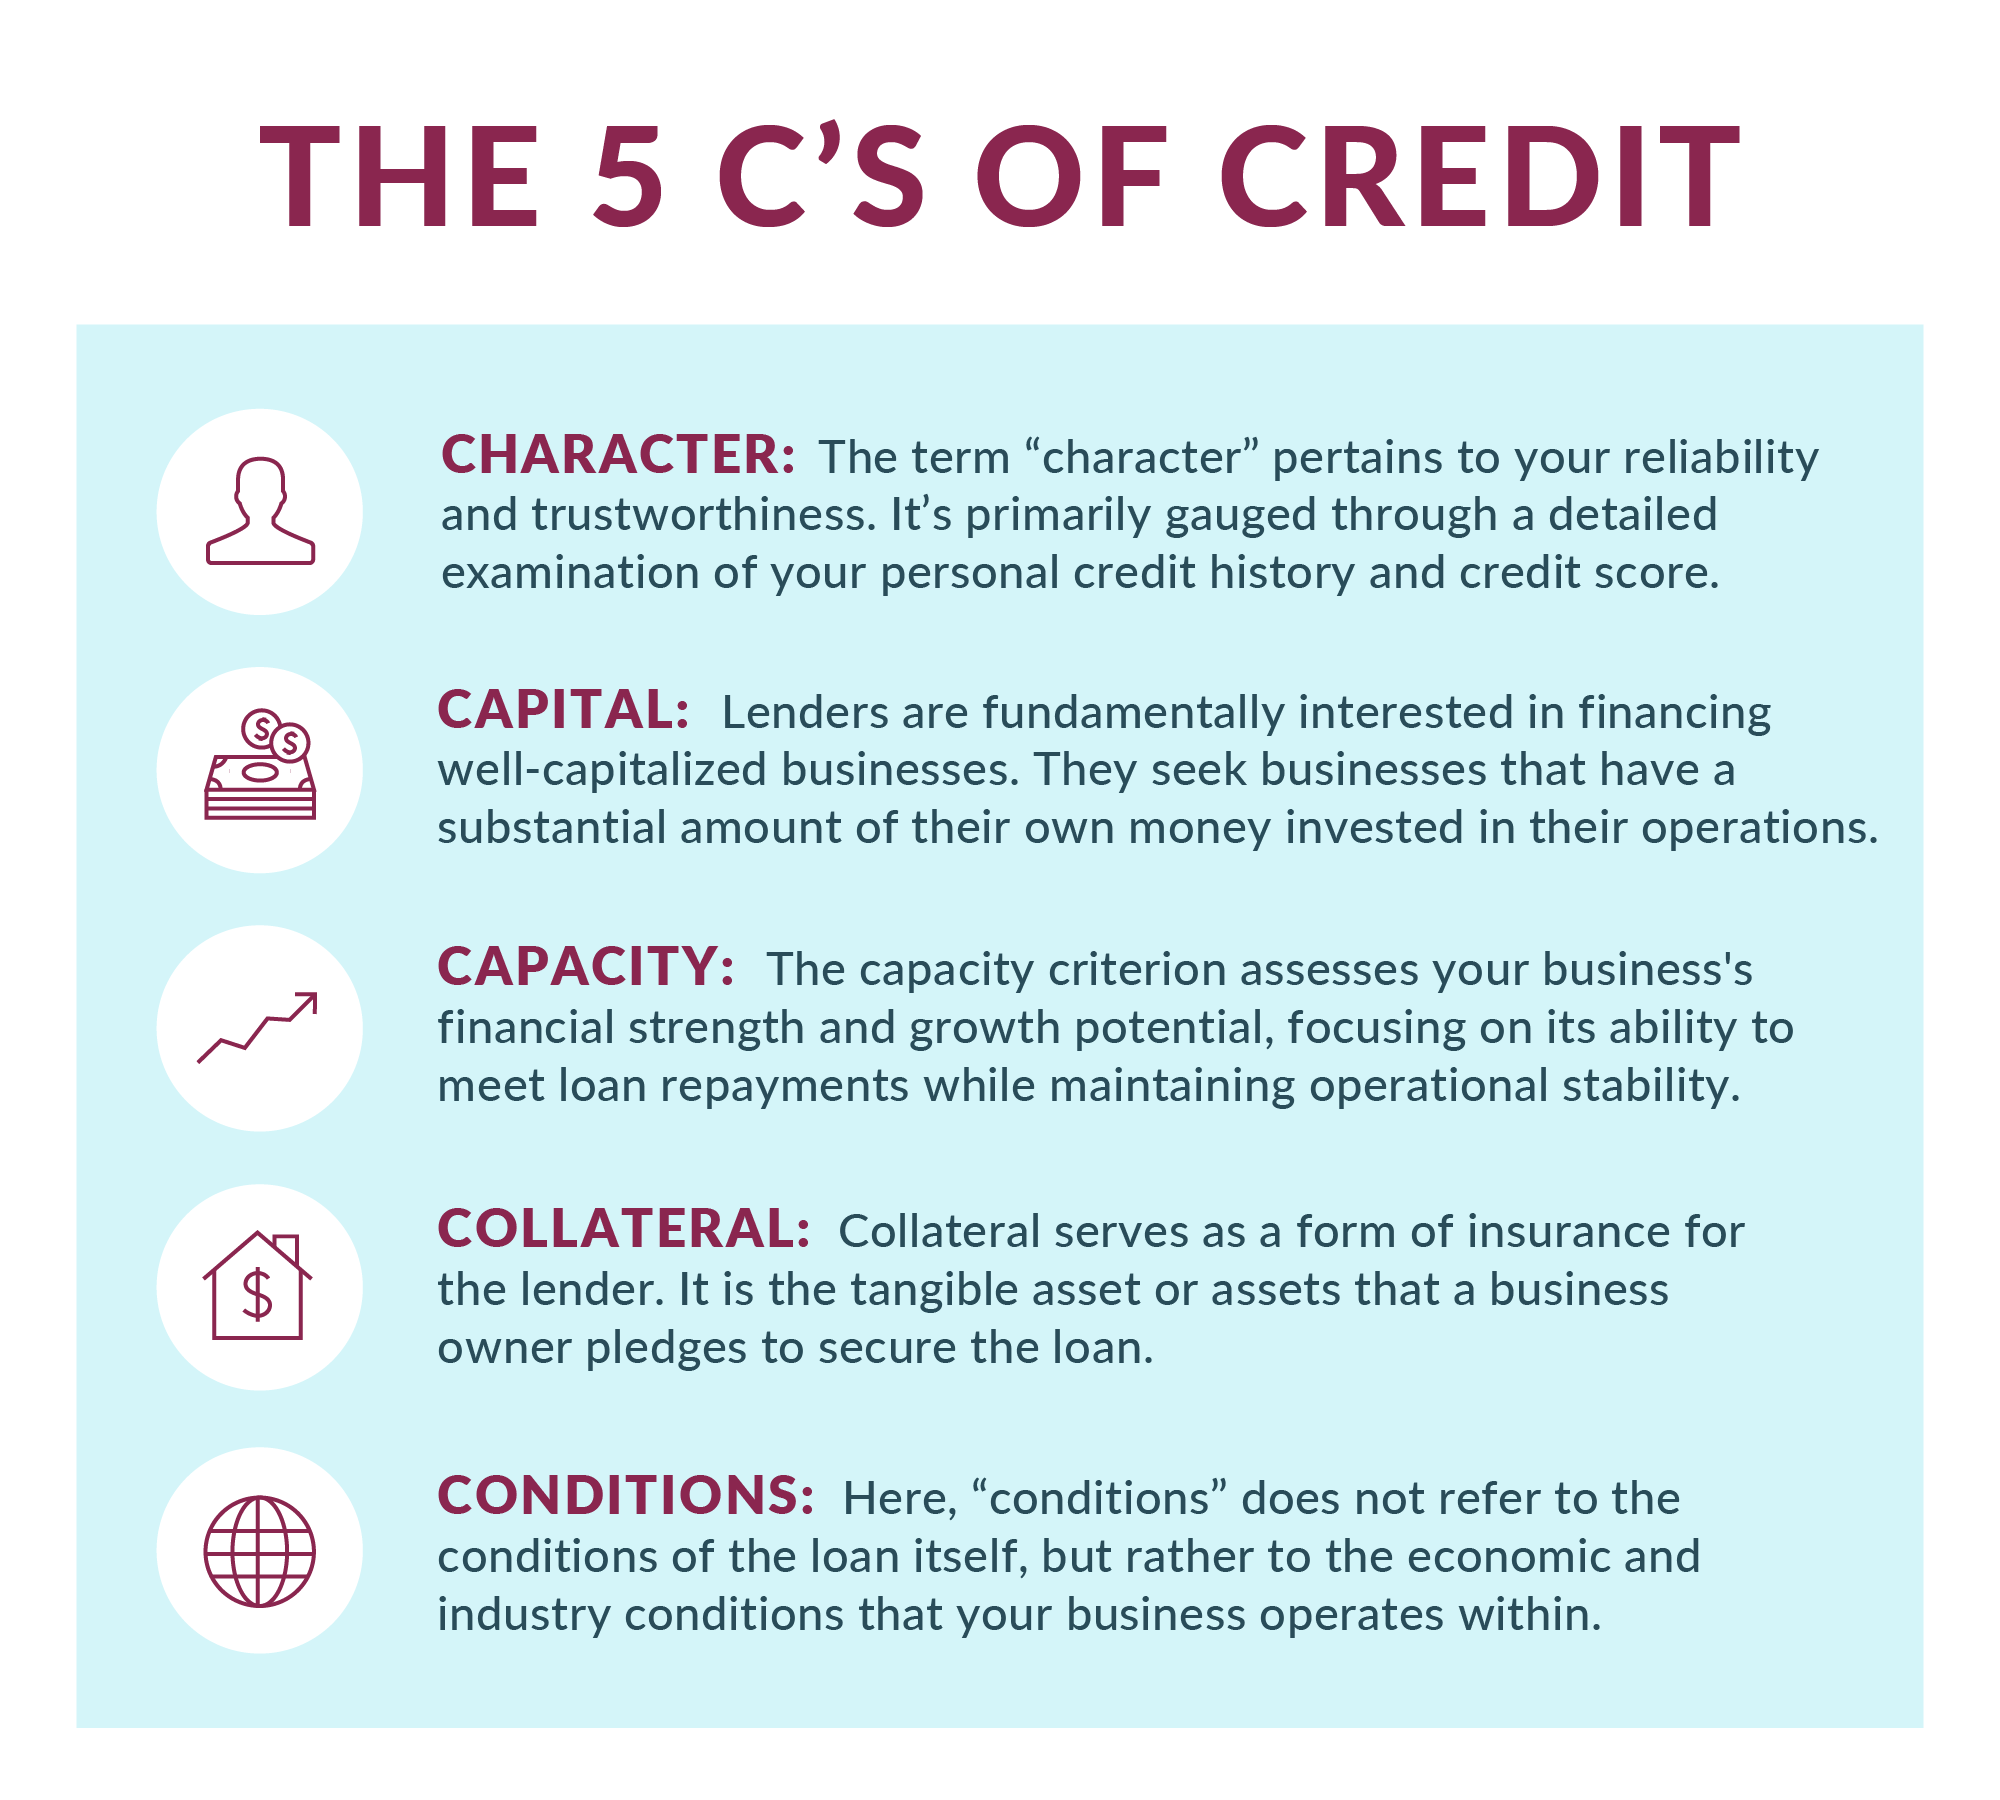
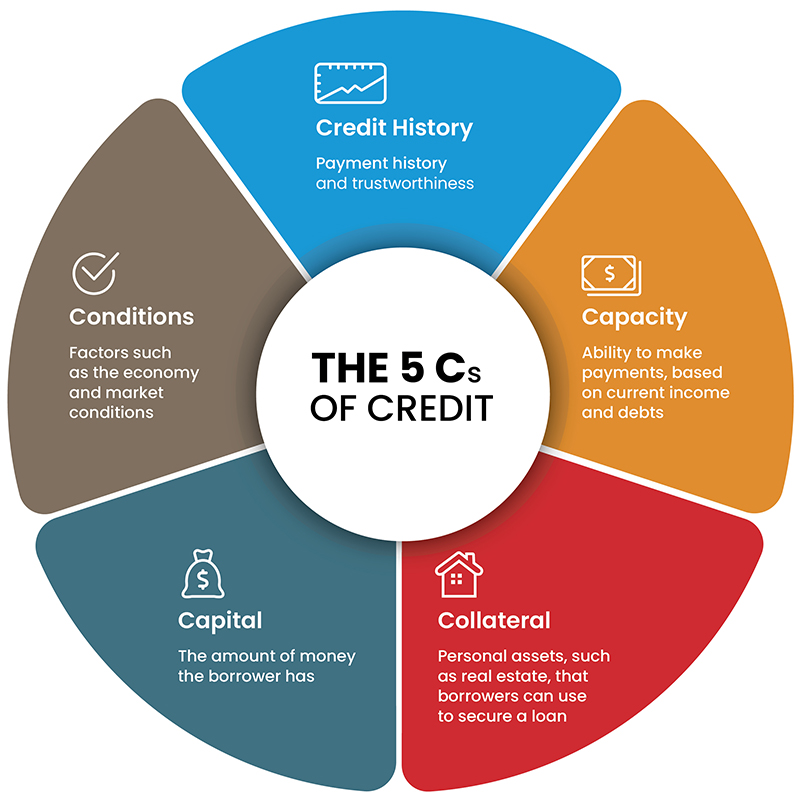
I spent twelve years in commercial lending before moving to the other side of the desk. The process never got less tedious, but I learned exactly what makes or breaks an application. Most people think credit is a number. It isn't. It's a story built from five data points that underwriters weigh against each other constantly. When you understand how they actually connect, you can shape your application before you even submit it. This framework has been the operating system for credit decisions since at least the 1920s. It survived FICO scores, algorithmic underwriting, and every wave of fintech disruption. The reason it persists is simple: five dimensions cover far more ground than any single metric ever could. A thin-file borrower with strong capacity can get approved where a high-score borrower with shaky capital cannot. Capacity is the debt service coverage ratio in plain English. Can this person actually produce enough cash to pay you back on schedule? I see borrowers obsess over their credit score and ignore capacity entirely. That is backwards. A borrower with a 720 score and a DTI of 52 percent will lose to a borrower with a 640 score and a DTI of 28 percent every single time. The lender cares about the payment, not the personality trait behind the score.
When I was structuring small business loans, I learned to look past the stated income. I would pull three months of bank statements and calculate actual net cash flow versus the proposed payment. One applicant had perfect tax returns showing $84,000 in revenue but the bank statements told a different story. The revenue was real but seasonal, concentrated in November and December with almost nothing from January through August. I structured a seasonal payment plan that matched their cash flow pattern and avoided a full denial. The standard algorithm would have approved the loan and then the borrower would have missed three payments by March. That is the kind of thing automated systems miss routinely. For individual consumers, capacity means your total monthly debt obligations relative to your net income. Lenders use two different ratios here. The front-end ratio looks at housing costs only. The back-end ratio includes everything: auto loans, student loans, credit cards, alimony, you name it. Most conventional loans cap the back-end ratio at 43 percent. VA and USDA loans sometimes go higher with compensating factors. Jumbo loans often demand a ratio below 36 percent. These thresholds shift depending on the loan program and the macro environment, so always verify current guidelines rather than relying on something you read three years ago.
Character Is Not What You Think It Is
Character in credit terms has almost nothing to do with morality or honesty. It is a measure of reliability and willingness to repay based on observable history. Underwriters look at payment patterns, credit history length, public records, and recent credit behavior. A single late payment from seven years ago means virtually nothing. Two late payments in the last six months means everything. I once worked a file for a self-employed contractor who had a $14,000 medical collection from 2018 that he never disputed and never paid. It was old, small, and completely irrelevant to his actual ability to pay. The automated underwriting system flagged it as a significant derogatory event and dropped his eligibility score by nearly 40 points. I pulled the original billing statement, confirmed the debt had been sent to collections and subsequently written off by the provider, and wrote a two-paragraph letter explaining the context with documentation attached. The underwriter overridden the flag manually. The loan closed. This happens constantly. The machine sees a collection and penalizes. A human underwriter understands that an old medical bill is noise, not signal. The counterintuitive part that most borrowers miss: having too clean a credit profile can sometimes hurt you. If you have never carried any installment debt and only use one credit card paid in full every month, the underwriter has zero evidence of how you handle recurring obligations. That is what we call a thin file. The system cannot assess your character because it has no behavioral data to analyze. The fix is usually straightforward: add a small installment loan like a credit-builder loan or a Auto Loan, keep it under six months, and make every payment on time. Three to six months of clean history is often enough to move you from thin file to established.
Get the Full Details
Capital Means Your Own Skin In The Game
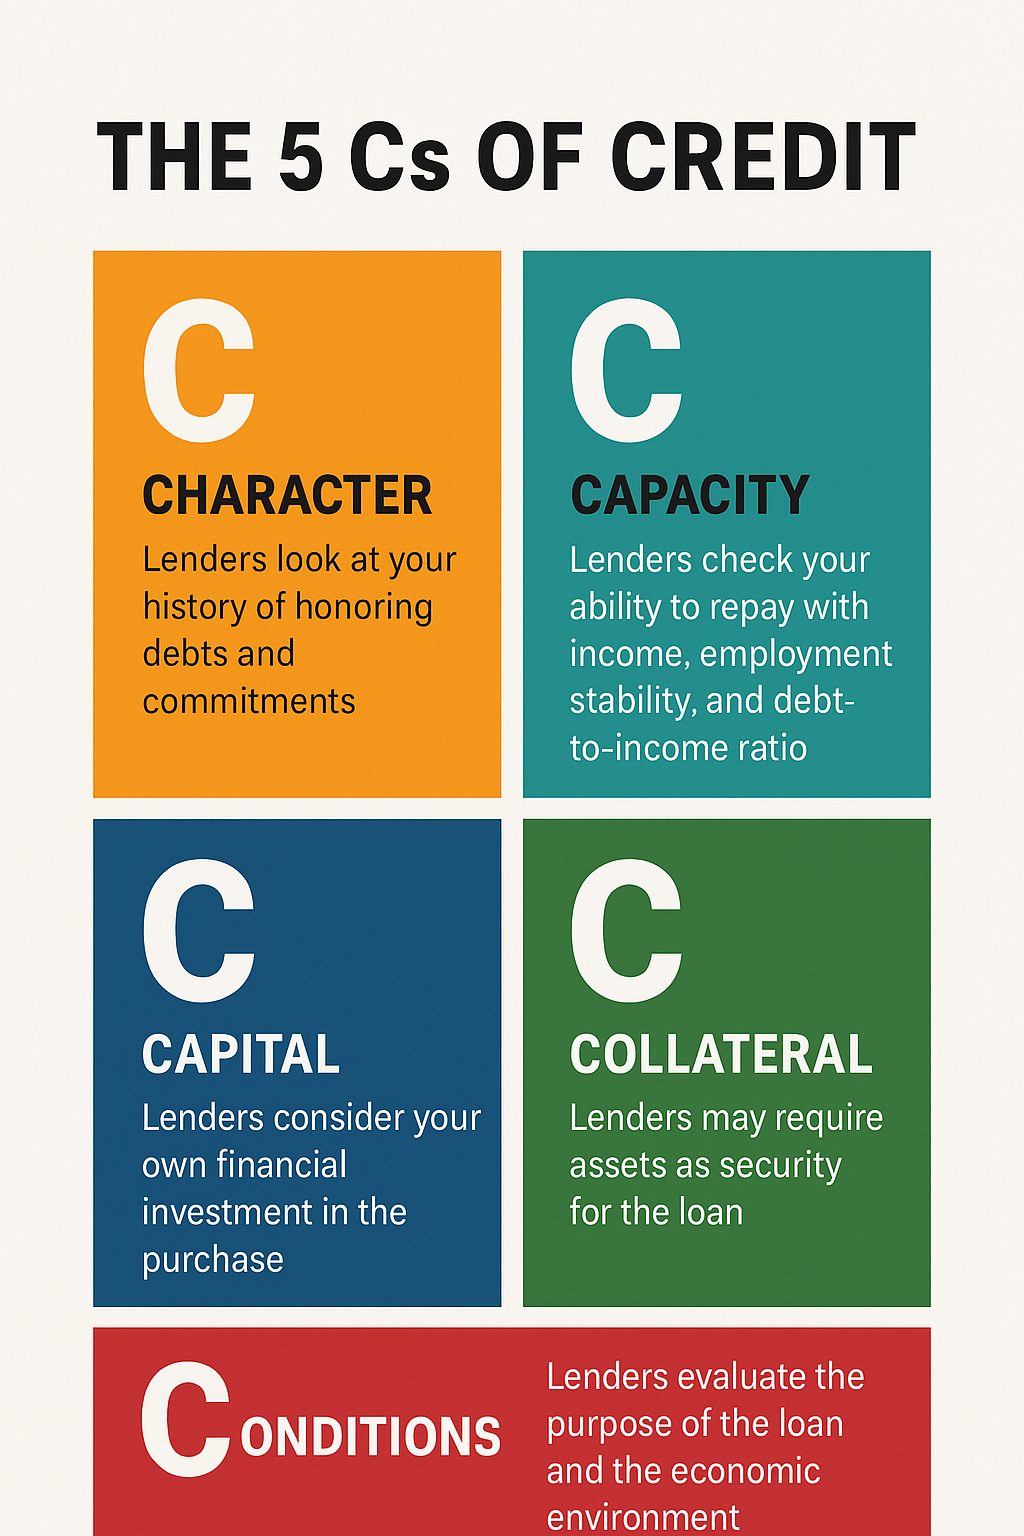
Capital refers to the borrower's own financial investment in the transaction. On a mortgage, this is your down payment. On a business loan, it is your owner's equity contribution. The purpose is twofold. First, it reduces the lender's exposure. Second, and more importantly, it signals commitment. A borrower who puts money at risk behaves differently than one who does not. I saw this play out clearly during the pandemic-era lending cycle. Two applicants applied for the same SBA 7(a) loan program. Both had similar revenue and collateral. One put up 20 percent of their own capital. The other put up zero and expected the loan to cover everything. The borrower with zero skin in the game got a higher interest rate and stricter covenants. Not because the lender was cruel. Because the risk profile changed dramatically when the borrower had nothing to lose if the business failed. This is a fundamental principle that gets ignored constantly. For residential mortgages, the capital requirement varies by program. Conventional loans can go as low as 3 percent for certain qualifying borrowers. FHA requires 3.5 percent with a 580 credit score. Zero-down VA and USDA loans exist but have income and property eligibility restrictions. The key insight most people miss is that your capital contribution does not need to come from savings. Gift funds from family members are acceptable for most programs, though they require a gift letter and paper trail. Some lenders also accept sweat equity or down payment assistance programs that can reduce your out-of-pocket cost significantly.
Collateral Is The Safety Net, Not The Main Event
Collateral is assets pledged to secure the loan. It is the last line of defense for the lender if the borrower defaults. Most consumers think collateral is only relevant for secured loans like auto loans or mortgages. That is incomplete. Even unsecured personal loans consider your assets indirectly when evaluating overall financial strength. In commercial lending, collateral valuation is where deals frequently fall apart. I remember a restaurant equipment financing deal where the borrower valued their used ovens, freezers, and POS system at $180,000 based on what they originally paid. The appraised liquidation value was closer to $62,000. That gap turned a well-structured loan into a rejection. The lesson is that original purchase price is irrelevant. Liquidation value is what matters. If you are borrowing against assets, get a professional appraisal before you apply. Do not estimate. Estimates cost you time and credibility. One practical workaround I developed: when collateral values are tight, I would sometimes restructure the loan to include a second priority lien on a different asset rather than trying to force a single asset to cover the full amount. A piece of equipment with a weak independent value might support a loan when combined with a blanket lien on accounts receivable. This is standard commercial practice but rarely discussed in consumer contexts. The principle is the same across the board: diversify your collateral base rather than concentrating risk on a single depreciating asset.
Conditions Are The Context That Nobody Talks About
Conditions encompass the purpose of the loan, the economic environment, industry trends, and the specific terms the lender is offering. This is the most dynamic of the five Cs and the one that changes fastest. A loan that looks solid today might look risky tomorrow if interest rates shift or the borrower's industry faces regulatory headwinds. During 2022 and 2023, I watched dozens of otherwise qualified borrowers get denied or offered worst-in-class terms purely due to conditions. The Federal Reserve raised rates aggressively. Commercial real estate values corrected. Restaurant and hospitality businesses were still recovering from pandemic disruptions. Lenders tightened their criteria across the board, and the five Cs framework became much harder to clear. A borrower who would have been approved at a 3 percent DTI and strong collateral in 2021 faced rejection in 2023 for the same numbers. This is not about the borrower changing. It is about the conditions changing. The practical takeaway is that timing matters more than most borrowers realize. If you are planning a significant credit event, monitor the macro environment. Avoid applying during periods of aggressive monetary tightening if you can defer. If you must borrow during tight conditions, strengthen the other four Cs proportionally. Better character, stronger capacity, more capital, and additional collateral can partially offset adverse conditions. But there is a limit. No amount of personal collateral will convince a lender to fund a struggling coffee shop in a market where coffee shop failure rates are triple the historical average. Conditions set the floor.
How The Five Cs Interact In Practice
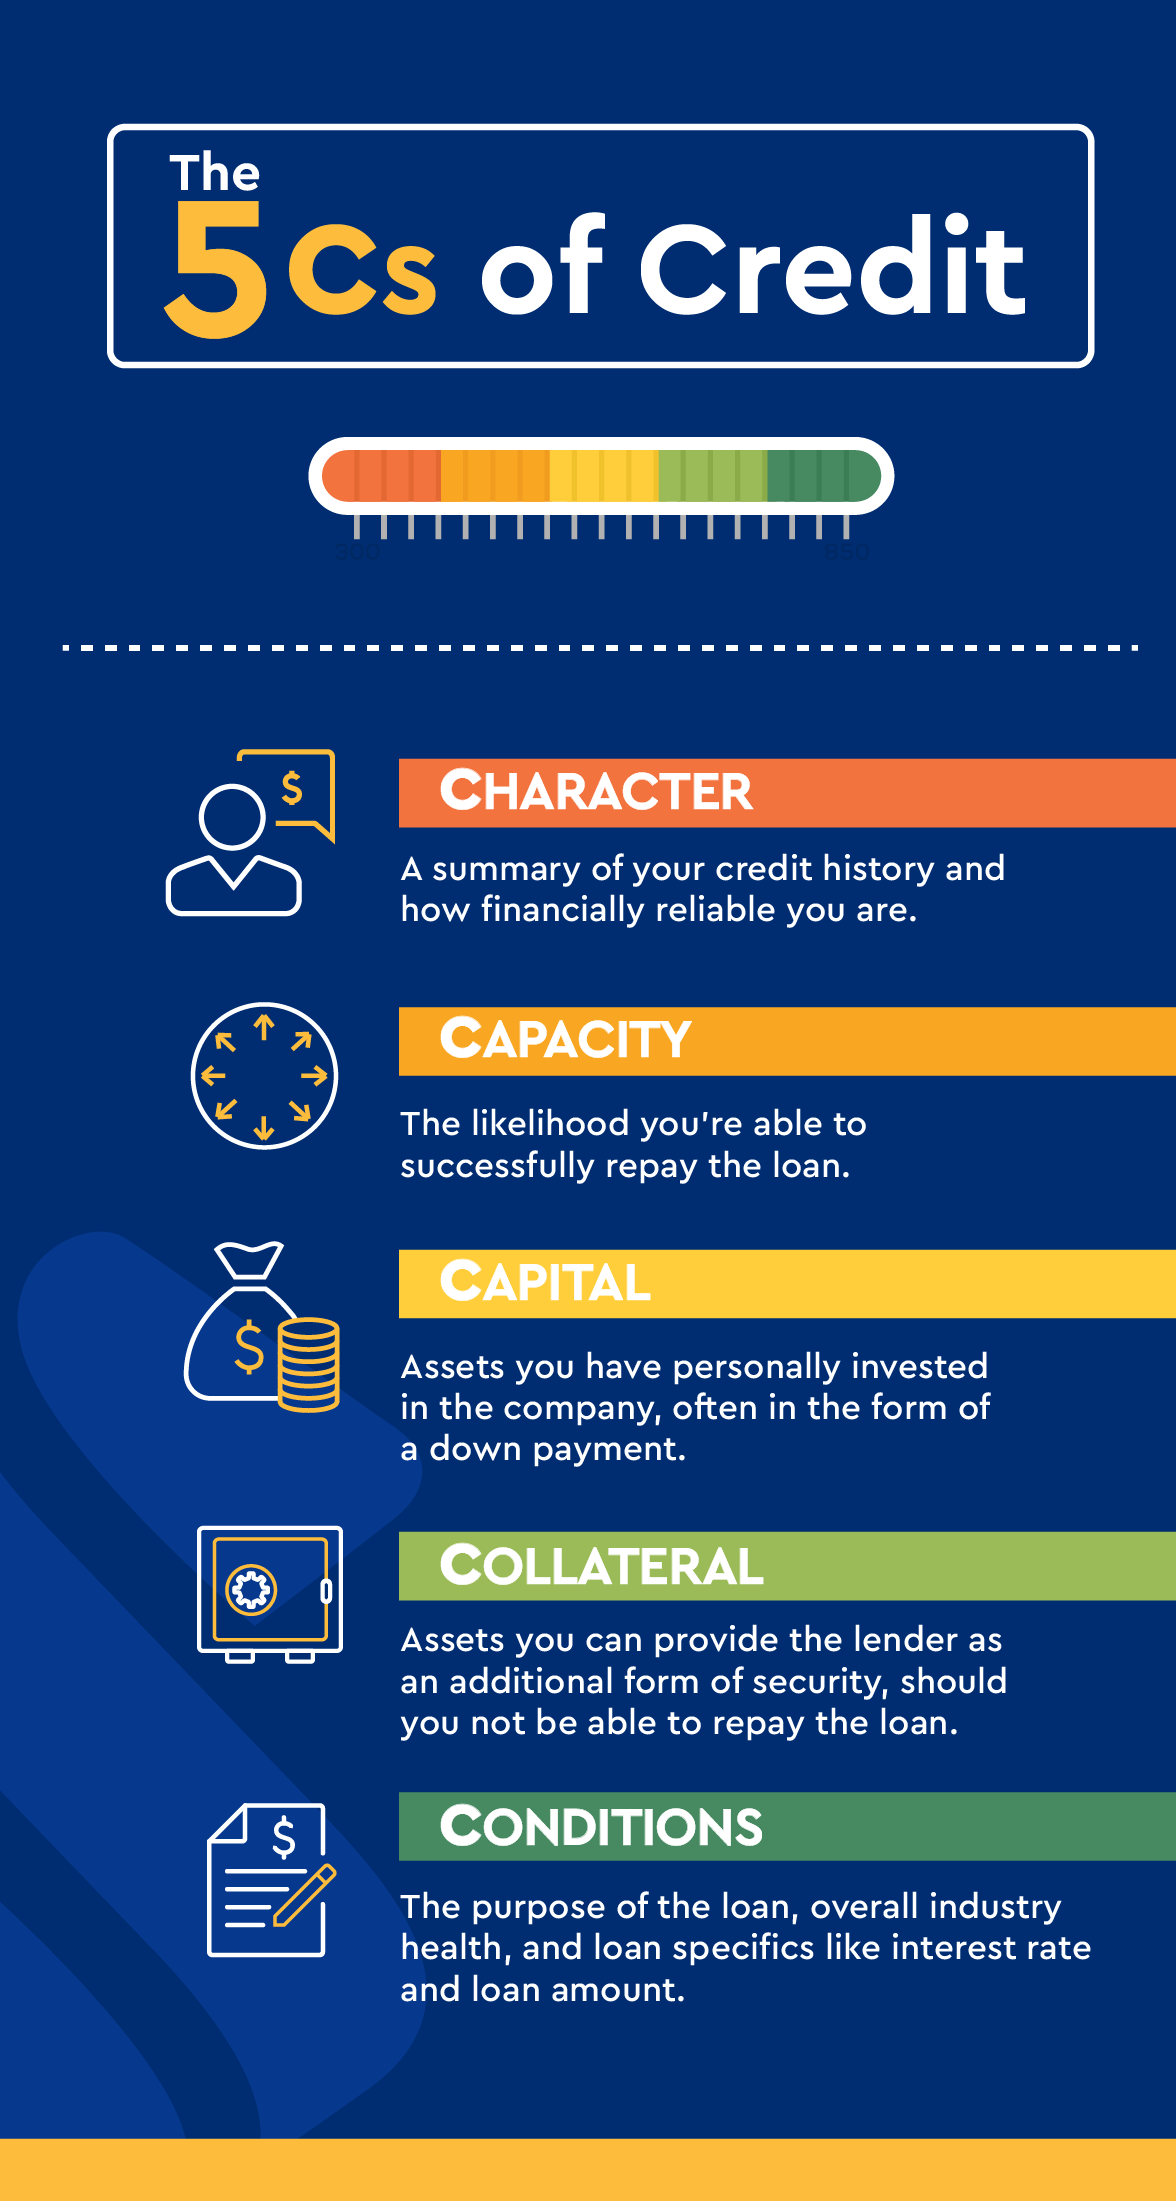
The five Cs do not operate independently. They trade off against each other in a system that underwriters manage intuitively rather than mathematically. Strong capacity can compensate for weaker capital. Strong collateral can offset marginal character. But there are hard floors. You cannot compensate for a recent bankruptcy with excellent capacity alone. You cannot offset zero capital contribution with strong collateral on a unsecured loan product. The framework has limits. I developed a simple mental model for evaluating my own credit applications: if any single C is severely weak, the entire application suffers disproportionately. One C at zero drags down the others. Five Cs at mediocre produces a better outcome than four strong Cs and one broken one. This is why I always recommend fixing the weakest link first before submitting anything. Paying down a single high-balance credit card can improve capacity and character simultaneously. Saving for a larger down payment improves capital and may improve conditions through better loan terms. The improvements compound.
Where The Framework Breaks Down
The five Cs model is useful but incomplete. It assumes rational evaluation of objective data. It does not account for algorithmic biases in scoring models. It does not capture informal credit relationships like rent payment history or utility payment patterns, which many borrowers carry reliably but which traditional systems ignore. It also struggles with gig economy workers whose income is irregular and whose tax documentation looks different from traditional W-2 employees. For nontraditional income situations, I recommend building a paper trail that mimics what the five Cs expect. Provide three years of tax returns, three months of bank statements, and a detailed profit and loss statement prepared by a CPA. The documentation bridges the gap between your actual financial reality and what the underwriting framework can process. It adds roughly two weeks to the application timeline but prevents automatic rejection based on incomplete data interpretation. Another limitation: the five Cs model favors borrowers with formal financial histories. It disadvantages immigrants, young adults, and anyone who built credit through informal channels. This is a structural bias, not a bug in the framework itself. The framework was designed for a different era of lending. Newer alternative data models are beginning to incorporate rental payments, phone bills, and even employment verification APIs, but adoption is uneven across lenders. If you fall into this category, shop lenders who explicitly advertise alternative underwriting approaches rather than applying to traditional banks that rely solely on the five Cs framework.