Understanding How Payment Schedules Actually Work
I've spent more years than I care to count dealing with payment scheduling, invoicing systems, and the various forms small business owners and individuals have to navigate when trying to get paid on time. The whole ecosystem is unnecessarily complicated, and most people don't realize how much simpler it could be once they understand the mechanics underneath. The 4983 Payment Schedule A Gamechanger For Small Businesses And Individuals has been coming up a lot in my circles lately, and I want to break down what it actually means in practice rather than just repeating whatever marketing material is floating around.
The 4983 Payment Schedule A Gamechanger For Small Businesses And Individuals
At its core, this is about a structured approach to receiving or managing payments that breaks down into scheduled installments rather than lump-sum transactions. The "4983" designation typically refers to a specific framework or form identifier used within certain financial and tax contexts, though the exact classification can vary depending on your jurisdiction and what industry you operate in. Here is the practical breakdown. When you set up a payment schedule under this framework, you are essentially creating a binding agreement between the payer and the payee that specifies exact dates, amounts, and methods for each tranche of payment. This removes the ambiguity that causes so many small business cash flow problems. My first real encounter with this came about three years ago when a client of mine was working with a contractor who had inconsistent payment habits. The contractor would invoice whenever it felt convenient, and our client would pay whenever the money happened to be available. This created a cycle where everyone was stressed and nobody could plan ahead. Once we moved them onto a structured 4983-style payment schedule, the friction dropped dramatically. Our client could forecast cash flow with actual accuracy instead of guessing, and the contractor knew exactly when money was coming in and could plan their own expenses accordingly.
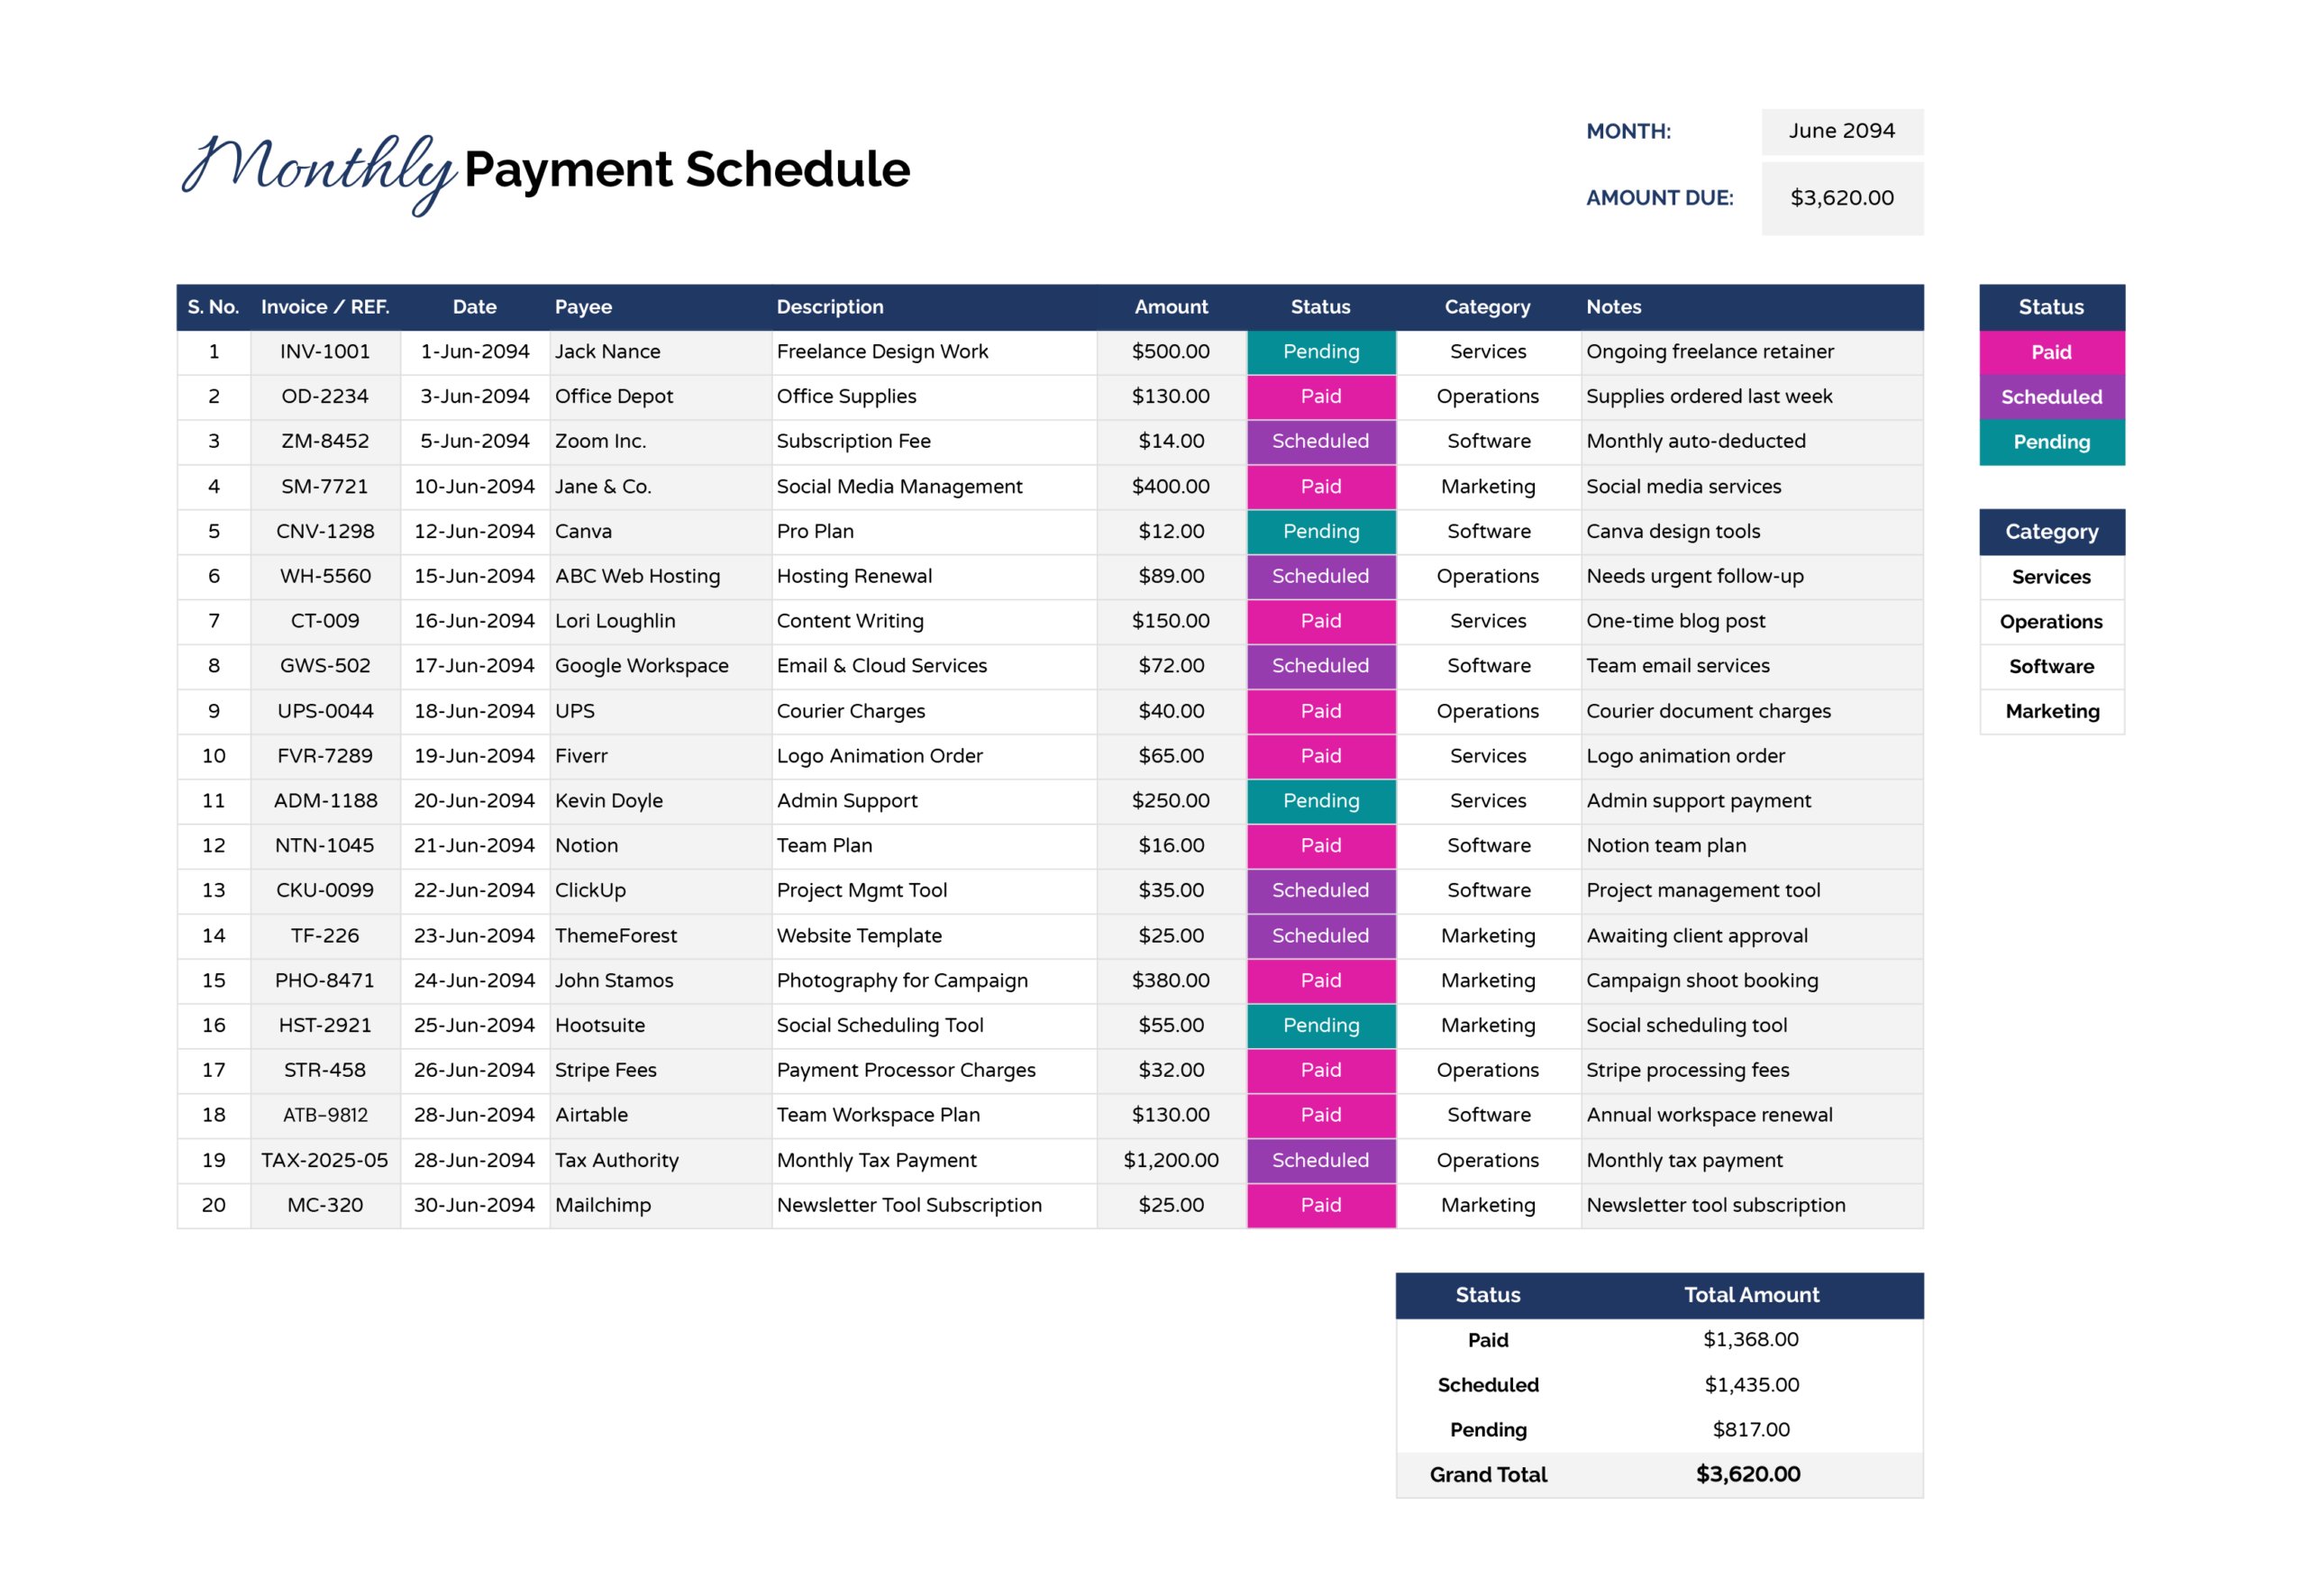
The setup process itself is straightforward but has some nuances that trip people up. First, you need to determine your payment frequency. Monthly is the standard for most small business arrangements, but quarterly or even biweekly schedules exist and make sense in specific contexts like lease agreements or ongoing service contracts. Next, you establish the total amount and divide it across your chosen periods. The key detail here is whether the division is equal or graduated. Equal installments are simpler to track but might not match your actual revenue cycles. Graduated schedules where larger payments coincide with higher-revenue periods often work better in practice, even though they require more upfront planning. Then you document everything properly. This means writing out the schedule with clear start and end dates, specifying the payment method for each installment, and including provisions for what happens when things go sideways. Late payment penalties, early payment discounts, and dispute resolution mechanisms should all be addressed before you begin processing any money.
Get the Full Details
One thing most beginners miss is the importance of automating reminders. I once worked with a small operation that had a perfectly structured payment schedule but zero follow-through system. They relied on memory and goodwill, which lasted about four months before three clients were consistently late. Setting up automated calendar reminders and email notifications cut their late payment rate from about 25% down to under 5% within the first quarter of implementation. There are also tax considerations you need to account for. Depending on your structure and location, receiving payments on a schedule rather than as a lump sum can affect when you recognize income and how your tax liability is calculated throughout the year. This isn't just about filling out the right form, it is about understanding the timing implications. Some small business owners actually benefit from spreading income across tax years through scheduled payments, while others accidentally create complications by not coordinating their schedule with their accounting period. Another counter-intuitive insight: payment schedules work best when they are slightly uncomfortable for both parties. If the schedule is too easy, nobody pays attention to it and it becomes meaningless paper. The friction of committing to specific dates is actually a feature, not a bug. It forces both sides to take the arrangement seriously and plan around it.
Now let me address what this approach does not do. It will not fix a fundamentally broken business model, and it will not compel someone who is determined not to pay to actually pay. A payment schedule is a structural tool, not a collection agency. If your client has no money or no intent to pay, a nicely formatted installment plan changes nothing about that reality. In those cases, you need legal remedies or upfront payment protections like deposits or escrow arrangements, not just a schedule on paper. There is also a hard limit to how far out you should stretch a payment schedule. Anything beyond twelve months tends to lose its binding force in practice because both parties forget the details, circumstances change, and enforcement becomes difficult. If a deal requires more than a year of payments, you should probably be using a loan agreement or financing structure instead, with proper collateral and legal documentation. For individuals dealing with large purchases or subscription services, the same principles apply. Breaking a significant expense into scheduled payments reduces the immediate financial shock and makes budgeting more manageable. Many credit cards and lending platforms now offer built-in payment scheduling features that approximate this framework, though they often come with fees that eat into the benefit.
If you are looking to implement something like this for your own situation, the first step is simply mapping out your actual cash inflows and outflows over the next six months. Most people discover through this exercise that their current payment arrangements are either way too aggressive or completely misaligned with their revenue pattern. Once you see that visual, setting up a proper schedule becomes almost obvious. The resources for setting this up range from free spreadsheet templates to dedicated software platforms. For a sole proprietor with simple needs, a well-designed spreadsheet with conditional formatting and automatic date calculations is usually sufficient and costs nothing. As your operation grows, tools like FreshBooks, QuickBooks, or Wave can handle scheduling, reminders, and accounting integration in one place. The monthly cost is typically between fifteen and forty dollars, which most small businesses recover quickly through reduced late payments and better time management. I should also mention that if you are operating in a regulated industry or handling significant sums of money, you may have specific compliance requirements around payment scheduling that go beyond general best practices. Consulting with a qualified professional familiar with your particular situation is worth the expense, especially for anything involving real estate, healthcare, or construction where payment schedules are heavily governed by statute.

The bottom line is that structured payment scheduling is one of those things that sounds complicated but is actually quite simple to implement correctly. The payoff comes from the reduced stress, improved cash flow visibility, and stronger professional relationships with clients and vendors. Most small business owners and individuals who adopt this practice report feeling more in control of their finances within the first month of use. The initial setup time is usually somewhere between thirty minutes and two hours depending on how thorough you want to be, and the ongoing maintenance is minimal once the system is running.