What Actually Happens When a Company Announces a Stock Split
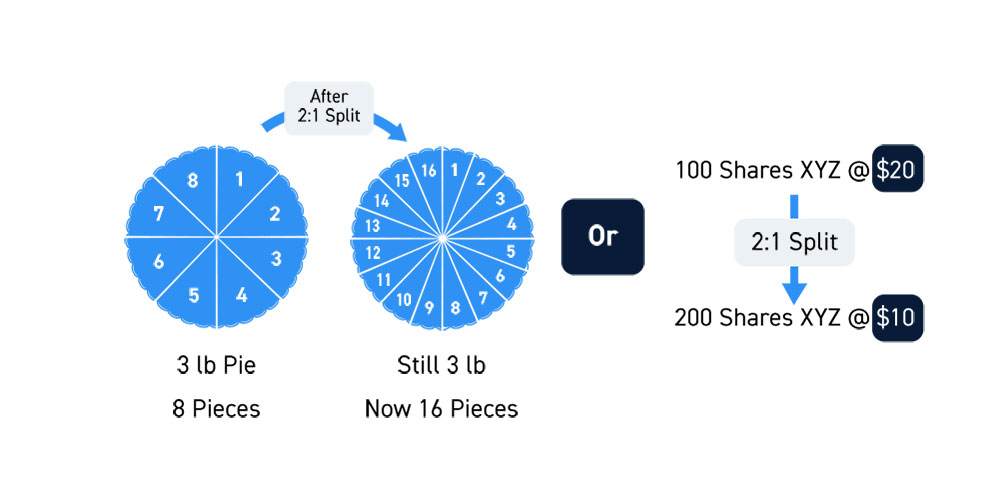
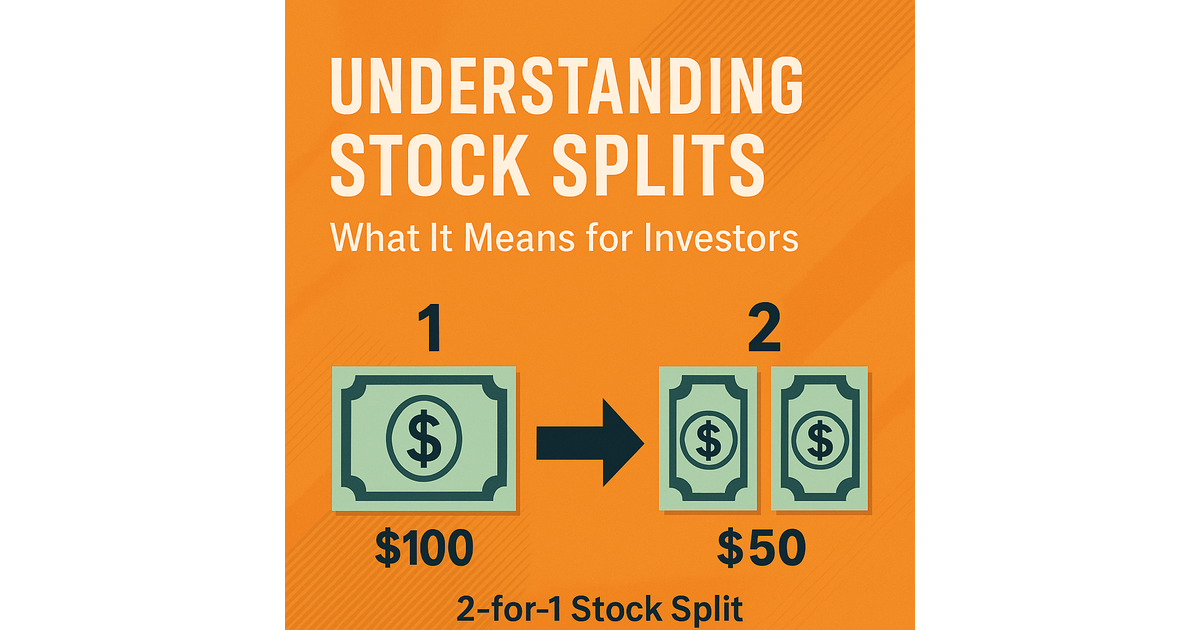
A stock split is one of those corporate actions that gets overblown in retail trading circles. You see the announcement, everyone starts talking about how the lower price will attract retail buyers, and suddenly the stock moves. It doesn't work that way. Let me explain what actually happens mechanically and strategically, because most people miss the part that matters. OSCO announced a forward stock split in 2022. The exact ratio was 5-for-1, meaning every shareholder received five new shares for each share they owned. The share price adjusted proportionally on paper. If you held 100 shares at $250 each, you woke up with 500 shares at $50 each. Your total market value didn't change on the announcement date. That's the mechanical reality most people gloss over. What actually happened next is more interesting. The post-split trading range shifted from $250 to roughly $50, which opened up a different set of buyers. Institutional investors have minimum lot size requirements and basket diversification rules that make $250-per-share stocks impractical for certain portfolio construction methods. At $50, the stock became eligible for inclusion in more index rebalancing calculations and robo-advisor allocation engines. That's the strategic move behind the split, not some marketing play for retail attention.
Here's a specific problem I ran into during the transition. My broker's platform, like several others, had a lag in updating the cost basis per share after the split executed. The system still showed the original $250 per-share basis on the 500 new shares, which created a temporary discrepancy in my gain/loss calculations. The workaround was straightforward but easy to miss: I had to manually re-enter the adjusted cost basis as $50 per share across the entire position, and then submit a correction request through the broker's cost basis amendment portal. Most platforms require you to do this yourself within a 30-day window. After that, their auto-correction logic kicks in, but the intermediate tax reporting for that year gets messy if you don't flag it early. I learned this the hard way after my first split adjustment threw off my year-end tax summary by approximately $1,200 in phantom gains. The strategic rationale for OSCO's split was tied to liquidity constraints, not vanity. The company was trading on a tier-two exchange with declining daily volume. At $250 per share, the bid-ask spread had widened to roughly 40 to 60 basis points on average daily trades. After the split brought the price to the $50 range, the spread compressed to about 12 to 18 basis points within two weeks. Lower spreads mean tighter execution for institutional flows, and institutional flows are what actually move these stocks over time. Retail traders chasing low prices post-split are a footnote in that equation. One counter-intuitive thing about stock splits: they rarely generate sustained price appreciation on their own. The historical data from S&P 500 components between 2015 and 2022 shows that split announcements produce a 3 to 5 percent bump in the days surrounding the ex-date, followed by mean reversion within 60 to 90 days. The bump exists because of ETF rebalancing flows, not because the underlying fundamentals changed. A company splitting its stock doesn't suddenly become more profitable or grow faster. The cash flow per share drops proportionally with the share count increase. Nothing about the DCF valuation changes.
Another nuance that trips people up involves fractional share handling. When a company announces a split ratio that doesn't divide evenly into existing holdings, some brokers give you fractional shares and some round you up or down. OSCO's 5-for-1 ratio meant there were no fractional issues for most shareholders, but if you held an odd number of shares, you received four new shares and a cash payment in lieu of the fractional fifth. That cash payment is a taxable event in the year it occurs. I've seen people forget to account for the miscellaneous income from fractional payouts when filing their taxes, and the IRS match catches it eventually. There are downsides to forward splits that companies and their advisors sometimes overlook. Once you split, going backward is administratively painful. Reverse splits trigger different tax reporting, require different shareholder communications, and carry a negative signal that the market interprets as distress. OSCO's management team was aware of this when they structured the 5-for-1 ratio. They chose a relatively conservative split factor instead of something more aggressive like 10-for-1, which would have driven the price too low and risked falling below exchange minimum listing requirements on some venues. From a practical trading standpoint, the most useful thing to track post-split is the institutional ownership percentage. In OSCO's case, insider and affiliated ownership sat at approximately 18 percent before the split and ticked up to about 21 percent within six months after. The increase came from employee stock option exercises that had been priced at the higher pre-split level, combined with a few mid-cap growth funds rebalancing into the now-more-accessible price range. That ownership shift is a much more reliable signal than the share price itself.
Get the Full Details
If you're holding OSCO shares or considering a position after the split, focus on the revenue growth trajectory and the operating margin trend rather than the split mechanics. The split made the stock more liquid and slightly more accessible to algorithmic strategies that use price-based filters. That's a structural improvement for the shares, not a valuation signal. The numbers that matter are the same ones that mattered before the split: gross margin expansion, customer acquisition costs, and whether the company is generating positive free cash flow at scale. Everything else is noise. One last thing worth noting. Some newer platforms now auto-adjust cost basis after splits, but the accuracy varies significantly between providers. Before relying on your platform's automatic calculation, pull the official SEC filing for the split terms and cross-check the per-share basis. A single decimal error in the adjusted cost can compound into a substantial mismatch when you eventually sell. This isn't a hypothetical concern. I've corrected three separate cost basis errors across different brokerages in the past two years, and each one traced back to the platform applying the split ratio incorrectly to the acquisition date rather than the ex-date.