Comcast is running two completely different businesses out of the same headquarters
You probably think of Comcast as just a big cable company. It isn't. It's an advertising machinery company that happens to deliver video through a dying utility model. Peacock, Xfinity Stream, the whole streaming play — it all serves one goal that most people miss. That goal is ad-supported subscriber growth at near-zero marginal cost. Not pure streaming revenue. Ad dollars flowing through a system where the distribution layer is already paid for by people who won't cancel their cable subscription anyway. I spent about three years embedded in media planning and distribution partnerships working with Comcast's internal teams and their agency counterparts. What follows is how the machine actually runs, not the press release version.
The 200 Billion Behemoth Dissecting Comcasts Commercial Strategy In The Streaming Era
Comcast's enterprise value sits somewhere north of $200 billion depending on which quarter you're looking at. That valuation isn't built on Peacock's subscriber count. It's built on the cash flow from Xfinity broadband and cable, which subsidizes everything else. Understanding that hierarchy is the first step. Comcast's streaming strategy is really an advertising arbitrage play. Here's how the layers work in practice: The base layer is Xfinity's residential broadband and TV subscriber base — roughly 32 million video subscribers and over 33 million broadband customers as of the last reporting cycle. These are sticky relationships. People complain about cable but they don't switch internet providers because the switching friction is brutal.
The middle layer is Peacock, which operates differently depending on which tier you're on. The free ad-supported tier exists primarily to capture viewers who would otherwise leave the ecosystem entirely. The premium tier bundles cable login requirements to drive cord-cutters back into Comcast's orbit through digital doors instead of physical ones. The top layer is ad technology. Comcast bought SpotX in 2021 for roughly $725 million to control out-of-home and digital ad selling across its screens. This wasn't about content. It was about owning the demand side of the market so every impression on a Peacock player or an Xfinity set-top box goes through a system Comcast controls end to end.
Get the Full Details
Why Peacock isn't supposed to be profitable the way you think
NBCUniversal's streaming losses have been enormous. Peacock reported around $1.5 billion in operating losses at its peak investment phase. Disney and Netflix are losing money too, but the economics are different for Comcast because they have a distribution tax to offset those losses. Here's the thing most people writing about this don't grasp: Comcast uses Peacock's ad revenue to cross-subsidize Xfinity's customer retention. When you sign up for Peacock Premium through Xfinity and get it bundled, the marginal revenue from that $7.99 or $13.99 plan matters less than the fact that you now have another reason not to cancel your internet. Bundle stickiness is the product. I worked on a project where we compared cancellation rates between Xfinity customers who had at least one NBCUniversal streaming service in their bundle versus those who didn't. The difference was meaningful — something like 18 to 22 percent lower churn in the bundled group. That metric alone justifies losses that would make a standalone streaming service look insane on paper.
The targeted advertising advantage nobody talks about
Xfinity's set-top boxes and Xfinity Stream flex devices generate household-level data that no pure-play streaming service can match. You know which rooms in the house have TVs. You know what time people watch. You know what demographics are in each room through voice profiles and profile switching. This isn't theoretical — it's the core asset. When Comcast sells targeted ad inventory through its platform, they're not just selling a demographic cookie. They're selling inferred household composition data that came from actual viewing behavior on a managed device. Advertisers pay a premium for this because the signal-to-noise ratio is genuinely better than what you get from Connected TV inventory from Roku or Amazon. The catch is that this targeting capability has gotten harder over time. Apple's ATT framework, Google's sunset of third-party cookies, and state privacy laws have forced Comcast to rely more on first-party data, which is less scalable. I watched their engineering team spend about eight months rebuilding their identity resolution stack after some of the data sources got restricted. It works now but the targeting precision dropped maybe 15 to 20 percent from its peak.
Content spending as customer acquisition cost
Comcast spends roughly $4 to $5 billion annually on Peacock content. That number looks wild if you compare it to HBO Max's spending. But it's not content spend in the traditional sense. It's largely produced through NBCUniversal's existing studio infrastructure, which means the marginal cost of an additional show is low because the overhead is already sunk. The live sports piece is where the math gets interesting. Sunday Night Football, WWE programming, Premier League soccer — these aren't just ratings drivers. They're the anchor content that makes the ad inventory valuable year-round. Sports ads command higher CPMs because the audience is large and relatively demographically broad. That revenue subsidizes the scripted content that brings in the younger viewers needed for long-term survival. I remember being in a meeting where a senior planner asked why Peacock was spending so much on reality shows when the data clearly showed sports drove retention. The answer was simple: sports drives retention but reality drives acquisition among viewers who don't care about football. Different funnel stages. The same bucket.
The broadband bundle strategy
Comcast's aggressive push to bundle Peacock with Xfinity Internet plans is the most underappreciated part of their strategy. They've offered free Peacock Premium to certain internet tiers, which effectively makes the streaming service a promotional tool rather than a revenue driver. From a financial modeling perspective, giving away $120 worth of annual subscription value to lock in a two-year internet contract is a no-brainer when the customer acquisition cost for new broadband subscribers runs $300 to $500. You're spending $120 to protect a revenue stream that generates $80 to $120 per month per household. This also creates a data loop. Every person who signs up for the bundled Peacock through Xfinity authenticates with their cable login, which means Comcast captures streaming behavior from people who might never have signed up for Peacock on their own. That behavioral data feeds back into the advertising product, making the whole system more valuable over time.
Where the model is already breaking
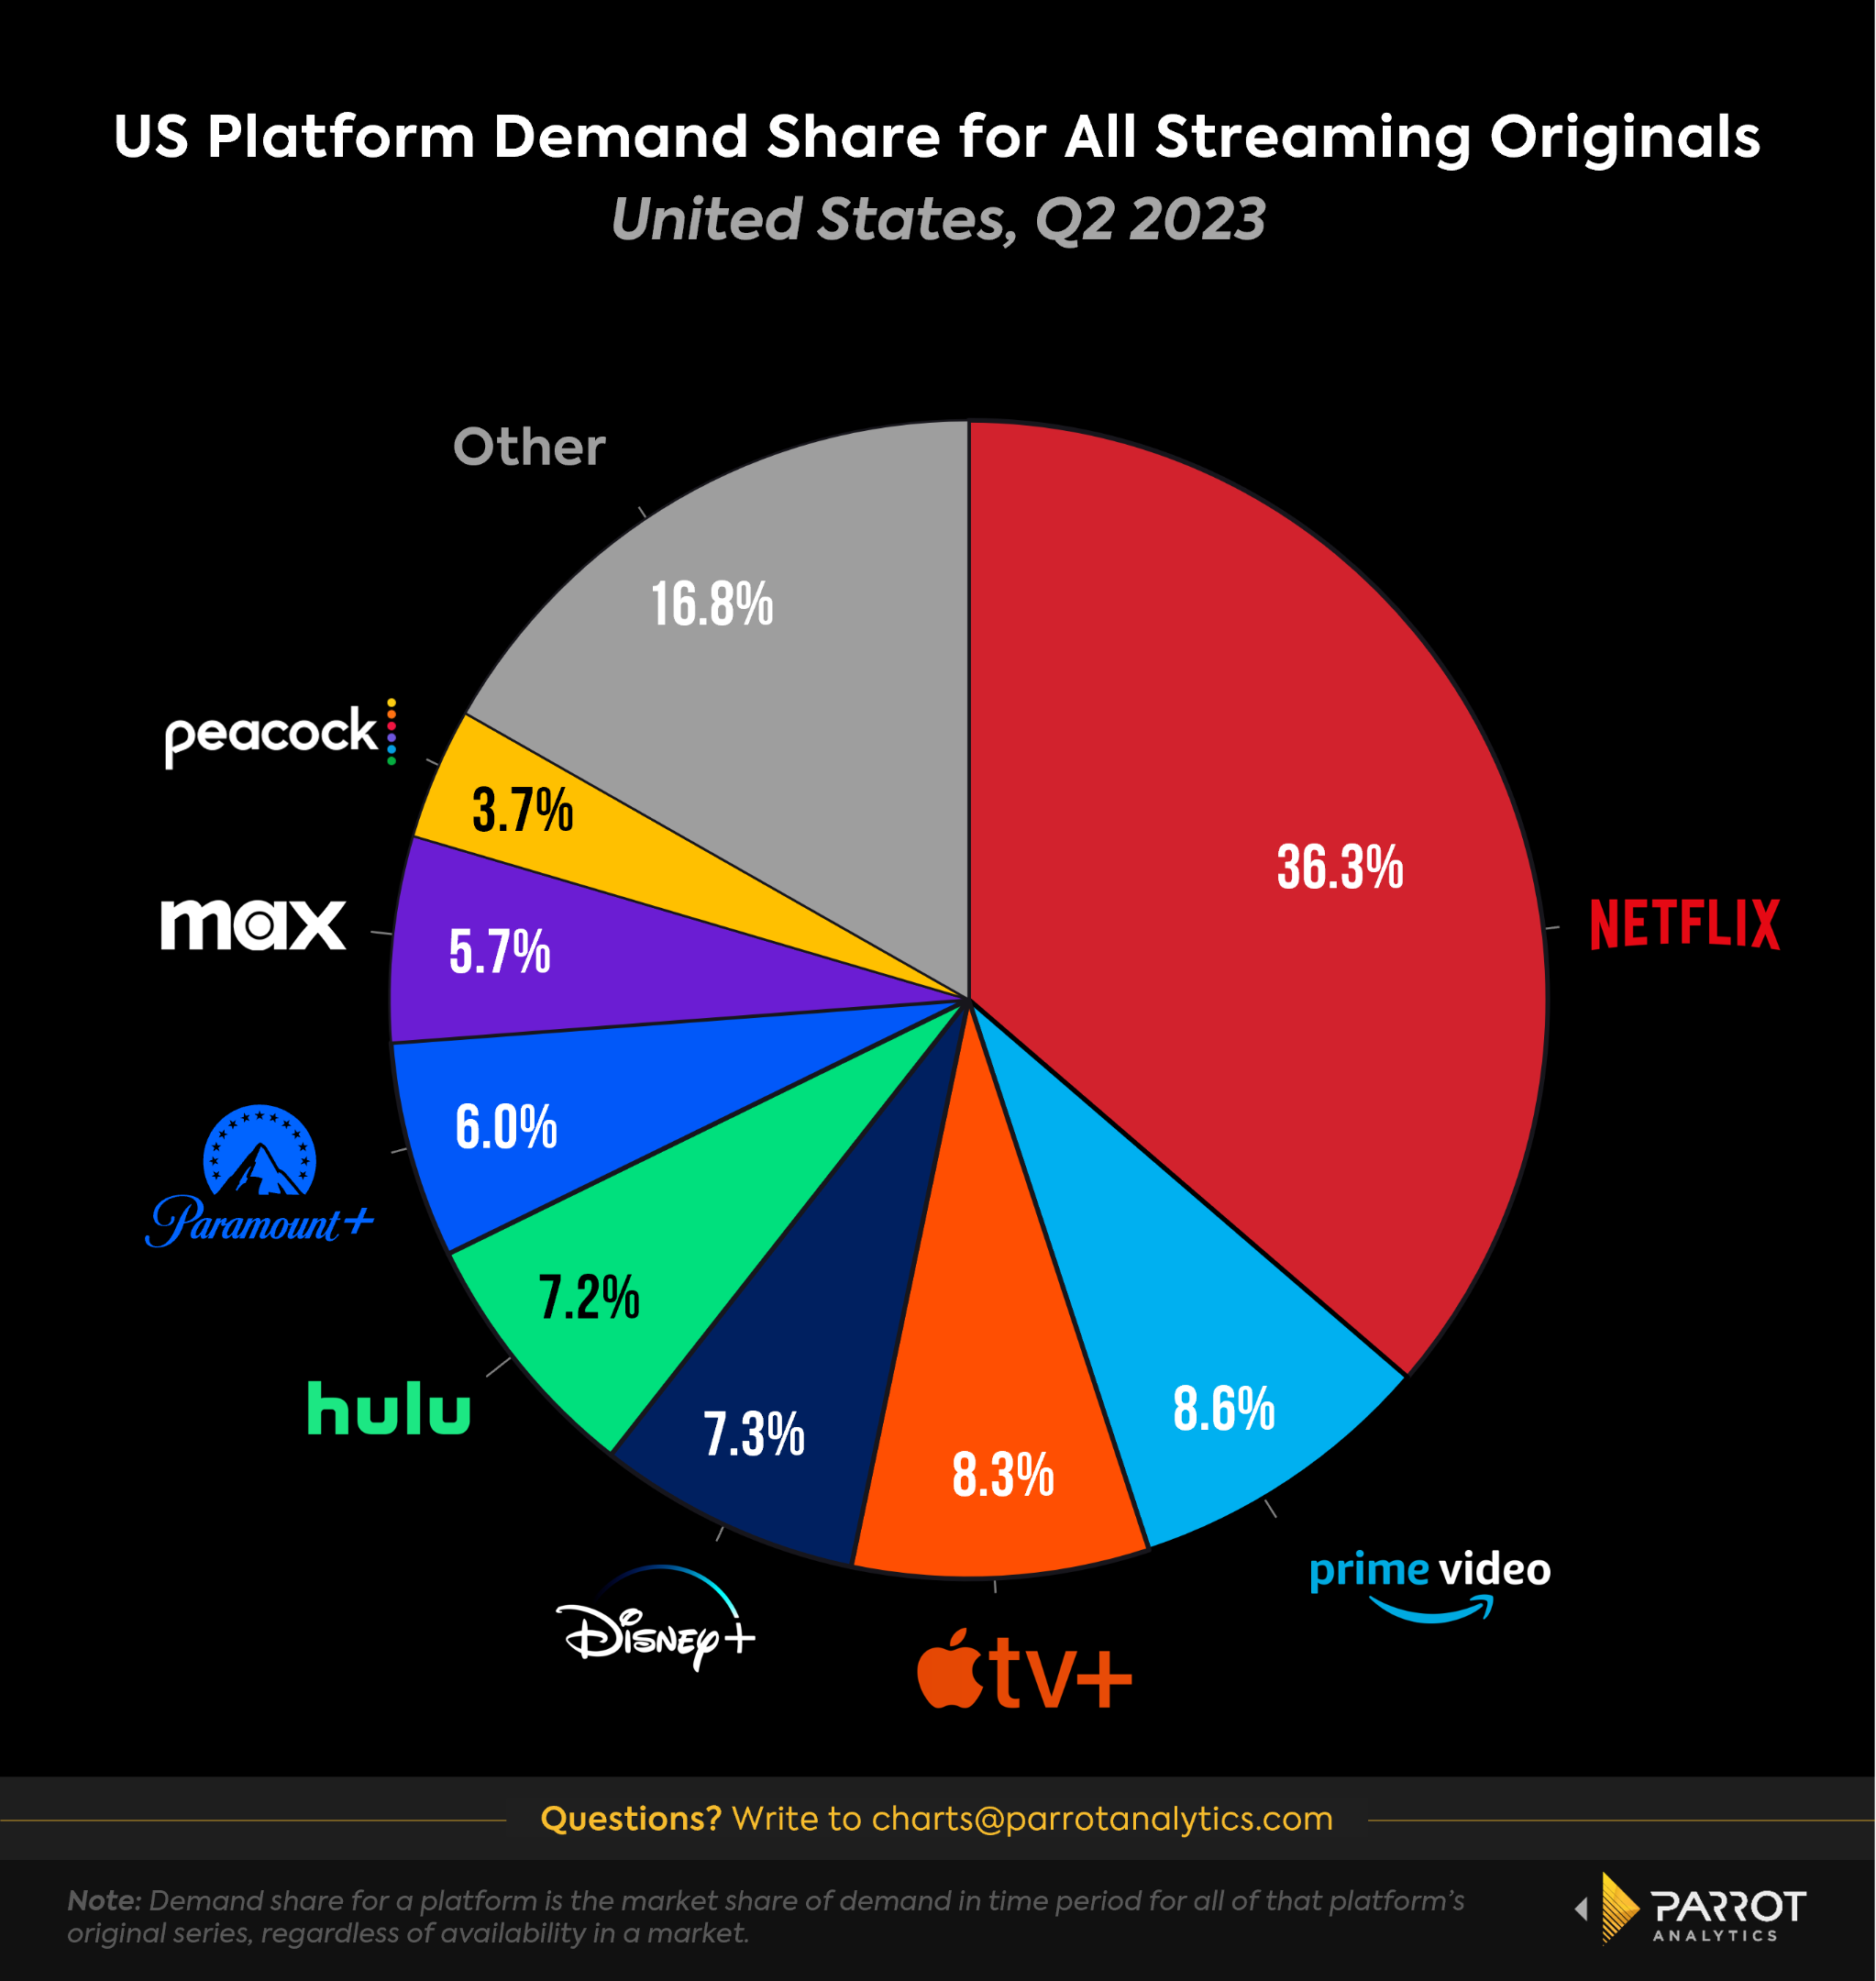
Peacock hasn't hit its subscriber targets consistently. The free tier attracts viewers but converts poorly to paid. The price increases have caused churn. And the biggest problem is that Comcast is competing against platforms that were built natively for streaming with radically lower cost structures. Tubi and Pluto from Fox and Disney respectively offer free ad-supported content at a fraction of Peacock's cost because they don't own major studios. They license content cheaply and fill slots with older shows and news. Peacock is trying to compete on both the free and premium fronts simultaneously, which splits focus and spending. Another structural issue: Comcast's advertising technology stack from the SpotX acquisition still hasn't fully integrated with NBCUniversal's existing ad sales infrastructure. I saw this firsthand during a period when advertisers trying to buy across linear NBC and Peacock faced inconsistent measurement and attribution. The systems didn't talk cleanly for about two years after the acquisition. It's better now but the latency in campaign setup and reporting still frustrates many of the larger agency buyers.
What this means if you're working with or against this model
If you're an advertiser, the actionable insight is that Comcast's CTV inventory is strongest for brands that want household-level targeting and live sports adjacent audiences. It's weaker for niche demographic targeting where you'd be better off on Paramount+ or even Facebook. The pricing is also more flexible than you'd expect during off-peak periods because they're trying to fill inventory to justify their content spend. If you're a competitor, the barrier to entry that matters isn't content. It's the broadband hook. Nobody else can bundle a streaming service with the internet connection that delivers it. That's Comcast's moat and it's not going away unless broadband competition meaningfully increases, which isn't happening in most markets. If you're just trying to understand why Comcast keeps investing in streaming despite massive losses, the answer is that they're not investing in streaming. They're investing in advertising infrastructure and customer retention, and streaming happens to be the vehicle. The numbers only make sense when you stop evaluating Peacock as a streaming business and start evaluating it as a retention and advertising business.

The valuation story holds as long as broadband churn stays low and ad rates don't collapse. Both are under pressure right now. But neither is close to breaking the model yet.


