Why I Started Using The 20 An Hour Biweekly Pay Manifesto
I made $18.50 an hour for three years straight before someone at work mentioned a budgeting method that flipped how I thought about income. It wasn't some fancy investment scheme or crypto advice. It was just a straightforward way of looking at biweekly paychecks and what they could actually cover if you stopped treating every paycheck like a separate mini-budget. The concept itself is simple enough that I almost dismissed it at first. The 20 An Hour Biweekly Pay Manifesto Your Guide To Financial Prosperity is built around the idea that once you lock in twenty dollars per hour as your baseline, everything in your life — rent, groceries, savings, debt — should be calculated against that single hourly number rather than against whatever landed in your bank account on payday. Most people budget from the paycheck down. This method flips it so you budget from the hour up.
The Core Math Behind It
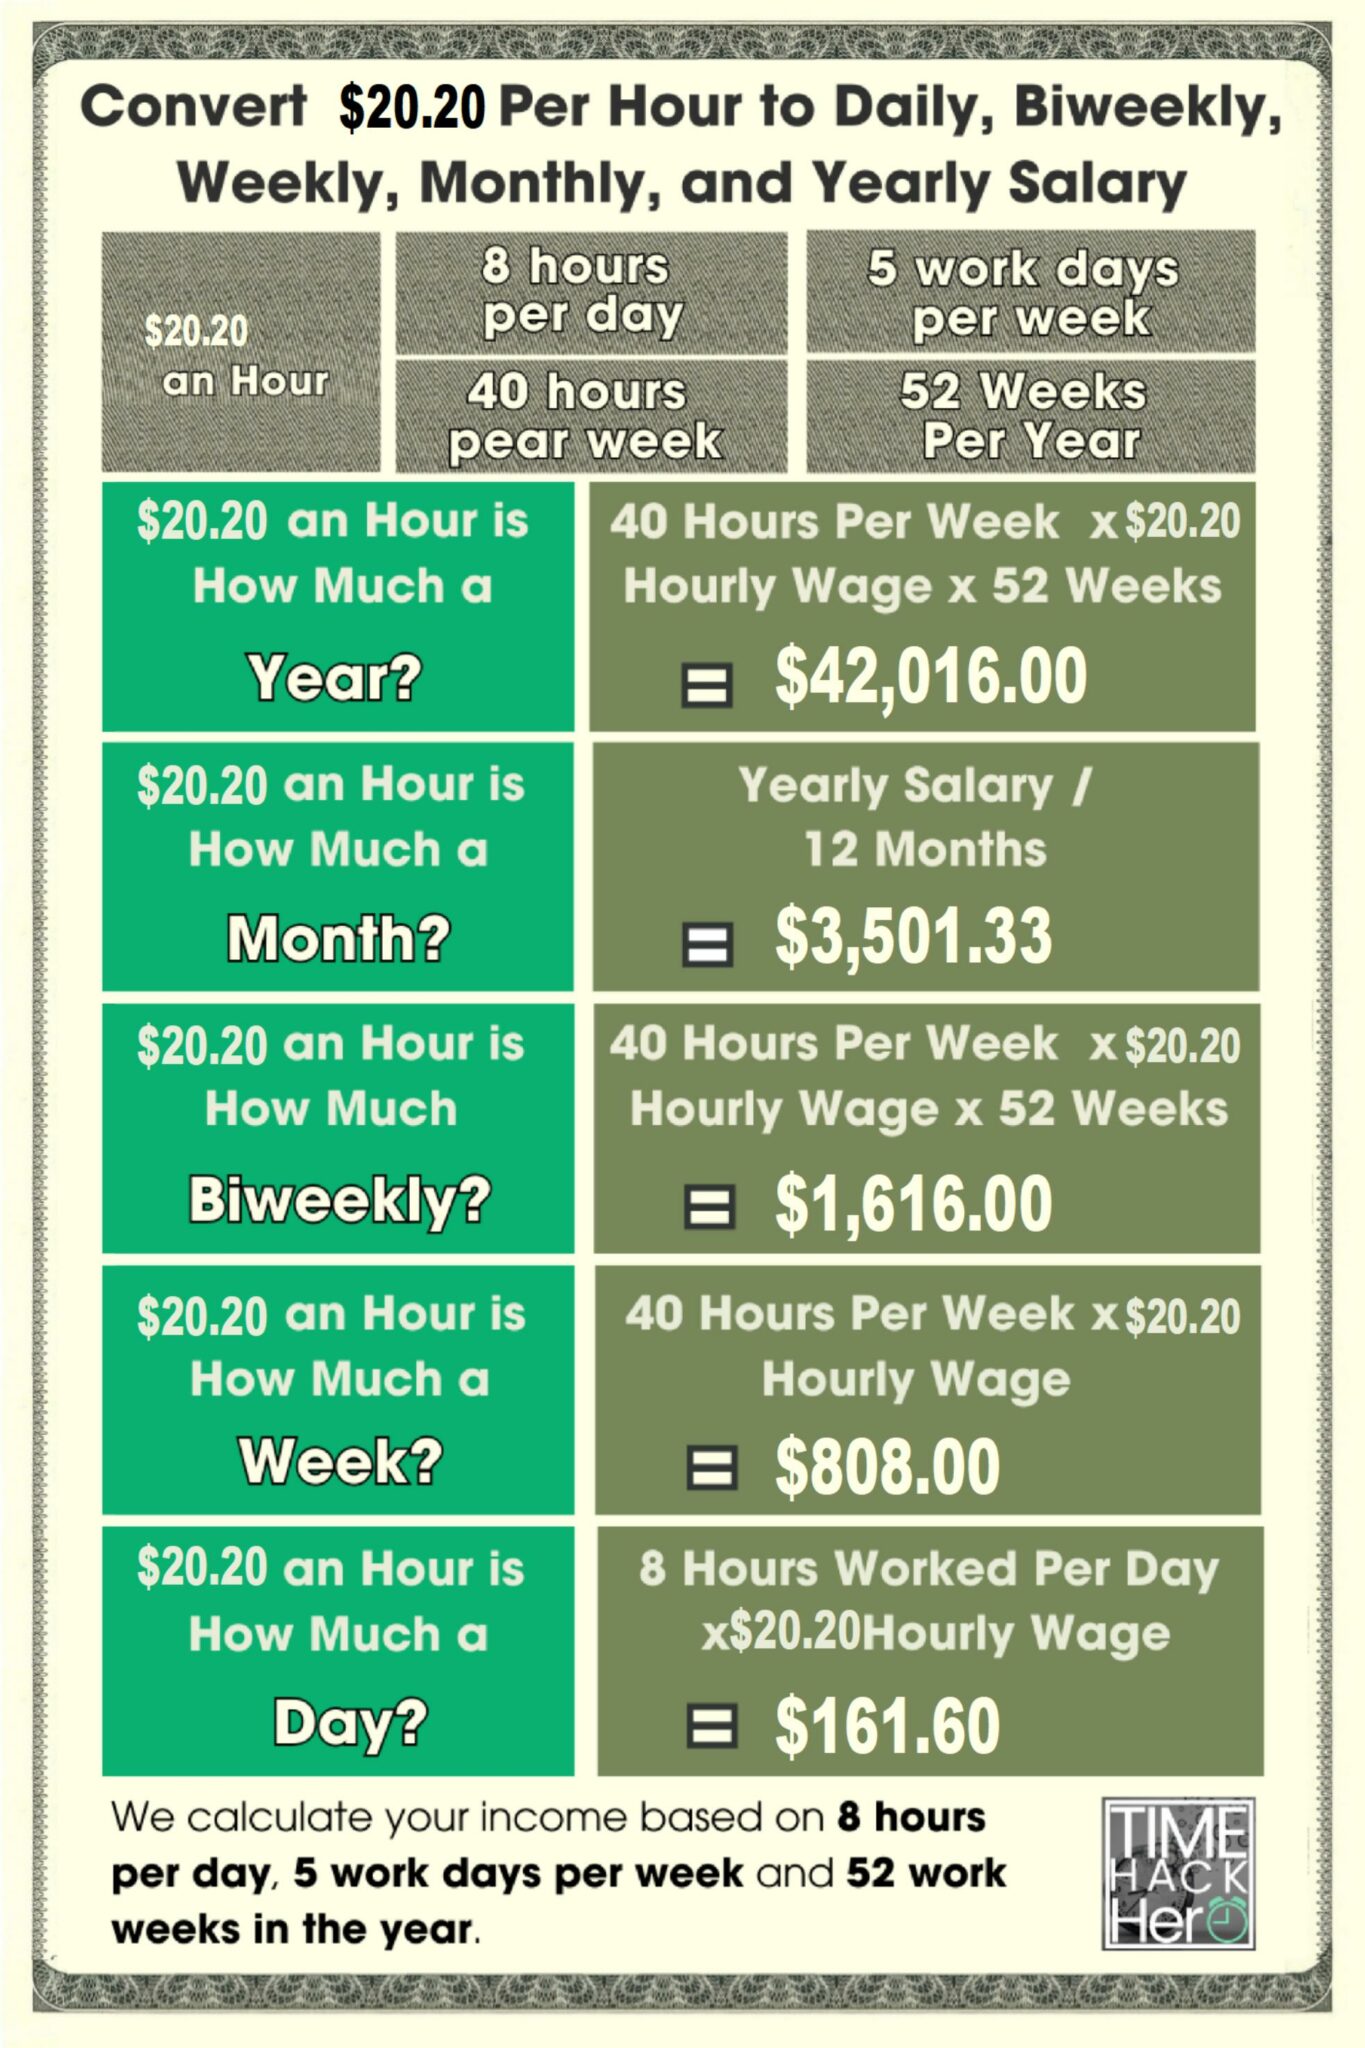
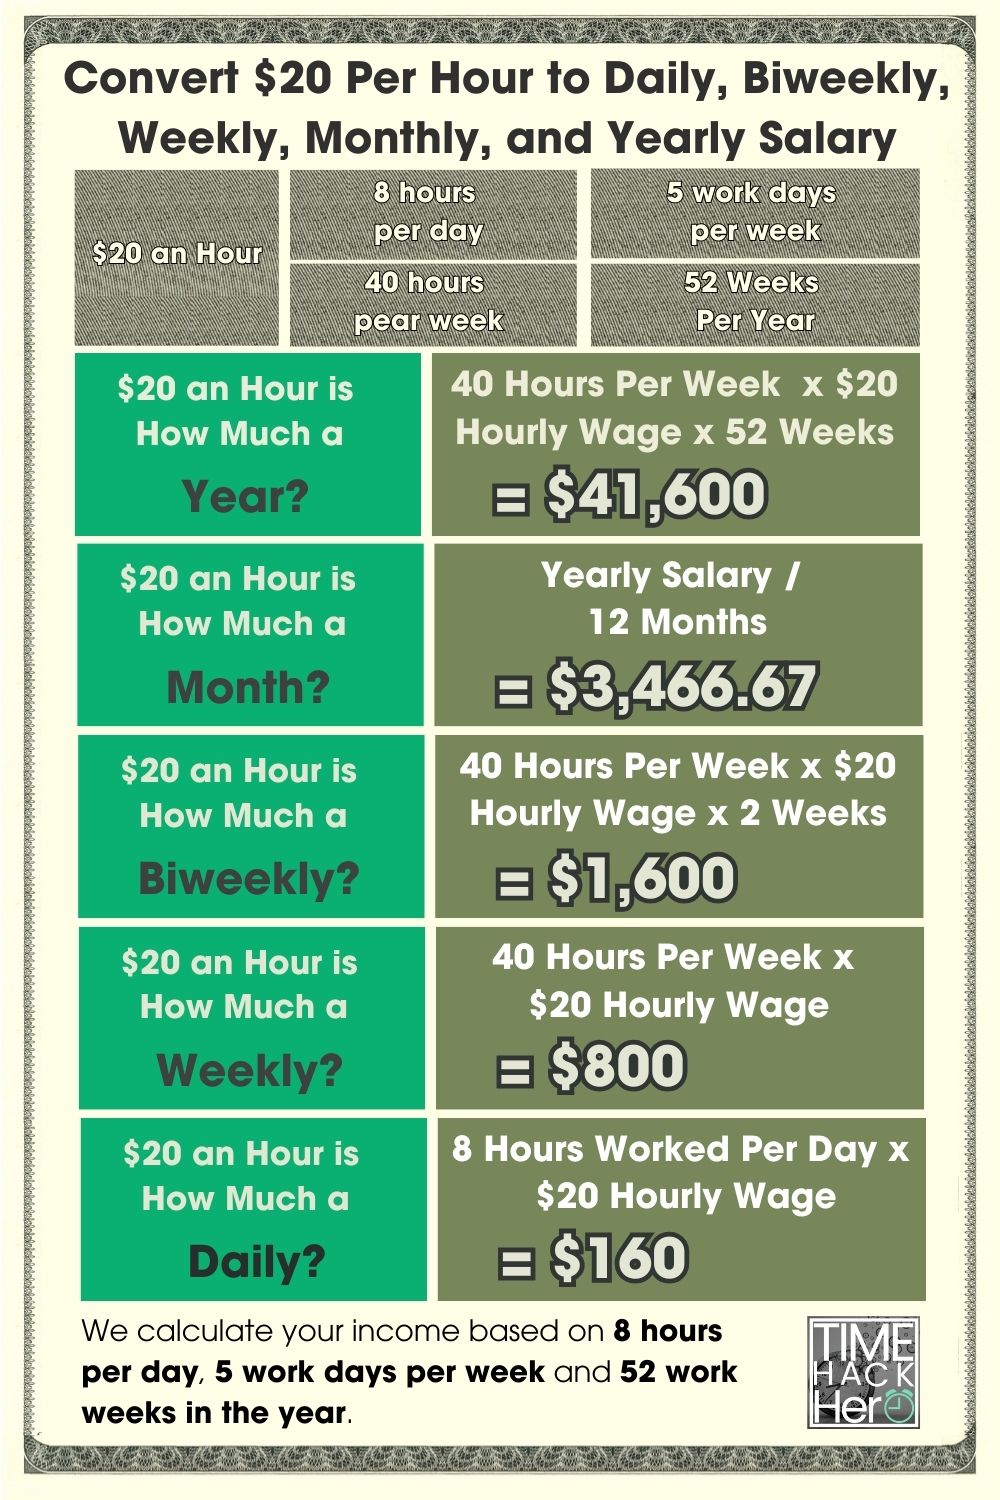
A standard full-time schedule at twenty dollars an hour works out to roughly $41,600 annually before taxes, assuming 2,080 working hours across the year. That means every biweekly paycheck grosses about $1,600. After typical deductions — FICA, federal and state withholding depending on where you live, maybe a 401k contribution if your employer offers one — you're looking at somewhere between $1,200 and $1,400 net per paycheck in most states. Here's where the method diverges from regular budgeting. Instead of allocating dollar amounts to categories out of each paycheck, you assign a dollar-per-hour value to every expense. Rent comes out to $6.25 an hour of your working life. Car insurance is $1.10 an hour. Groceries run about $3.40 an hour. Once you map everything this way, you immediately see whether your chosen expenses are sustainable on a twenty-dollar hourly wage or whether they're already underwater before you factor in savings and emergency fund contributions. I found this framing much harder to ignore than seeing numbers on a spreadsheet because it ties directly to time. You're not just spending money. You're spending hours of your life. That distinction changes how you make decisions about things like upgrading your apartment or switching to a cheaper car insurance plan.
How To Actually Set It Up
The first step is listing every recurring monthly expense you have, then dividing each one by the number of working hours in a month at your current hourly rate. Twenty dollars an hour means roughly 170.67 working hours per month when you account for the standard forty-hour week across four and a third weeks. So a $1,200 monthly rent payment divided by 170.67 equals about $7.03 per hour of your life. Next, write down your target total hourly cost. The manifesto recommends keeping your total under fifteen dollars per hour, which leaves roughly five dollars per hour unallocated for savings, discretionary spending, and unexpected expenses. That fifteen dollar cap is where most people find themselves in trouble because their fixed costs alone — rent, utilities, transportation, insurance, minimum debt payments — often push past twelve dollars per hour before they've even thought about saving anything. When I first ran my own numbers, my fixed costs clocked in at fourteen dollars and sixty cents per hour. I was essentially one broken appliance away from being underwater. The method doesn't sugarcoat that reality. It just shows it to you clearly so you know exactly where to start cutting.
Get the Full Details

A Real Problem I Encountered
The tricky part with biweekly pay is that not every month contains two paychecks. Some months have three, which throws off the entire hourly calculation if you don't account for it. I learned this the hard way back in 2021 when I had three paydays in March and assumed my budget would just stretch accordingly. It didn't. The expenses that month were the same as any other month, but I'd allocated my three-paycheck income across a twelve-month average that implicitly assumed twenty-six paychecks. By April, when only two paychecks hit, I was already behind on several categories. The workaround is to treat every month as having either two or three paychecks and build a rolling twelve-month model rather than a month-by-month budget. Map out which months will have three paydays and intentionally front-load savings and debt payments into those months. When I started doing that, my three-paycheck months became what I call buffer months where I'd move extra money into savings and throw it at whatever debt had the highest interest rate. The two-paycheck months then ran smooth without requiring any adjustments. It added about twenty minutes of setup time each January to recalculate the rolling schedule, but that twenty minutes saved me from scrambling every February and August when the three-paycheck gap hit.
Things The Method Doesn't Tell You
The biggest gap in the standard framing is that it doesn't adequately address income volatility. If you work hourly and your schedule fluctuates week to week, the twenty dollar baseline becomes a theoretical number rather than a practical one. Some months you might average eighteen dollars an hour because of fewer scheduled hours. Other months you pick up overtime and push past twenty-five. The method assumes a steady forty hours a week at a fixed rate, which works fine for salaried employees or people with predictable schedules but falls apart for anyone whose hours vary by more than ten percent month to month. Another thing nobody mentions is tax refund season. The manifesto treats taxes as a static deduction, but your actual withholding changes throughout the year as your tax bracket shifts, as you claim different deductions, or as your W-4 elections get updated. I had a client who realized in October that their W-4 filings from the previous January were no longer optimal because their marginal tax rate had jumped a full bracket. That meant their effective hourly take-home was closer to nineteen dollars and twenty cents, which pushed their total hourly expenses above the fifteen dollar cap even though nothing had changed on the expense side. The fix was adjusting their W-4 mid-year to increase withholding enough to cover the bracket change without overcorrecting and creating a massive refund that tied up cash all year. There's also the issue of healthcare costs that the method handwaves away. If you have a high-deductible health plan with an HSA, the pre-tax nature of those contributions effectively raises your real hourly wage because you're using untaxed dollars for medical expenses. But if you don't have an HSA and you're paying premiums plus out-of-pocket costs from after-tax income, those numbers inflate your hourly burden significantly. A comprehensive vision plan, a decent dental plan, and prescription medications can quietly add two or three dollars per hour to your costs without you noticing until it's too late.
When This Method Actually Works And When It Doesn't
The method works best for people making between eighteen and twenty-eight dollars an hour who have a single income, no dependents, and stable employment with predictable hours. In that window, the math is clean and the fifteen dollar hourly ceiling is achievable with moderate adjustments to housing or transportation choices. It breaks down pretty quickly once you're either below fifteen dollars an hour or supporting multiple dependents on a single income. At twelve dollars an hour, covering basic fixed costs alone pushes you past the fifteen dollar hourly threshold unless you're making significant lifestyle changes. The method won't tell you that your income is the problem. It will just show you that you're over your limit and hope you figure out which category to cut. Sometimes the only realistic cut is increasing your hourly rate, which this framework doesn't help you do. For people in that situation, the more practical approach is to combine the hourly costing method with an income strategy. Figure out what your fifteen dollar hourly ceiling actually looks like at your current wage, identify the gap, and then treat closing that gap as your primary financial goal rather than trying to trim expenses further. No amount of budget refinement will make twelve dollars an hour support a comfortable life with dependents in most parts of the country.
Quick Reference Numbers
If you want to run this yourself without building a spreadsheet, here are the baseline figures. Twenty dollars an hour at forty hours per week gives you roughly $1,600 gross per biweekly paycheck. After estimated deductions of about twenty-two percent for a single filer with standard withholding in a median-tax state, your net comes to approximately $1,248 per paycheck. Annualizing that across twenty-six paychecks yields roughly $32,448 in take-home pay before any voluntary deductions like retirement contributions. Your fifteen dollar hourly spending ceiling translates to about $2,560 per month or $1,280 per biweekly paycheck. If your fixed expenses exceed that per-paycheck amount, you're already above your target before anything discretionary or savings-related enters the picture. That's the point where the method stops being motivational and starts being a diagnostic tool telling you that something needs to change. The reason this approach stuck with me after years of trying different budgeting systems is that it removes the emotional component from financial decisions. You're not failing at budgeting because you spent too much on groceries. You're over your limit because rent went up four hundred dollars and your hourly ceiling didn't move. The numbers don't care about your intentions. They only care about the math, and once you accept that, the method actually becomes useful instead of another source of guilt.