Understanding China's Shadow Banking and Central Bank Influence
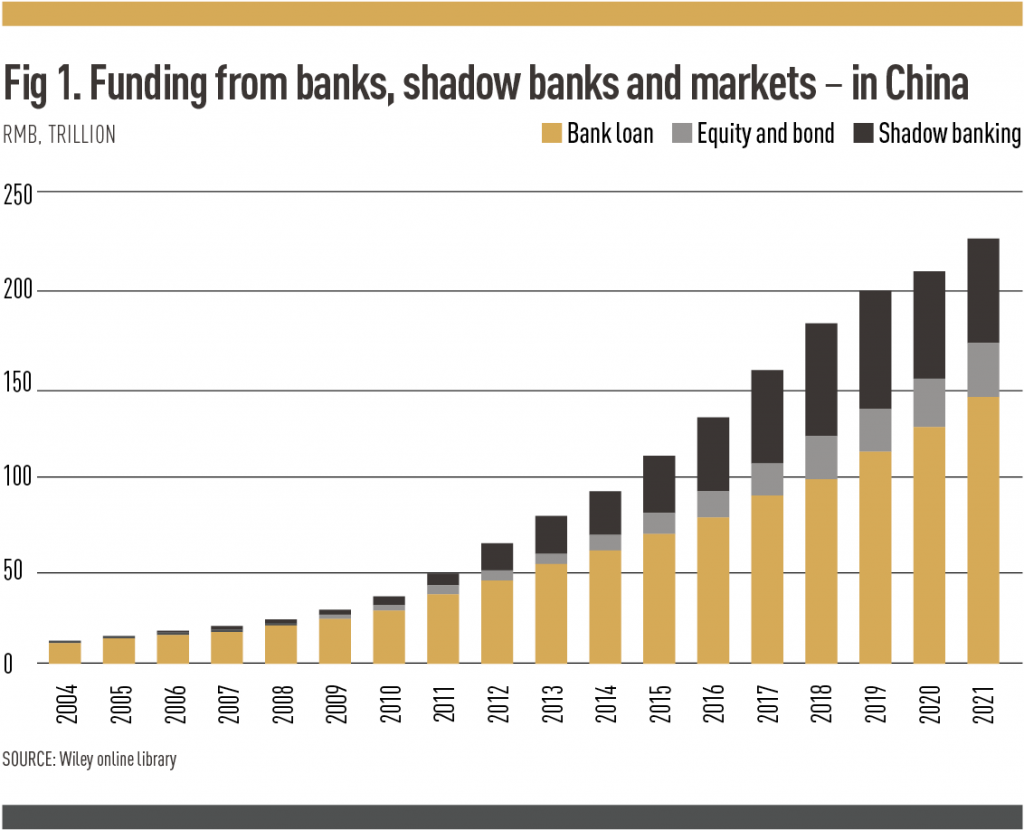
The term shadow banking covers a wide range of financial activities that operate outside traditional banking supervision. In China, this sector has grown enormously over the past fifteen years. The central bank has influenced it through indirect mechanisms rather than direct control. This is not some secret conspiracy. It is a system that developed out of necessity and regulatory gaps. When people talk about 14 trillion in this context, they are usually referring to the total balance sheet of China's shadow banking sector at its peak around 2017-2018. That figure came from data compiled by the China Banking and Insurance Regulatory Commission and various research firms. The number has fluctuated since then due to regulatory crackdowns and economic shifts. What matters more than the exact figure is how the system actually functions day to day. Shadow banking in China works primarily through wealth management products issued by banks, trust companies, and securities firms. These products pool money from investors and lend it to entities that cannot access traditional bank credit. Local government financing vehicles, real estate developers, and smaller private companies are the main borrowers. The people buying these products are mostly institutional investors and wealthy retail customers looking for yields higher than what bank deposits offer.
The central bank influences this system through several channels. The most direct is the reserve requirement ratio, which affects how much liquidity commercial banks have to lend or invest. When the People's Bank of China lowers the RRR, more money enters the system and shadow banking activity tends to expand. When it raises the RRR or conducts open market operations to pull liquidity out, the opposite happens. This is standard monetary policy, not something hidden. Another channel is the lending rate ceiling and floor adjustments. When the PBOC adjusts the benchmark lending rate, it affects the cost of funds for the entire financial system. Shadow banking products price themselves relative to bank loan rates, so any change in the benchmark ripples through quickly. I watched this happen repeatedly during the rate adjustment periods in 2019 and 2020. The yields on wealth management products would shift within days, sometimes hours, of an announcement. The PBOC also uses targeted lending facilities like the medium-term lending facility and the standing lending facility. These provide liquidity directly to certain banks under specific conditions. When banks can get cheap funding from the central bank, they are less dependent on wholesale funding markets. This reduces their incentive to issue off-balance-sheet products and effectively shrinks the shadow banking sector. It is a blunt but effective tool.
Regulatory policy changes are perhaps the most visible form of influence. The asset management in 2018 was a major regulatory shift that forced banks to break the implicit guarantee of principal repayment on wealth management products. Before this rule, investors assumed that bank-issued products would always be honored even if they lost money. After the rule, the market had to price in actual risk. The shadow banking sector contracted significantly as a result. Many smaller products were terminated or merged. What beginners often miss is that shadow banking is not simply illegal or underground activity. It is a parallel financial system that operates with varying degrees of formality. Some vehicles are fully regulated. Others exist in gray areas where the rules are unclear or enforcement is inconsistent. The line between legitimate financial innovation and regulatory arbitrage is blurry in China, as it is in most countries with large shadow banking sectors. I encountered a specific problem when trying to track the flow of funds through these products. The reporting requirements are fragmented across multiple regulators. The PBOC tracks monetary aggregates. The CBIRC regulates bank wealth management products. The CSRC oversees securities and fund companies. The data does not flow between them in a usable way. When I needed a comprehensive view of a particular sector, I had to combine estimates from different sources and adjust for overlap. There is no single dataset that gives you the full picture.
Get the Full Details

The workaround I used was to focus on proxy indicators rather than trying to measure the entire system. Monthly social financing data from the PBOC includes a line for entrusted loans and trust loans, which are two major components of shadow banking. Watching the month-to-month changes in these figures, combined with yield spreads on corporate bonds versus policy bank bonds, gave me a reasonable sense of what was happening. It is not perfect, but it is about as good as it gets with publicly available data. Another counter-intuitive point is that shadow banking can actually increase financial stability in some circumstances. Traditional banks in China are heavily regulated and constrained in what they can lend. When the economy needs credit but banks cannot provide it through formal channels, shadow banking fills the gap. Without it, many viable projects would simply not get funded. The risk is not that shadow banking exists. The risk is that it grows too large relative to the formal system without adequate oversight. The limits and downsides are real though. The system creates opacity. Investors often do not understand what they are buying or who the actual borrower is. There have been cases where the underlying assets were non-performing loans that had been restructured or rolled over multiple times. When these problems surface, they can trigger panic and runs on similar products. The 2022 wave of wealth management product redemption pressure in China is a recent example. Yields on risky products dropped sharply as investors pulled money out.
The central bank has been working to bring shadow banking under clearer regulation for several years. The financial stability report published annually by the PBOC tracks this sector and recommends policy changes. The overall trend has been toward reduction of risk and greater transparency. But the system is still large and still important to the broader economy. Any analysis that dismisses it as a marginal phenomenon is missing something significant about how Chinese credit allocation actually works. If you are looking at this from an investment perspective, the practical takeaway is that shadow banking products offer higher yields but come with higher informational asymmetry. You need to understand the issuer, the underlying assets, and the regulatory environment. Generic yield comparisons between products are misleading because the risk profiles are difficult to assess. I have seen experienced investors lose money on products that looked fine on the surface because the underlying collateral was overstated or the issuer was relying on unsustainable rollover practices. For policymakers and researchers, the challenge is measurement. The absence of good data makes it easy to underestimate or overestimate the sector depending on which indicator you trust. Combining multiple data sources and being transparent about your assumptions is the only reliable approach. There is no shortcut around that.


