How to Actually Claim Your Money From Texas Unclaimed Property
Most people never check, and when they do, they give up after hitting one error message. The Comptroller's website is functional but ugly, and the documentation requirements will trip you up if you aren't prepared. I've processed maybe two dozen claims over the years for myself and other people. Here is how it works, what goes wrong, and what you actually need to do.
Start at
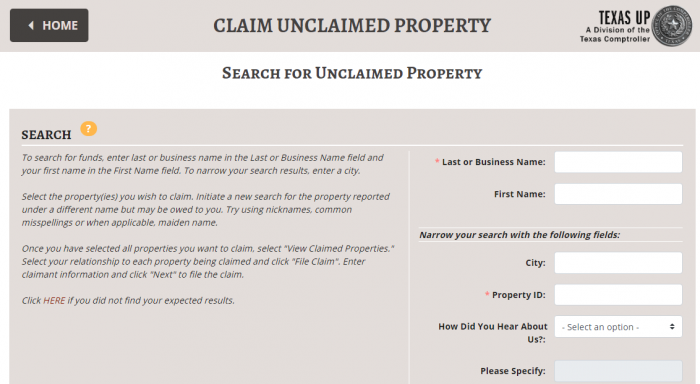
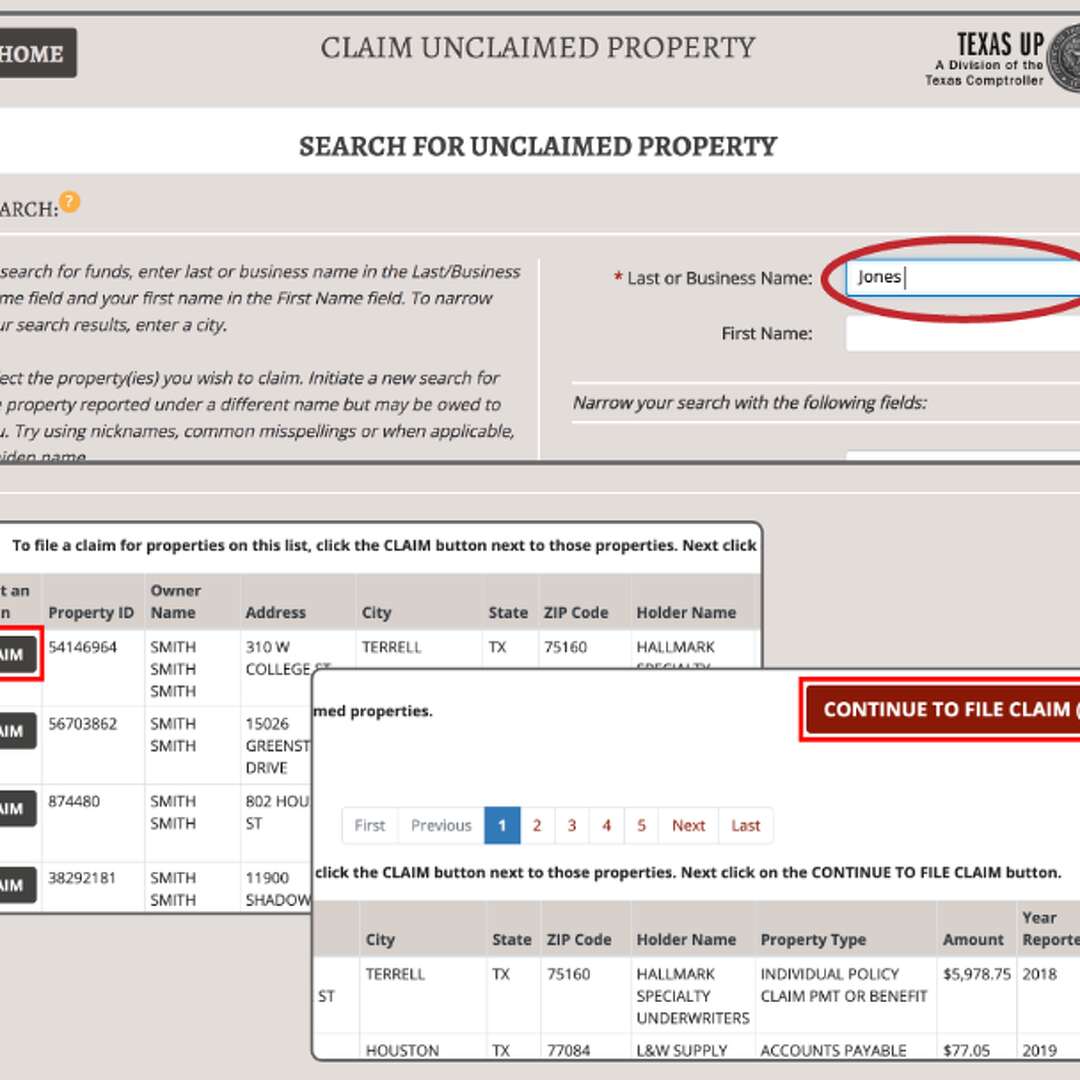
the official Texas Comptroller site and run a search. The query tool covers utilities deposits, payroll checks, uncashed dividends, insurance refunds, safe deposit box contents, and a handful of other categories. You can search by name alone, but adding a city or former address cuts down the noise significantly. Names like "Garcia" or "Smith" will return hundreds of records and most of them won't be yours.
Texas Unclaimed Property Find The Forgotten Cash Owed To You
The search results page shows the holder name, the location, and the amount. The holder is not the state — it's the company that lost your money. A utility company, an insurance carrier, a bank. The state is just the custodian after the holding period expires. That distinction matters because the claim process routes through the Comptroller, but the Comptroller will ask you to verify the holder's identity and provide documents the original company would have already on file.
I learned that the hard way on a claim for an old utility deposit from 2009. The account had been transferred between two different service providers before escheatment. The Comptroller's system showed the current holder as the second provider, but their file had no record of the original deposit date. I spent three weeks on hold with customer service before realizing I could pull my own billing history from the second provider's archive and submit it as secondary documentation. The claim went through once they matched the account number and the deposit amount to the escheat record. If you are dealing with a utility or telecom claim, do not skip pulling your own records first. It saves the processing time from 6 to 8 weeks down to roughly 3.
The standard claim form is available on the Comptroller's site as a PDF. You need a notarized signature unless you submit the form through the online portal, which has its own authentication step. You will also need a government-issued ID and proof of your current address. If the unclaimed property is in the name of someone who is deceased, you need a death certificate and documentation establishing your authority to claim — an executor appointment or small estate affidavit depending on the amount. Texas uses a $100,000 threshold for simplified estate procedures, which means claims under that amount can sometimes go through without full probate paperwork if you have the right supporting documents.
Here is something the FAQ section does not tell you: the state conducts periodic outreach. If your name appears in the database and you have filed a tax return in Texas within the last few years, the Comptroller may send you a notification letter before processing your claim. This happened to me with a forgotten security deposit from a rental company. The letter arrived six months after I had already submitted a claim. They closed my duplicate submission and issued payment on the original one. Not a big deal, but it confirms that checking the database yourself is still the fastest route. Waiting for a letter can take 12 to 18 months.
The processing timeline is another area where expectations matter. Claims submitted online with complete documentation typically resolve in 4 to 6 weeks. Mail-in claims take 8 to 12 weeks. Rejections for incomplete documentation add another 2 to 4 weeks depending on how quickly you can resubmit. Most rejections happen because the address on your ID does not match the address on the unclaimed property record and you did not provide a secondary proof of residency. A utility bill or lease agreement from the past year solves this in most cases.
Do not use third-party services unless you have a specific reason. The Comptroller's website is free. Third-party sites charge between 10 and 25 percent of your recovery and do the same search you can do yourself. I have seen people submit claims through these services and still get stuck on the documentation requirements because the service never actually helped them gather the right proof. You are better off doing it yourself and spending the time on research instead of paying a fee.
The real limitation is that not every type of lost asset ends up in the Texas database. If your money was held by an out-of-state company that never remitted to Texas, the Comptroller will not have it. You would need to check the NASPLA unified database at
Unclaimed.org, which aggregates records from all states. That process is slower and the interfaces are worse, but it is the only way to find property that belongs to another jurisdiction.
Another edge case that catches people: the dormancy period in Texas is five years for most property types, but it varies. Mining severance taxes take ten years. Some insurance policies have different rules depending on the policy type and when the premium was last paid. If you are searching for something specific, look up the dormancy period for that category rather than assuming five years across the board.
The amount of your recovery is not negotiable. The Comptroller will pay the exact balance shown in their records. There is no haggling, no settlement offer, no interest accrual while the money sits in state custody. This is both a feature and a frustration — you get your money back eventually, but you do not get compensated for the time it was gone.
One final detail that saves people from wasting hours: if you find a record but the amount is small, like under $50, some holders may have already reconciled it through internal write-off procedures and removed it from the active database. Run a broader name-only search if your initial query returns nothing. The database is updated quarterly, so records can appear or disappear between cycles.