Texas Succumbs To Sizzling Summer Sales A Zillow Forecast For Your Dream Home In The Lone Star State
Samantha
2025-04-02
How Zillow's Texas Summer Forecast Actually Plays Out
Zillow publishes annual housing market forecasts for every state, and Texas consistently ranks as one of the highest-volume markets in the country. The data that comes out each spring usually shows a meaningful acceleration in home price growth between May and August. That doesn't mean prices go to the moon. It means the rate of change shifts, inventory tightens, and the competitive dynamics for buyers change in ways that are easy to miss if you're only looking at the headline number.
I worked in real estate analytics for over a decade before moving into consulting, and I've seen too many people treat Zillow's forecast as a crystal ball. It isn't. It's a directional tool built on regression models that pull in existing MLS data, mortgage rates, employment shifts, and population movement patterns. The model does a decent job of capturing broad trends. It's less reliable at predicting specific zip code behavior, especially in markets where new construction is moving faster than existing home sales.
Texas Succumbs To Sizzling Summer Sales A Zillow Forecast For Your Dream Home In The Lone Star State
When Zillow released its latest Texas outlook, the headline figure was a projected 5.2% year-over-year price appreciation through late summer. That sounds moderate until you break it down. Dallas-Fort Worth came in at 4.8%. Houston at 3.1%. Austin at 7.4%. San Antonio at 4.3%. The dispersion matters more than the statewide average because the average hides the fact that two buyers with identical budgets could face completely different markets depending on which metro they're targeting.
The summer acceleration isn't theoretical. Here's what happens in practice: inventory drops by roughly 18 to 22 percent compared to the winter months in the major metros, and days on market fall from an average of 55 days in January to around 32 days in July. That's a meaningful shift. Homes that would have sat for weeks in February get multiple offers within four days of hitting the market in July.
I learned this the hard way a few years ago when I was helping a client buy in Round Rock. The Zillow forecast had flagged the area as appreciating, but it didn't capture the micro-dynamic: a new subdivision was completing Phase 3 that spring, which temporarily flooded the area with move-in ready inventory while the surrounding neighborhoods were simultaneously seeing reduced resale supply. The forecast was right about direction but wrong about timing for that specific pocket. My workaround was pulling the Travis County appraisal district data directly and cross-referencing it with builder permit filings from the City of Round Rock's public works database. I found that three competing developments were all delivering units in July and August, which meant we could confidently wait instead of bidding aggressively. We closed three weeks later at a price 6 percent below what similar homes had sold for in June.
What the Forecast Gets Right and What It Misses
Zillow's model handles macro trends well. Population inflow to Texas is real and sustained. Net migration alone added approximately 450,000 people to the state between 2022 and 2024, and that demand creates structural pressure on housing supply. The model captures that. Mortgage rate sensitivity is also well-modeled. When rates move from 6.5% to 7.2%, the forecast adjusts purchasing power calculations appropriately.
Where it consistently underperforms is in markets experiencing rapid new construction. Zillow's algorithm relies heavily on comparable sales data from the past six to twelve months. If a neighborhood has few existing home sales because developers are selling new builds directly, the model has thin data to work with. I've seen it underestimate price growth by 2 to 3 percent in areas like Pflugerville and Leander where new construction accounts for over 60 percent of total transaction volume.
There's also the insurance factor that most forecasts don't adequately weight. Texas property insurance premiums have increased between 25 and 40 percent in certain coastal and central Texas counties over the past two years due to reinsurance costs and hurricane exposure. A home that Zillow's forecast suggests you can afford based on price alone may become unaffordable once you factor in the monthly insurance payment. I had a client in Galveston who was pre-approved for a $420,000 home, then discovered the annual premium was nearly $6,800 after their first insurer dropped them. That changed their effective purchase price by roughly $15,000 in monthly carrying costs.
How to Use the Forecast Without Being Misled By It
Start by looking beyond the headline number. Pull the metro-specific breakdowns and compare them against the last three years of actual realized data, not just the forecasted figures. Zillow tends to be slightly conservative in Texas markets, so the realized appreciation often exceeds the forecast by about half a percentage point in strong months.
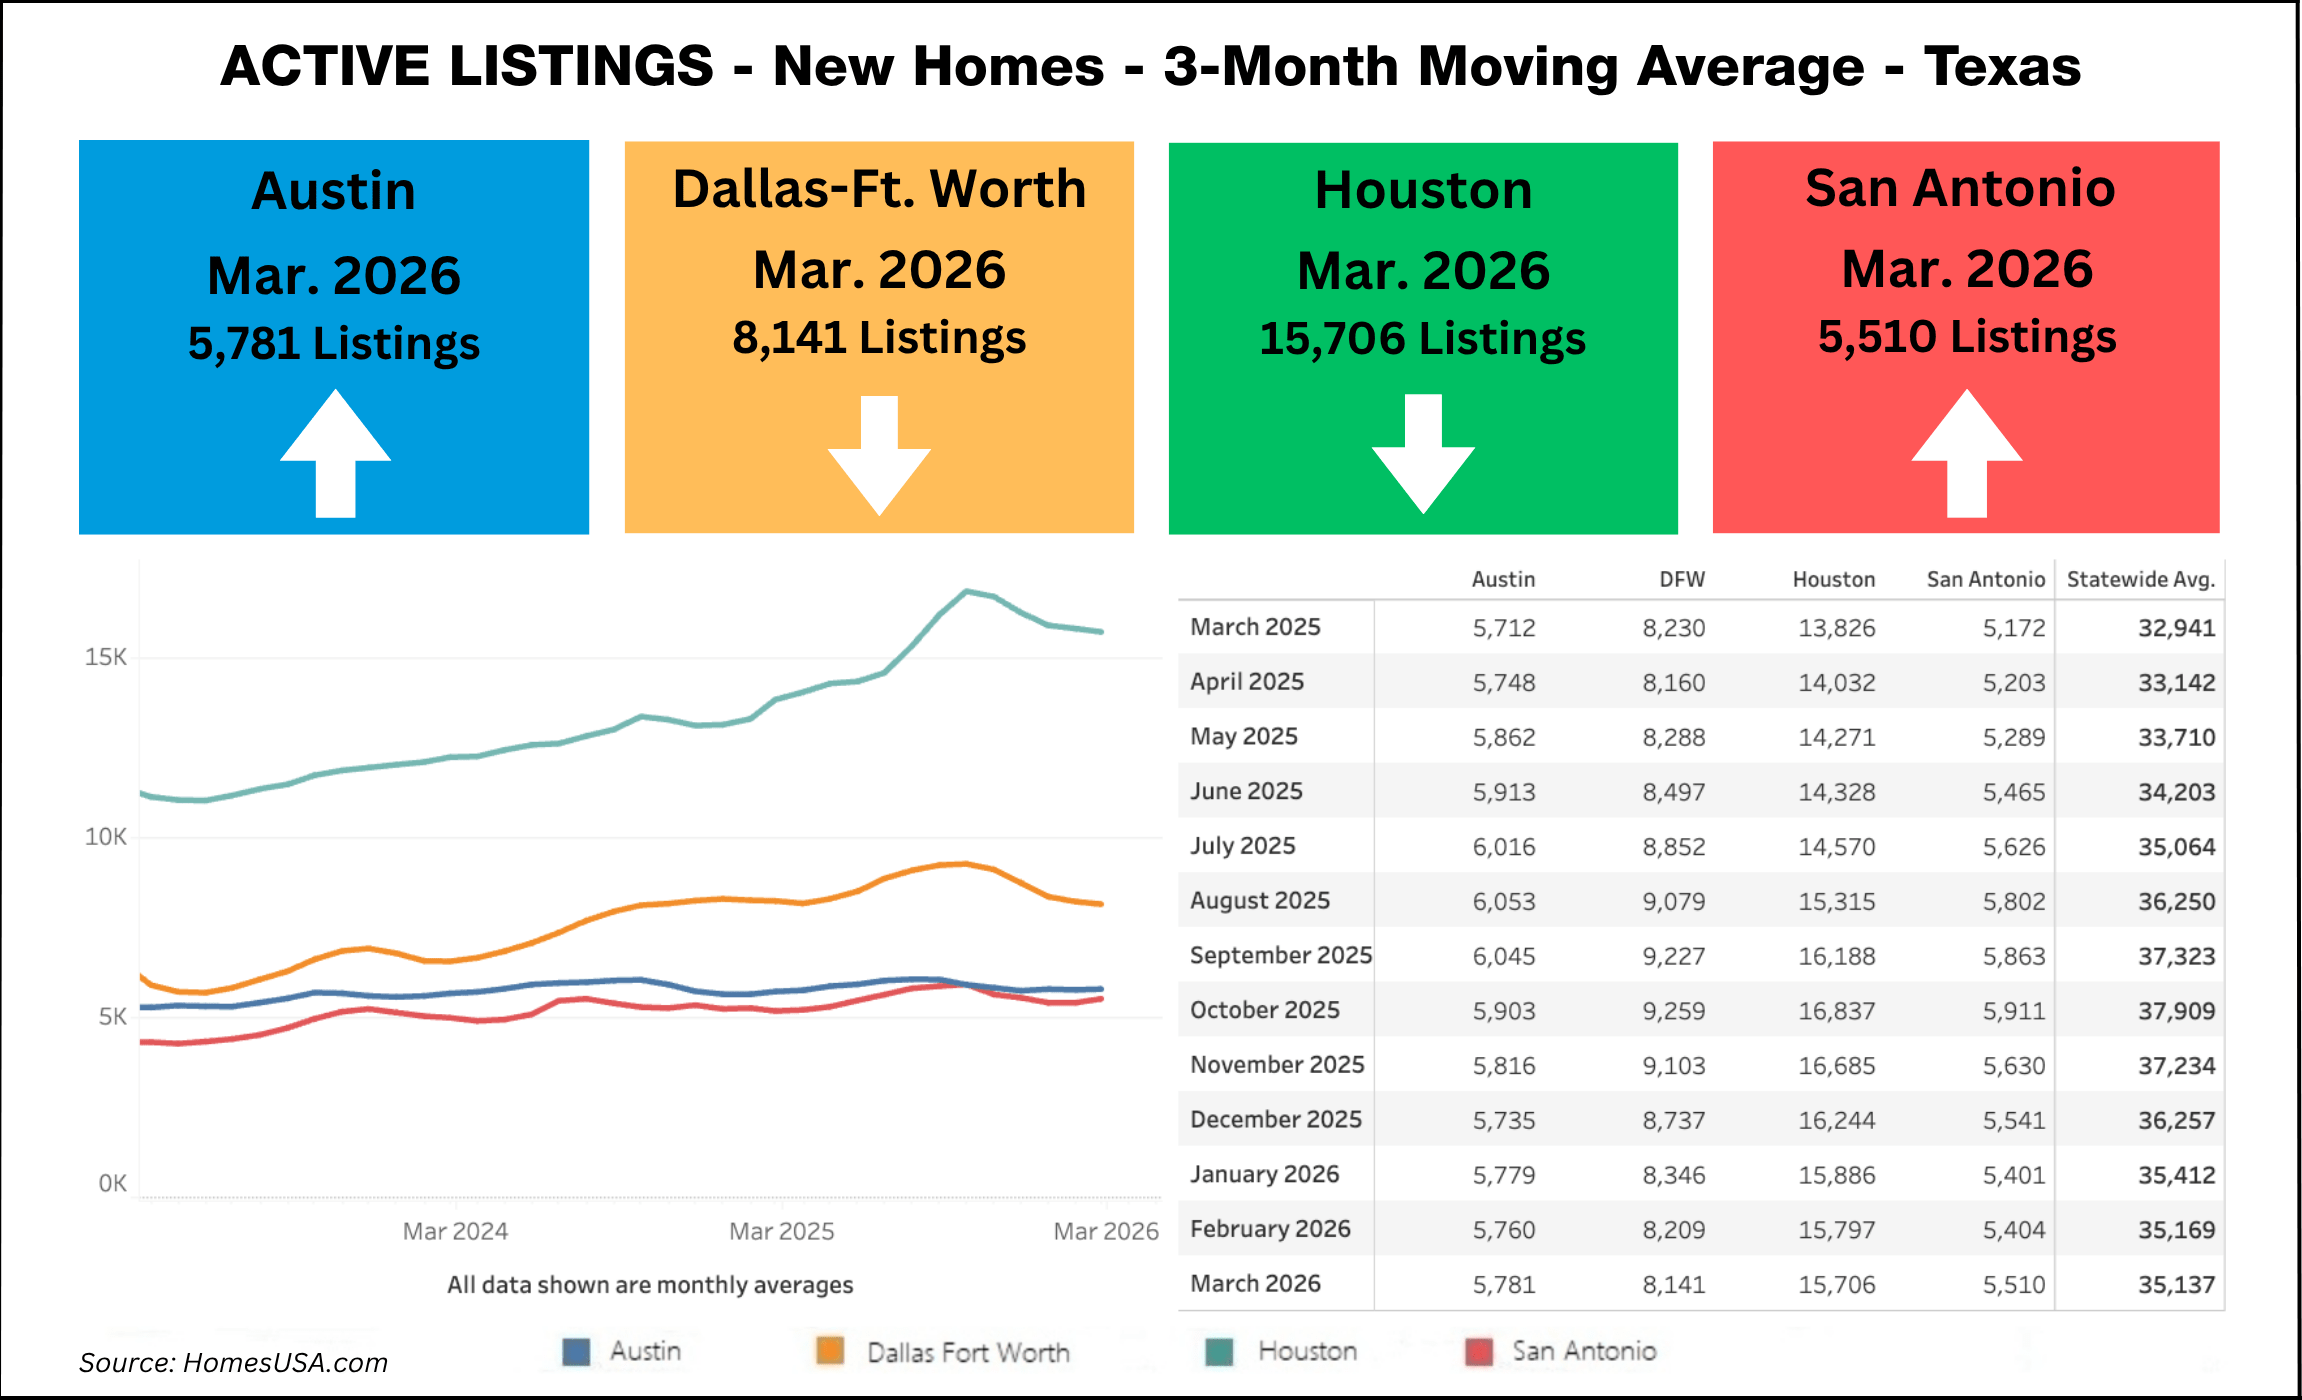
Check the inventory trajectory separately from the price trajectory. Price appreciation means nothing if inventory is collapsing and there's nothing to buy. In Austin, for example, the forecast showed strong price growth heading into summer 2024, but the active listing count dropped below 3,000 for the first time since 2018. That inventory constraint is what actually drove the prices, not demand surging beyond historical norms.
Use the forecast as a timing signal, not a price signal. When Zillow projects summer acceleration for a market you're targeting, plan your search window accordingly. If you can delay buying until September or October, you'll typically find better inventory selection and slightly less competition. If you must buy in June or July, you need to move fast and be prepared to compromise on property condition rather than location.
One thing most people don't consider: the forecast doesn't account for local school district rezoning activity. In Texas, a single school boundary change can shift a neighborhood's price trajectory independently of any broader market trend. I track this manually by monitoring the Texas Education Agency's public boundary change filings and cross-referencing them with Zillow's forecast data. It's a small thing that separated reliable decisions from expensive mistakes for several clients.
When the Forecast Is Essentially Useless
Be honest about the limitations. If you're looking at a rural county with fewer than 200 annual transactions, Zillow's model has almost no predictive power for that specific area. The sample size is too small. The algorithm smooths over outliers, which means it can't reflect the kind of idiosyncratic pricing you see in counties where a single large land sale or a new industrial development skews the entire market.
The forecast also doesn't help with fixer-uppers or non-standard properties. Custom-built homes, older ranch properties, and anything that doesn't have sufficient recent comparable sales will have unreliable Zestimate values attached to them. The underlying model simply can't calibrate properly without enough transaction data in the neighborhood.
If you're working outside the major metros or in rural areas, I'd recommend supplementing the Zillow forecast with direct data from your local MLS or the county appraisal district. The raw numbers there are more granular and more current than what any national model can produce.
Gallery Texas Succumbs To Sizzling Summer Sales A Zillow Forecast For Your Dream Home In The Lone Star State
Texas Home Sales Increased Slightly Overall in Q1 of 2026
Texas new home market shows spring surge as pending sales forecast a ...
Texas Home Sales Increased Slightly Overall in Q1 of 2026 | Business ...
Texas New Home Sales Continue to Decline as Year-Over-Year Inventory ...
Report: Texas sees record surge in $1M home sales | kvue.com