
Finding Actually Habitable Houses Below Six Figures In Texas
The market for Texas Homes For Sale Under 100K A Diamond In The Rough In The Lone Star State is real, but most people walk into it completely unprepared. I've been tracking this segment for about eight years, and the disconnect between what listings promise and what you actually get is where most buyers bleed money before they even close. Here is what you need to know before you start looking.
Where The Deals Actually Live
You will not find these houses in Austin, Dallas, Houston proper, or San Antonio. The prices simply do not exist there anymore. The viable markets are East Texas towns like Lufkin, Nacogdoches, and Palestine. West Texas communities around Midland and Odessa sometimes have older stock in the low five figures, though those tend to be cash-only properties with foundation issues. The Panhandle – Amarillo, Lubbock, Plainview – has a few pockets, but inventory moves fast there because out-of-state buyers have been circling for years. My working theory, based on watching deals come in and out of my inbox daily, is that the best opportunities sit in towns with a single major employer. A failing mill town like Corsicana or Enid has cheaper houses but also declining property values. A town with a growing hospital system or a new logistics warehouse – think Sherman or Tyler outlying areas – tends to hold value better even at the bottom tier.
The Inspection Problem Nobody Talks About
This is the part that costs people. When a house sells for $85,000 and needs $60,000 in repairs, you are basically paying full price. I had a client last year who fell in love with a 1978 mobile home on three acres near Sherman. The roof looked fine from the street. The foundation was level enough. The listing photos were bright. He went in blind because he did not want to offend the seller, and within forty-eight hours of moving his stuff in, the slab cracked and water came through the crawl space. Repair estimate was $47,000. He sold it six months later at a loss. The workaround is simple but annoying: bring your own inspector and make the offer contingent on a satisfactory inspection regardless of what the seller says. Some sellers in this price range get territorial about inspections because they think it gives you leverage to renegotiate. Tell them straight up that you are not trying to lowball, you are trying to not lose your shirt. Most reasonable sellers will agree. The unreasonable ones are the ones you want to avoid anyway.
Get the Full Details
How To Actually Buy One Of These Houses
Start by getting pre-approved, not pre-qualified. Pre-qualified means nothing to a seller. Pre-approved means a lender has looked at your credit, your income, and your debt-to-income ratio and is willing to write a letter saying they will lend you a specific amount. You need that letter in hand before you make an offer on a $90,000 house, because the sellers in this bracket are often elderly owners or inherited properties who need certainty, not hope. Financing a sub-$100K property in Texas is possible but narrow. Conventional loans have minimum property condition requirements that many of these houses fail. FHA loans are more forgiving but require an appraiser to sign off on the condition, and if the house does not meet HUD minimums, the loan falls apart. The most reliable route is a renovation loan – either FHA 203(k) or a HomeStyle renovation loan from Fannie Mae. These let you finance the purchase price and the repairs into a single mortgage. The downside is that the process takes longer, usually 45 to 60 days from contract to close, compared to 30 days for a standard purchase. If you have cash, things move faster. Cash offers in this price range often close in two weeks. But do not assume cash is always the right move. I have seen cash buyers overpay because they assumed their advantage gave them pricing power. In reality, a well-structured conventional offer with a clean inspection contingency is often more attractive to a motivated seller than a sloppy cash offer with no contingencies.
The Title And Lien Trap
This is the counter-intuitive part beginners miss. Houses under $100K in Texas frequently come with title complications. Not always, but often enough that you should budget extra time for a title search before you waive that contingency. I had a situation in 2023 where a property in Corsicana had an old mechanic's lien from a roof job in 2019 that nobody knew about. The seller was the original owner's nephew who had inherited the house through a family transfer that never went through probate properly. We spent three weeks untangling the lien and the heirship affidavit. The house was a steal at $72,000, but we almost walked away because the probate mess was worse than expected. The workaround: order a title commitment early, preferably in the first week after contract. Do not wait until the end of escrow. If there is a cloud on the title, you want to know at day ten, not day forty. Factor in $300 to $600 for a title search and another $500 to $1,200 for title insurance if problems surface. This is not optional spending. It is the difference between owning a house and owning a lawsuit.
What These Houses Actually Look Like
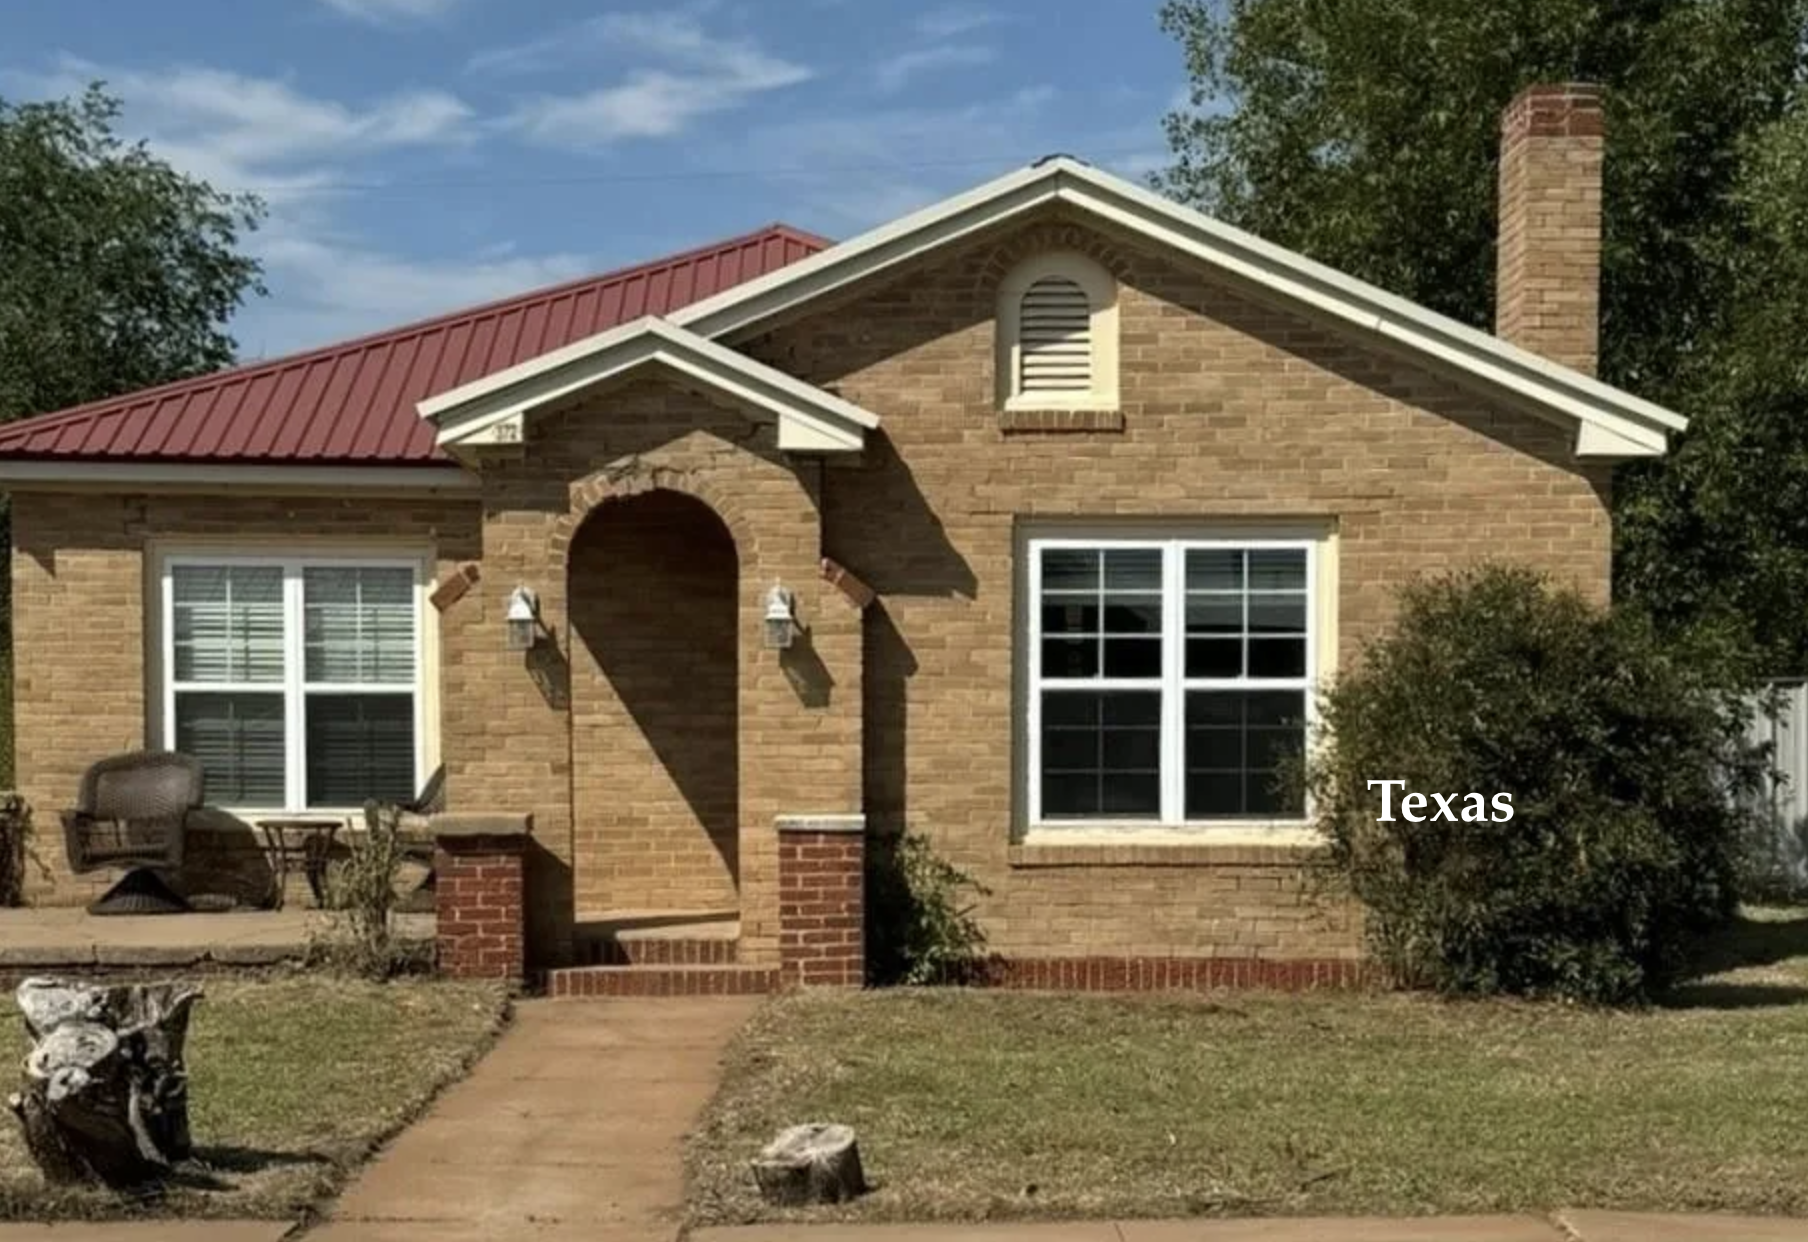
Most homes in this price range were built between 1960 and 1985. They are single-wide or double-wide manufactured homes on owned land, or modest frame houses on concrete slabs. You will see a lot of 1970s split-levels and rambler-style homes with original plumbing and electrical. The square footage is usually between 900 and 1,400. Three bedrooms and one bathroom is the standard configuration. Two baths at this price point is rare and usually means one of the bathrooms is half-bath converted from a closet. The yards are typically unfinished. Expect overgrown vegetation, maybe a shed that leans slightly, and a driveway that is more gravel patch than pavement. This is not a negative in itself. Landscaping and hardscaping are cheap to fix. What is not cheap to fix is the HVAC system, the roof, and the foundation. Budget conservatively: assume the roof has ten years or less of life remaining, the air conditioner will need replacement within three years, and the foundation needs monitoring even if it looks fine today.
Neighborhood Selection Matters More Than You Think
I know this sounds obvious, but at the $100K price point, neighborhood selection is the single biggest determinant of whether this house becomes an asset or a liability. A $85,000 house in a declining neighborhood with rising vacancy rates will stay at $85,000 or drop to $70,000 over five years. A $95,000 house in a stable neighborhood with owner-occupants will likely appreciate to $120,000 to $140,000 over the same period, especially if you put $30,000 into updates. Check the vacancy rate for the zip code. Check the median days on market for recent sales in the area. Look at whether new construction is happening nearby. If builders are going into the neighborhood, that is a positive signal even if they are building $250,000 homes. It means the area is improving, not stagnating. I use the Texas Real Estate Commission's published sales data and cross-reference it with county appraisal district records. It takes about twenty minutes and saves you from buying into a dead zone.
The Renovation Math That People Mess Up
Here is the mistake: people look at the purchase price and the after-repair value and think the spread is profit. It is not. The spread is your budget, minus closing costs, minus holding costs, minus the value of your time. Let me walk through a real example. I helped a buyer last year purchase a 1982 brick veneer home in Navasota for $89,500. The comparables after repair were running around $155,000 in that neighborhood. Simple math says $65,500 in equity. Except the roof needed full replacement at $14,000. The HVAC was twenty years old, so we budgeted $8,500. The kitchen was original, so $12,000 for cabinets, counters, and appliances. The bathrooms needed updating, another $9,000. Flooring throughout, $7,000. Exterior paint and trim, $4,000. That is $54,500 in renovations before you touch a single wall inside. So the actual equation is $155,000 minus $89,500 minus $54,500 minus $3,500 in closing costs minus $1,200 in inspection and title work. That leaves about $6,300 in projected equity after all costs. Not bad, but not the windfall the comps suggested. And that assumes everything goes smoothly, which it never does.
When To Walk Away
This is important and rarely discussed. You need a clear set of conditions where you abort the deal regardless of how much you like the house. Here is what mine looks like after years of doing this: If the foundation repair estimate exceeds 15 percent of the purchase price, walk away. Foundation work at this price point is rarely cosmetic, and once you open the walls you usually find worse problems than the initial inspection revealed. If the roof is original or past its expected lifespan and you cannot get a written quote for replacement before making an offer, walk away. I know sellers hate this, but an unsigned verbal estimate is worthless. Get it in writing from a licensed roofer.

If the property has any history of flooding, even minor, in the last ten years, walk away. Texas flash flood zones are not territory. Flood insurance alone can run $1,200 to $2,500 a year in affected areas, and that changes your monthly payment significantly. If the neighborhood vacancy rate is above 18 percent based on county records, walk away. That is a sign of structural decline that no amount of renovation will fix.
The Closing Process In Texas
Texas is a title company state, not an attorney state. That means the closing process is handled by a title company, and the buyer usually has less involvement than in other states. You will sign a mountain of paperwork at the title office, pay your closing costs, and drive away with the keys. The whole thing typically takes 45 to 60 minutes if everything is in order. Closing costs for a $90,000 purchase in Texas run roughly $2,800 to $4,200. This includes title insurance (the seller typically pays the owner's policy in Texas, but the lender's policy is on you), recording fees, origination fees if you are using a loan, and prepaid items like property taxes and homeowner's insurance. Property taxes in Texas are high – the average effective rate is around 1.8 percent, which means you are looking at roughly $1,600 a year in taxes on a $90,000 home. Factor that into your monthly payment calculation from day one. One thing that catches people off guard: Texas requires a homestead exemption filing if you plan to live in the property as your primary residence. This reduces your taxable value by $100,000 for school district purposes and locks in your assessment increase at no more than 10 percent per year. File this with your county appraisal district within one year of purchasing the home. Missing the deadline costs you money every year you forget about it.
Property Taxes And The Assessment Game
Here is a nuance most first-time buyers in this bracket miss. Texas does not have a state-level property tax cap like California. Your assessed value can jump significantly after purchase. However, the homestead exemption and the 10 percent cap on annual assessment increases for homesteaded properties provides some protection. Without the homestead exemption, a $90,000 home could see its assessed value reset to market value at closing, potentially pushing your tax bill from $1,600 a year to $2,400 or more depending on the county. Some counties in East Texas have lower tax rates than others. Walker County, where I focus a lot of my work, runs about 1.55 percent effective rate. Angelina County nearby is closer to 1.75 percent. The difference is not huge but it adds up over ten years. Always check the specific county tax rate before making an offer, not just the state average. I also recommend calling the county appraisal district directly and asking for the property's assessed value history. Sometimes the previous owner's assessed value is far below market value, and the jump after sale will be steeper than you expect. Knowing this in advance prevents unpleasant surprises at closing.

Long-Term Considerations
Buying a house under $100K in Texas is not a shortcut to wealth. It is a deliberate, sometimes tedious process that rewards patience and punishes impulse. The people who succeed in this market are the ones who treat it like a business transaction rather than an emotional purchase. They inspect thoroughly, they verify everything, they budget conservatively, and they walk away when the numbers do not work. The people who fail are the ones who fall in love with the potential instead of the reality. They skip inspections because they do not want to lose the deal. They underestimate repair costs because they watch too many renovation shows. They ignore neighborhood data because the house itself looks good. These mistakes are predictable, and they are avoidable if you approach this with a clear head and a detailed checklist. The market for Texas Homes For Sale Under 100K A Diamond In The Rough In The Lone Star State will always exist. There will always be houses that need work and sellers who are motivated. The trick is separating the genuine opportunities from the ones that look good in a listing photo but cost you everything in practice.

