Getting a Tesla in Canada Without Losing Your Mind
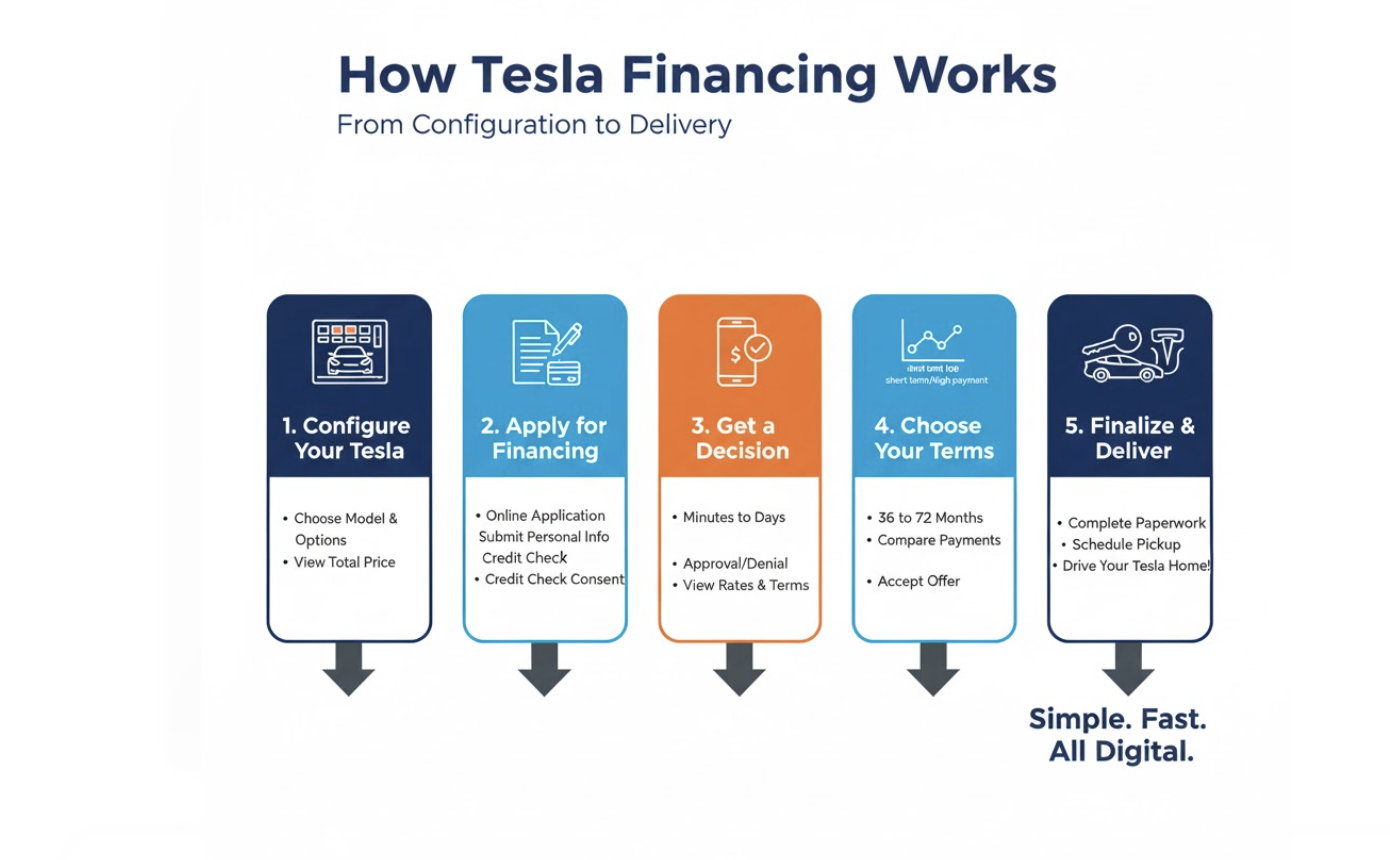
Financing a Tesla in Canada works differently than most people expect. You can't walk into a bank and just sign papers like you would for a used Civic. The process has specific quirks that trip people up, and if you know them ahead of time, it saves you a few days of back-and-forth with loan officers who have never dealt with EV purchases before. The main route most Canadians take is through Tesla's own lending partner, which is currently a partnership with TD Auto Finance. That means your application goes straight through the Tesla website during checkout, and the rate you get is whatever TD offers at that moment. It's fast—usually approved within 10 to 20 minutes if your credit profile is straightforward. But the rates aren't always competitive compared to what you might get elsewhere.
Tesla Financing In Canada Your Comprehensive Guide To Driving Home A New Electric Vehicle
Before I went through this myself, I assumed the deal was locked in at the rate Tesla showed. It isn't. The displayed rate at checkout is a starting point, and your actual approved rate depends on your credit tier, the model you're buying, and sometimes the incentives available that month. I found this out the hard way when my initially quoted rate of 8.49% dropped to 6.99% after I switched from the Model Y Long Range to the Model Y Performance. Same dealer, same bank, different vehicle trim. Tesla's configurator doesn't update the rate estimate in real time, so you might see one number and get approved at another. Always check your final approval email carefully before you commit. There's also a less obvious option: bringing your own financing. You can get pre-approved from a credit union, a mortgage lender, or an online lender like Simplii or ING Direct, and then use that loan to pay Tesla off at delivery. This often gets you a better rate, especially if you have excellent credit. The trade-off is that you handle the payoff logistics yourself, which adds a layer of complexity. Tesla will still deliver the car to you regardless, but you'll need to coordinate the fund transfer so you're not sitting on a driveway waiting for paperwork. One thing that catches people off guard is the difference between the cash price and the financed amount. The window sticker shows the base price, but the actual amount you finance includes the destination charge, any selected options, and then government taxes. In Canada, there's no federal EV tax credit anymore as of 2024, but some provinces still offer rebates. Quebec has the RAV program, and British Columbia has its own scheme, but these rebates are applied as a discount at the point of sale, not as a reimbursement. If you finance through Tesla directly, the rebate reduces your financed balance automatically. If you bring your own lender, you need to confirm they'll apply the rebate to your principal before you sign anything.
The application itself is painless. You put in your social insurance number, employment details, income, and your current address history. The system pulls a soft or hard credit inquiry depending on the stage—soft when you're just checking rates, hard when you submit the full application. That hard pull can drop your credit score by a few points, which matters if you're shopping around with multiple lenders simultaneously. Space out your applications by at least a few days if you're comparing options. There's a specific edge case I ran into that I wish someone had warned me about. I was financing a used Tesla through the certified pre-owned program, and my application kept getting flagged for manual review. It turned out the vehicle identification number on the title didn't match the one in Tesla's system because the car had been transferred between two provincial dealerships right before purchase. The mismatch triggered an automated fraud check. The workaround was straightforward once I knew what to do: I called Tesla financing directly, provided the bill of sale and the corrected VIN documentation, and they manually overrode the flag within two business days. If you're buying a used Tesla and the paperwork looks slightly off, don't just wait. Call them. The automated system won't resolve it on its own. Another detail that matters but nobody mentions: your down payment affects your rate more than you'd think. Tesla and TD seem to weight larger down payments favorably, possibly because they reduce the lender's risk exposure. Dropping from zero down to five percent can sometimes improve your rate by half a percentage point or more. It's worth running the numbers both ways before you lock in.
Get the Full Details
For those considering a lease instead of a loan, the math shifts significantly. Tesla's lease deals in Canada often come with promotional rates that are lower than their financing rates, especially on newer models. But leases come with mileage caps, wear-and-tear fees, and the obligation to return the car at the end of the term. If you drive more than 20,000 kilometers a year, leasing usually costs you more in the long run. The break-even point is somewhere around 15,000 to 18,000 kilometers annually, depending on the specific lease terms offered that quarter. The final step before delivery involves signing a bundle of documents, mostly through DocuSign. You'll see the loan agreement, the security agreement, and the ownership transfer paperwork. Take your time reading through the interest rate section and the prepayment penalty clause. Some Tesla financing agreements in Canada include a penalty if you pay off the loan within the first two years, typically calculated as three months' worth of interest. If you plan to upgrade or sell the car early, that penalty can add a few thousand dollars to your cost. Mortgage lenders and credit unions rarely have this clause, which is another reason to compare your options before committing. Delivery itself is usually scheduled two to four weeks after approval, sometimes longer if you've customized your order with premium wheels or a color other than the standard options. The delivery specialist will walk you through the car's features, which takes about an hour, and they'll process your final payment or set up your autopay arrangement on the spot. You drive home the same day, fully financed.