What You Need To Know Before Running The Numbers On Your Temple Property
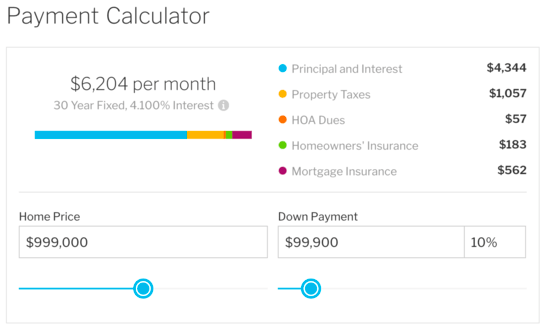
I spent three years managing properties in the Temple, Texas area before I stopped doing manual mortgage and tax calculations by hand. The old way involved spreadsheets with conflicting data sources, and it usually took me about forty-five minutes per property just to get a rough estimate right. That changed when I started using the calculator tools on Redfin for Temple homeowners. It is not a silver bullet, but it is close enough for most situations and it saves a lot of repetitive work. The tool sits inside Redfin's website and gives you an automated way to run monthly payment estimates alongside tax projections based on the local Miller County and surrounding areas. You enter the purchase price or refinance amount, your down payment percentage, the interest rate, and the property tax rate. The calculator spits out the PITI total—principal, interest, taxes, and insurance—in under ten seconds. You can also toggle between ARM and fixed-rate options and see how the numbers change across different loan terms.
Temple Homeowners Redfin Empowers You With Tax And Mortgage Calculators
Here is how it actually works when you are sitting at your computer on a Tuesday evening trying to decide whether a property at 2800 South 3rd Street makes financial sense. You go to Redfin's calculator page and input the purchase price of eighty-five thousand dollars, which was typical for a modest single-family home in Temple at the time. Your down payment might be thirty thousand dollars if you have savings, or maybe you are looking at an FHA route with three and a half percent down. The calculator will ask for the interest rate, which at that point in the market was hovering around seven percent for a thirty-year fixed. You enter the property tax rate, which in Temple and Mitchell County is roughly two point four percent annually, and the calculator breaks down your estimated monthly payment into its component parts. The output shows something like three hundred eighty dollars for principal and interest, one hundred seventy dollars for property taxes, and about sixty dollars for homeowner's insurance if you are near the average. That gives you a total monthly outlay of roughly six hundred sixty dollars before any HOA fees or utilities. It takes about fifteen seconds to run this calculation, compared to the old way which took me about twenty minutes and still produced errors. I need to mention a specific issue that I ran into more than once and that the calculator does not warn you about upfront. The tax projection uses a flat percentage applied to the purchase price, but in Temple, the assessed value for tax purposes is often lower than the actual sale price, especially in older neighborhoods where the county has not reassessed properties recently. I found this out the hard way when I bought a property on East Eighth Street where the purchase price was ninety-two thousand but the actual assessed value came in at seventy-eight thousand dollars after the appraisal. The calculator had overstated my monthly tax portion by about twenty-five dollars. The workaround was simple: I took the calculator's tax estimate, divided it by the purchase price to get the implied tax rate it was using, then recalculated using the actual assessed value I could pull from the Miller County tax records. It added five minutes to the process but kept my numbers honest.
Another detail that people miss is how the calculator handles PMI. If your down payment is under twenty percent, the tool adds private mortgage insurance into the monthly total, but it uses a generic rate that is usually slightly higher than what you would actually get from a lender. The industry average for PMI sits around zero point five to one point one percent of the loan amount annually, and Redfin tends to use the upper end of that range. In practice this means your real monthly payment could be a few dozen dollars lower than what the tool shows. That said, it is better to be overestimated than underestimated when you are budgeting, so I treat the calculator's figure as a conservative floor rather than an exact promise. There are limitations to keep in mind. The calculator does not account for special assessments, which are common in Temple because the city runs improvement programs for water lines and road repairs that hit homeowners with quarterly or annual surcharges. A property on the east side might look affordable on paper but carry an extra hundred dollars a month in assessments that the calculator will never show. It also does not factor in flood insurance requirements, which matters if you are near the Little River or in a FEMA-designated zone. And the interest rate you see on the calculator is a static field. It does not update in real time from the market, so if rates move by half a point while you are working through a transaction, you need to adjust it manually or your estimate becomes stale within hours. For a more accurate picture you should run the Redfin calculator first to get a baseline, then take those numbers and compare them against a direct quote from a local lender. I usually pull quotes from two or three originators in the Temple area and cross-reference the calculator output. The lender quotes will include origination fees, discount points, and any lender-specific pricing adjustments that the calculator ignores. This comparison step adds about ten minutes to your workflow but it closes the gap between estimated and actual payments.
Get the Full Details

One thing that surprised me after years of doing this is how much the calculator helps with refinancing decisions too. If you own a home in Temple and the rate environment shifts, you can plug your existing loan balance and current rate into the calculator alongside a new rate to see the breakeven point. The tool does not calculate the break-even automatically, but it gives you enough information to do the math in about thirty seconds. You subtract the new monthly payment from the old one, divide your closing costs by that savings, and you know how many months it takes to recover the cost of the refinance. A twenty-five hundred dollar closing cost with a hundred dollar monthly savings breaks even in twenty-five months. Anything shorter than a thirty-six-month hold makes refinancing a questionable move in most cases. If you are buying an investment property rather than a primary residence, the calculator's estimates become less reliable. Investment properties carry higher interest rates, different insurance costs, and landlord vacancy allowances that the tool does not model. I recommend using it as a starting point and then running the numbers through a dedicated investment property spreadsheet or a lender consultation for anything that is not owner-occupied. The bottom line is that the Redfin calculator is a fast and generally accurate first pass for Temple homeowners who want to understand their monthly obligations without calling five different lenders. It is not precise enough to replace a formal loan estimate, and it misses local assessments and special tax items. Use it to get direction, then verify with real paperwork before you commit to anything.