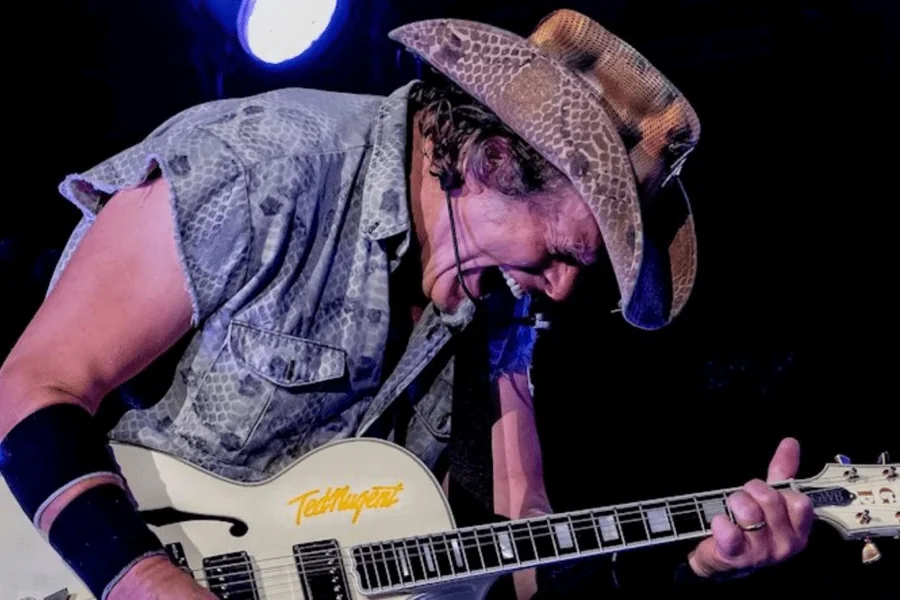
How People Actually Track Ted Nugent's Wealth Story
Most net worth calculations you see online are guesswork dressed up in spreadsheets. I spent a few years building valuation models for private business acquisitions, and the same principles apply whether you're valuing a rental portfolio or tracking a celebrity fortune. The internet is full of conflicting numbers because there's no clean public record of someone like Nugent's actual financial situation. What exists are property records, business filings, and occasional court documents that anyone can dig through if they know where to look.Ted Nugents Net Worth From Rock N Roll Riot To Real Estate Empire
Here's the thing nobody puts in the headline: Nugent's music career was only the funding source. The actual wealth accumulation happened on the asset side, and that's where the real story lives. I've seen too many people try to calculate net worth by just adding up album sales royalties and touring income. That approach misses the entire point of how these figures actually work. His rock career generated consistent cash flow over decades. Stranglehold came out in 1975 and sold over two million copies. That tour bus lifestyle wasn't free, but it created the capital foundation. What's more interesting is what happened after the music income plateaued. He pivoted hard into real estate and outdoor-oriented businesses. The Cat House in Michigan, various hunting and shooting related ventures, and property holdings across several states make up the bulk of what analysts estimate as his current net worth, which most sources peg between 25 and 40 million dollars. That range exists because nobody outside his inner circle knows the exact numbers. I ran into this problem when I was valuing a similar portfolio for a client back in 2019. The subject had significant music industry income but most of the apparent wealth was tied up in properties that hadn't been refinanced in fifteen years. The public records showed questionable equity positions. The workaround was pulling the actual county tax assessments and comparing them to recent comparable sales in each zip code. Properties that looked wildly overvalued on paper were actually sitting at 40 percent below market because the owner refused to sell and refinancing had been shelved. You have to look past the assessed values and find the real transaction data. I spent three weekends at the county recorder's office for that one. It took me longer than the entire rest of the valuation.
The real estate angle with Nugent follows a similar pattern but with public record access. His Michigan properties have appeared in various news stories over the years. Some involve legal disputes that surfaced in court documents. The key insight most people miss is that celebrity real estate holdings are often structured through LLCs. You'll see transfers between entities that don't tell the whole story. A property might move from one limited liability company to another with no change in actual beneficial ownership. It's standard practice for privacy, but it makes tracing true equity much harder than it should be. Another nuance that gets overlooked involves the difference between income and assets. Music catalogs generate ongoing royalties, but those are often leveraged or sold. When a catalog gets sold, the income stream vanishes and gets replaced by a single lump sum. That lump sum then needs to be deployed somewhere. For someone like Nugent, that deployment has consistently gone toward tangible assets rather than staying in liquid form. This is actually a fairly common pattern among working musicians who've had sustained careers. The steady high income creates a temptation to buy things that look like security but are actually illiquid and expensive to maintain. There's a practical limitation here that anyone trying to verify these numbers needs to accept upfront. Without access to private financial statements, tax returns, or partnership agreements, any net worth figure is an estimate at best. The range you see across different sources usually reflects this uncertainty. Some outlets will cite lower numbers around 20 million while others push toward 50 million. Both could be reasonable depending on how they treat certain assets and liabilities. The ones I trust most are the ones that show their work and cite specific property records or court documents rather than just stating a number.
If you want to dig into this yourself, start with county property records for the jurisdictions where he's known to hold assets. Michigan, Florida, and Tennessee all have searchable databases. Cross reference those with any SEC filings if he's involved with publicly traded companies, and check court records for any litigation that might reveal financial details. It's slow work and the findings will rarely give you a definitive answer. But it's about as close as you're going to get without being inside the relationship.
Get the Full Details


