Understanding What You Actually Pay When You Swipe
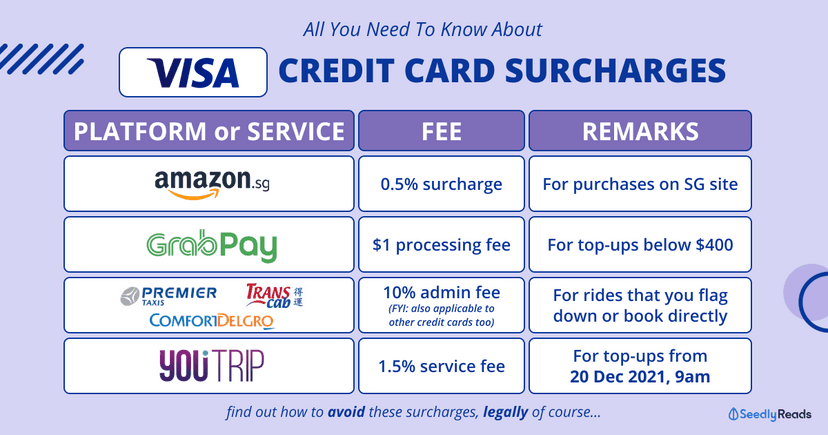
Singapore credit card fees are a messy collection of merchant surcharges, foreign transaction markups, late payment penalties, and cash advance rates that most people never read about until they see them on a statement. I've been working in payments for a long time and the complexity hasn't gotten better. It's gotten more confusing with newer cards adding layered reward structures that obscure what the actual cost is. The typical cardholder in Singapore will encounter merchant convenience fees when paying tuition at universities, government fees through credit card portals, insurance premiums via instalment plans, and the occasional hotel or car rental deposit that blocks a large amount for days. These aren't random. They follow patterns that banks exploit because people rarely check the fine print before committing.
Tech Singapore Charges On Credit Cards A Guide To Understanding The Fees And Fines
When people search for information about these charges, they usually find generic blogs that list the surface-level fees without explaining the hidden mechanics. The reality is that a 1.5% to 2% convenience fee on education or government payments is standard across DBS, UOB, and OCBC. But the fee isn't always disclosed at the point of selection. I've seen applicants complete a full registration form for a school placement only to be told at the final step that a 2% processing charge would apply if paid by credit card. By then they're already invested in the process and feel trapped into accepting it. Foreign transaction fees are where most people lose real money. Standard cards carry a 3.25% to 3.5% markup on every non-SGD purchase. Cards like the Citibank Rewards Mastercard or HSBC Life Black Card advertise zero foreign transaction fees, but they compensate by charging higher annual fees or offering weaker reward rates at home. There is no free option. You pick your compromise.
How Cash Advances Actually Work
Cash advances are the silent wealth transfer in credit cards. The interest rate starts accumulating from day one. There is no grace period. The typical rate sits between 26% and 28% per annum, calculated daily. A S$1,000 cash advance taken for three days costs approximately S$2.30 in interest alone, plus a transaction fee that ranges from S$30 to S$50 or 5% of the amount, whichever is higher. I once helped a friend who accidentally used his credit card at an ATM in Changi Airport. He needed cash for a taxi because his phone was dead and he couldn't pay with PayNow. The machine dispensed S$200. He thought he'd transfer it back the next day. The fee was S$30 and the interest had already started ticking. By the time he noticed and paid it off five days later, the total cost was roughly S$34.50 on a S$200 withdrawal. That's a 17% effective cost for five days. Annualised, it's catastrophic. The workaround is simple and it's not widely known. Use your debit card at ATMs instead. Singapore debit cards don't have cash advance fees. The daily limit might be lower, but for emergency amounts under S$1,000 it's usually sufficient. If you need more, pre-arrange a short-term overdraft from your bank before you travel. It costs fractions of what a cash advance will.
Get the Full Details
Annual Fees and What They Actually Buy You
Singapore credit cards range from no annual fee to over S$500 for premium cards. The question isn't which card has the lowest fee. It's whether the benefits justify it. A S$198 annual fee card like the DBS Fast and Fresh Visa might seem expensive until you factor in that a single flight booking through the bank's travel portal can return S$50 to S$100 in rebates. After two transactions the card has paid for itself. Premium cards above S$400 annually typically include airport lounge access, travel insurance, and concierge services. The travel insurance alone on cards like the UOB Privilege Privilege Card or the Citi PremierMiles Card can be worth S$200 to S$400 if you travel more than twice a year. But here's the counter-intuitive part that most people miss: the best value cards are often the mid-tier ones with annual fees around S$150 to S$250. They offer meaningful rebates without the heavy lifestyle perks that most cardholders never use. Lounge access means nothing if you commute on the MRT. Travel insurance is useful but only if you actually travel internationally, which for many Singaporeans is once or twice a year at most. I've seen people hold S$600 annual fee cards for years and never visit a single lounge, never file a travel insurance claim, and barely use the concierge. They're paying half a percent of their income for benefits they never touch. Switching to a mid-tier card with similar cashback or mile structures cut their effective annual cost by 60% while maintaining nearly identical earning power on purchases.
Late Payment Penalties and the Credit Score Spiral
A single missed payment in Singapore triggers a late fee of around S$30 to S$60 depending on the bank, and more critically, it gets reported to the Credit Bureau Singapore. The impact on your credit score can last seven years. This isn't theoretical. I've reviewed applications for mortgage refinancing where a single S$50 late fee from three years ago became the reason a bank rejected a otherwise solid application. The underwriter saw the blemish and the risk model penalised accordingly. The practical solution isn't willpower. It's automation. Set up a partial payment autopay that covers at least the minimum, ideally the full statement balance. The difference between minimum payment and full payment is where people get crushed. Minimum payment keeps the account open but extends the debt for years with interest compounding daily. A S$2,000 balance paid at the minimum rate of 2.5% per month takes roughly four years to clear and costs over S$1,100 in interest alone. Paying the full amount costs nothing extra.
Overlimit Fees and Hidden Transaction Charges
Many Singapore banks have moved away from traditional overlimit fees, but they still allow transactions that exceed your credit limit under certain conditions. The charge for going over limit, when it applies, is typically S$30 to S$50. More common are the merchant category code (MCC) restrictions that cause unexpected rejections or fees. Some banks block payments to gambling sites, cryptocurrency exchanges, and certain remittance services. Attempting these payments doesn't always generate an explicit fee, but the transaction may be declined, which wastes time and can disrupt bookings or purchases. I encountered this with a client who was trying to pay a cross-border property management fee to a Malaysian company. The payment gateway accepted his card details, but his Singapore bank flagged the MCC as cross-border property services and declined it. By that point the booking window had closed and the property manager charged a late payment penalty. The workaround was to call the bank beforehand to confirm which MCC categories were restricted, then use a different card or wire transfer for those specific payments. It added ten minutes to the process but saved a S$150 penalty.

What Nobody Tells You About Reward Earnings
Reward rates in Singapore are not uniform across all spending categories. Most cards offer baseline rates of 0.3% to 1% on general spending, with boosted rates of 3% to 5% on selected categories like dining, groceries, or online shopping. The trap is that these boosted categories rotate quarterly or monthly. A card that offers 5% cashback on dining in Q1 might switch to 1% in Q2 and move the bonus to online shopping instead. The people who maximise rewards don't track every category change manually. They set up a simple spreadsheet or use a free tool like the Bank Bazaar or MoneySmart reward comparison pages to check quarterly category rotations. I maintain a personal tracking sheet that I update every three months. It takes about twenty minutes and has saved me roughly S$200 to S$400 annually compared to blindly using whatever card I picked up that morning. Another nuance that banks don't advertise: some rewards are capped. A card might advertise 5% cashback on dining, but the cap is S$30 per month. If you and your partner eat out frequently, you'll hit that cap within two weeks and the remaining dining spend earns the baseline rate. Knowing the cap structure before you plan your spending is essential. Without it, you're optimising for the headline number that doesn't reflect your actual usage pattern.
Practical Steps to Minimise Your Charges
Start by pulling your last twelve months of credit card statements. Look for patterns. Convenience fees on education or government payments, foreign transaction charges on holiday spending, cash advance fees from ATM withdrawals, late payment fees from autopay failures. These add up. I found that one of my clients had accumulated S$340 in convenience fees over two years simply by not realising that direct payment portals at polyclinics and government agencies accepted bank transfer at no additional cost. Switching to GIRO or PayNow for those specific payments eliminated the recurring charge entirely. Review your card portfolio annually. If you hold multiple cards with overlapping benefits, consolidate to the one that gives the best effective rate on your actual spending pattern. A card that earns 1.2% on everything beats a card that earns 3% on dining and 0.5% everywhere else if you only dine out once a month. The math doesn't lie but it requires doing the math rather than assuming the headline percentage is what matters. Set autopay for the full statement balance. Not the minimum. Full balance. This single action eliminates late fees, avoids interest charges entirely, and protects your credit score from accidental misses. The only risk is insufficient funds in your checking account, which is why maintaining a small buffer equal to at least one statement cycle's spending is prudent. I keep mine at roughly double my average monthly spend. It's dead money sitting in a low-interest account, but it's cheaper than any late fee or interest charge that the alternative would generate.