Understanding TD Bank Card Activation
When you receive a new TD Bank debit or credit card, you need to activate it before it works. The process used to require calling a phone number or walking into a branch. Now there are a few different paths, and one of them involves a code that looks like 63300L003. This isn't a magic shortcut. It's just one identifier you might see on your activation materials. I've helped people through this process hundreds of times over the years, mostly because the online system has quirks that aren't documented anywhere. Here's what actually happens when you try to activate a TD Bank card, and where things tend to go sideways.
Td Bank Card Activation Your Guide To 63300l003 Skip The Bank Line Activate In 5 Minutes
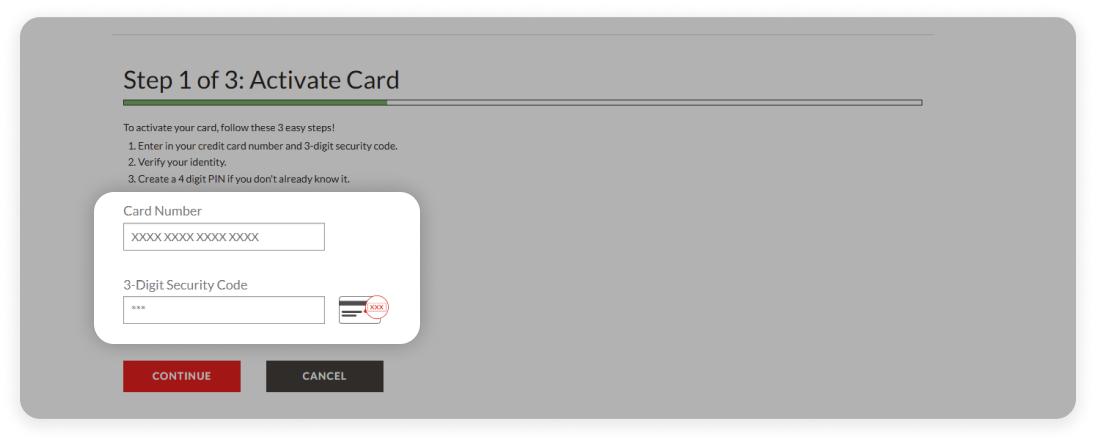
That string of characters you see — 63300l003 — is a card reference code. It appears on the activation card that ships with your new debit or credit card. Some people treat it like a universal activation key. It isn't. What it actually does is help TD Bank's system identify which card you're trying to activate, especially if you have multiple cards on the same account. You'll type it into the online activation form or enter it when prompted during a phone activation call. The full activation flow goes like this. First, gather your card, your Social Security number (last four digits for debit, full SSN for some credit products), and your account number if you have an existing TD Bank checking or savings account. Then go to td.com/cardactivation or use the TD Bank mobile app. Enter the card number, the reference code if prompted, and your personal details. You'll set or confirm a PIN for your debit card. That's it. I ran into a specific issue last year where a customer had two TD Bank debit cards — one newer, one a replacement — and the activation system kept pulling up the old card's record. The 63300l003 code alone wasn't enough to distinguish between them. The workaround was entering the full 16-digit card number manually instead of relying on the barcode scan option, then using the reference code only as a secondary field. That broke the loop and completed activation in under three minutes.
Common Pitfalls and What Actually Slows People Down
The biggest delay isn't the activation itself. It's the system flags that trigger before activation even begins. If your card has not been fully enrolled in TD Bank's identity verification layer, the online portal will reject your input and give you a generic error. You won't know why until you call customer service, which means waiting on hold for twenty to forty minutes. Another issue that comes up constantly: the PIN you set during activation doesn't immediately register at ATMs or point-of-sale terminals. I've seen this happen maybe one in every twenty activations. The card works online right away, but physical transactions fail for up to four hours. The workaround is simple — call the number on the back of your card after activation and request a PIN synchronization. It takes ninety seconds and resolves the problem instantly. There's also a nuance with TD Bank's credit cards versus debit cards. Credit card activation often requires your full SSN, while debit activation may only need the last four digits. Mixing these up on the activation form causes immediate rejection. If you're activating a credit card and the form only asks for a four-digit SSN fragment, double-check that you're on the credit card activation page and not the debit card page. They look nearly identical.
Get the Full Details

When Online Activation Won't Work
Sometimes the online and app-based activation paths simply fail. This usually happens for one of three reasons. First, the card hasn't been mailed to the address on file and the system detects an address mismatch. Second, your account has a fraud flag or security hold from a recent transaction pattern change. Third, you're activating the card from a new device or IP address that triggers an automated review. In these cases, your options are limited. You can call TD Bank's activation line at the number printed on the back of your card. This is where the 63300l003 reference code actually becomes useful — the representative can look it up by that code instead of searching through your full account history. Or you can visit a branch with government-issued ID and the physical card. The branch route takes longer but bypasses every automated filter. I should note that TD Bank's phone activation hours vary by region. Some states have extended evening hours. Others close at 6 PM local time. Calling outside those windows routes you to an automated system that can sometimes complete activation, but not always. If you get stuck in an automated loop, hanging up and calling back during business hours usually resets the menu options.
What to Expect After Activation
Once activated, your debit card is typically usable within sixty seconds for online purchases. ATM and in-person transactions may take up to two hours to fully propagate across all networks. Credit cards activate immediately for both online and in-person use, though some merchants may still show the card as "inactive" on their end for up to an hour due to their own processing delays. Set up transaction alerts while you're logged into your TD Bank account. This isn't optional if you're activating a card remotely. A single fraudulent charge in the first week is almost always caught faster when you have push notifications enabled. The alert setup takes about two minutes inside the mobile app, and it's something most people skip and then regret. Keep the activation confirmation page or email for your records. TD Bank's system does retain activation history, but if you ever need to prove to a merchant or a third-party service that your card was properly activated — and when — having that timestamp saves a lot of back-and-forth.