What Actually Happened When TD Bank Rolled Out Their Automation Stack
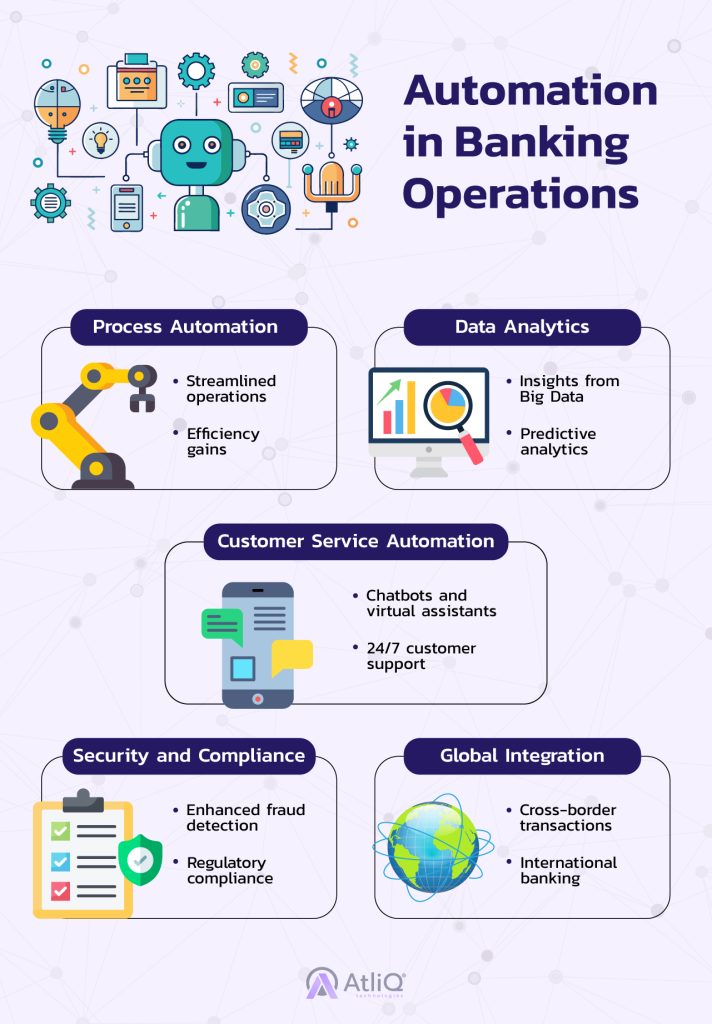
I spent roughly three weeks troubleshooting a client integration where the TD Bank automated workflows kept dropping transaction flags. The issue wasn't the API itself. It was the new fraud-scoring layer that TD introduced mid-2025, which reshuffled how certain account types get processed through their automation pipeline. That kind of thing doesn't get announced with a press release. You find out when your nightly reconciliation batch fails at 2:14 AM for the third time in a row. The term comes up a lot in fintech circles, but the reality is narrower than most vendors make it sound. TD Bank has been slowly replacing manual touchpoints across customer onboarding, fraud detection, loan servicing, and internal operations with automated pipelines powered by machine learning models. This isn't a single product you can download. It's an infrastructure shift that touches multiple departments and systems. The customer-facing side shows up as faster account approvals, reduced call times, and more consistent service outcomes. The backend side involves changes to how data flows between legacy systems and newer microservices. Here's something most people writing about this get wrong. The AI component isn't the main driver of change. It's the automation layer that came first. TD started wiring up their core banking processes to event-driven workflows about four years ago. The AI models were layered on top of that foundation. You can't run predictive fraud scoring if your transaction data hasn't been standardized and piped into a real-time stream. That groundwork took years of unglamorous engineering work.
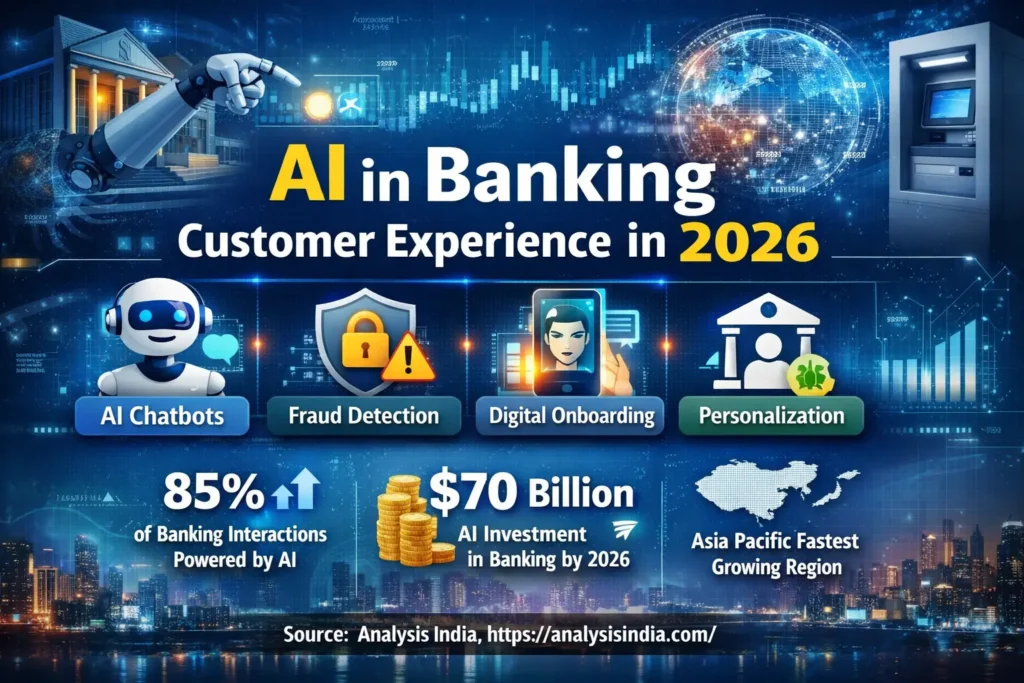
When you look at customer onboarding, for instance, the old process involved a banker reviewing uploaded documents manually, sometimes flagging items that needed human verification, which meant waiting. Now the system scans IDs, cross-references watchlists, and routes edge cases to specialists. Most straightforward applications clear in under five minutes. I had a contact who runs a small business banking group, and they reported that average time-to-account decreased from about 48 hours to roughly 20 minutes for standard business accounts. That's not a marketing claim. That's what their operations team told me directly. The loan processing side shows a similar pattern. Automated credit assessment tools evaluate applications using alternative data sources alongside traditional credit scores. TD's system can pull bank statement data, employment verification, and even some cash flow patterns to build a richer picture than a FICO number alone. Again, this only works because they spent significant time cleaning up their data architecture first. The model is only as good as the data it's fed. Fraud detection is where the automation gets most visible to customers. TD uses behavior-based anomaly detection that learns individual spending patterns rather than relying solely on rule-based thresholds. This means fewer false positives for legitimate transactions and better detection of genuinely suspicious activity. The tradeoff is that the system occasionally misclassifies edge-case behavior, especially for customers who travel frequently or have irregular income patterns. I've seen accounts get temporarily restricted because the model couldn't reconcile a month of unusual activity. The workaround is straightforward but not well-publicized: customers can pre-register travel plans through the app and add notes to their account profile explaining recurring irregular expenses. This the model context it normally lacks.
Another area worth noting is internal operations. TD has automated significant portions of their back-office work. Reconciliation, compliance reporting, and document processing have all been partially or fully automated. This doesn't mean humans are replaced. It means junior staff who previously spent hours on manual data entry now handle exception cases and customer escalations instead. The efficiency gain is real, but so is the organizational friction. Retraining staff and adjusting workflows around automation creates short-term disruptions even when the long-term outcome is better. If you're looking at this from a technology perspective, a few things matter more than the AI hype. First, understand that TD's approach is built on top of their existing legacy infrastructure. They haven't ripped out their core banking platform and replaced it. They've wrapped newer services around it. This means some processes still route through older systems, which introduces latency and occasional bugs that wouldn't exist in a greenfield build. Second, the automation is rule-heavy at the operational level. Many of the decisions that look "AI-powered" are actually deterministic rules with some probabilistic components. Only the higher-order tasks like fraud prediction and credit assessment rely heavily on machine learning. The biggest limitation I've observed is that automation doesn't handle truly novel situations well. If a customer's circumstances fall outside the training data distribution, the system either defaults to a conservative outcome or fails entirely. I encountered this when working with a client whose business model involved rapid inventory turnover with seasonal revenue spikes. The loan assessment model initially flagged them as high-risk because their cash flow pattern didn't match typical small business profiles. The resolution required manual review and a conversation with the underwriting team to adjust how their specific industry was evaluated. This kind of thing happens enough that TD has had to build escalation pathways into their automated systems.
Get the Full Details
From a customer experience angle, the net result is mixed but leaning positive. Most routine banking tasks are faster now. Account openings, loan applications, and basic fraud disputes move through the system with less human intervention. But when something goes wrong, the automated system can feel unhelpful. Chatbots and virtual assistants sometimes loop customers through options that don't address their actual problem. Getting to a human representative requires persistence. The phone trees are designed to filter out as many calls as possible before they reach live agents. The technology roadmap suggests more integration between TD's various platforms. There are plans to connect the mobile app, online banking, branch systems, and call center tools into a more unified experience. This would reduce the friction customers currently feel when switching between channels. It also means more automation touching more parts of the customer journey. More automation isn't inherently better or worse. It just means there are more places where things can go wrong. For businesses that rely on TD's infrastructure, the practical takeaway is to monitor their release notes and API documentation closely. TD tends to push infrastructure changes without much fanfare. A system that worked last quarter might behave differently after a backend update. The best approach is to build your integrations with error handling and fallback logic. Assume something will break at an inconvenient time. It will.
The broader trend here is that TD Bank is moving from a traditional bank with some digital features toward an institution where most routine processes run without human involvement. This is happening across the industry, not just at TD. The question isn't whether this direction is correct. It's whether customers and businesses can adapt to a system where the default interaction is with automation rather than a person. The answer so far is that most people tolerate it for simple tasks but grow frustrated quickly when exceptions arise. TD has work to do on the exception handling side.